Skip to main content

Natural Gas

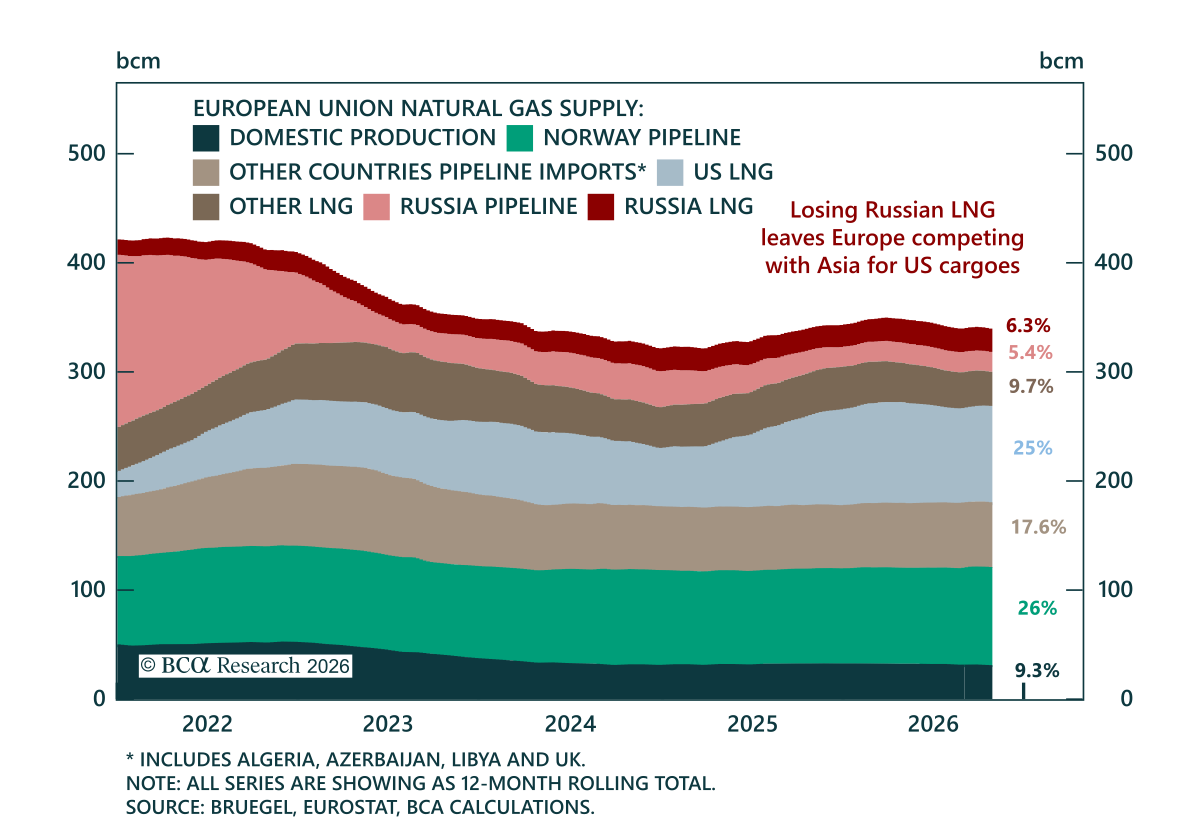
The EU ban on Russian LNG imports leaves TTF heading into Q1 2027 in a tighter market. The ban comes into effect on January 1, 2027, despite storage at its lowest seasonal level in over a decade. Nearly all Russian LNG reaching the EU comes from the Arctic…
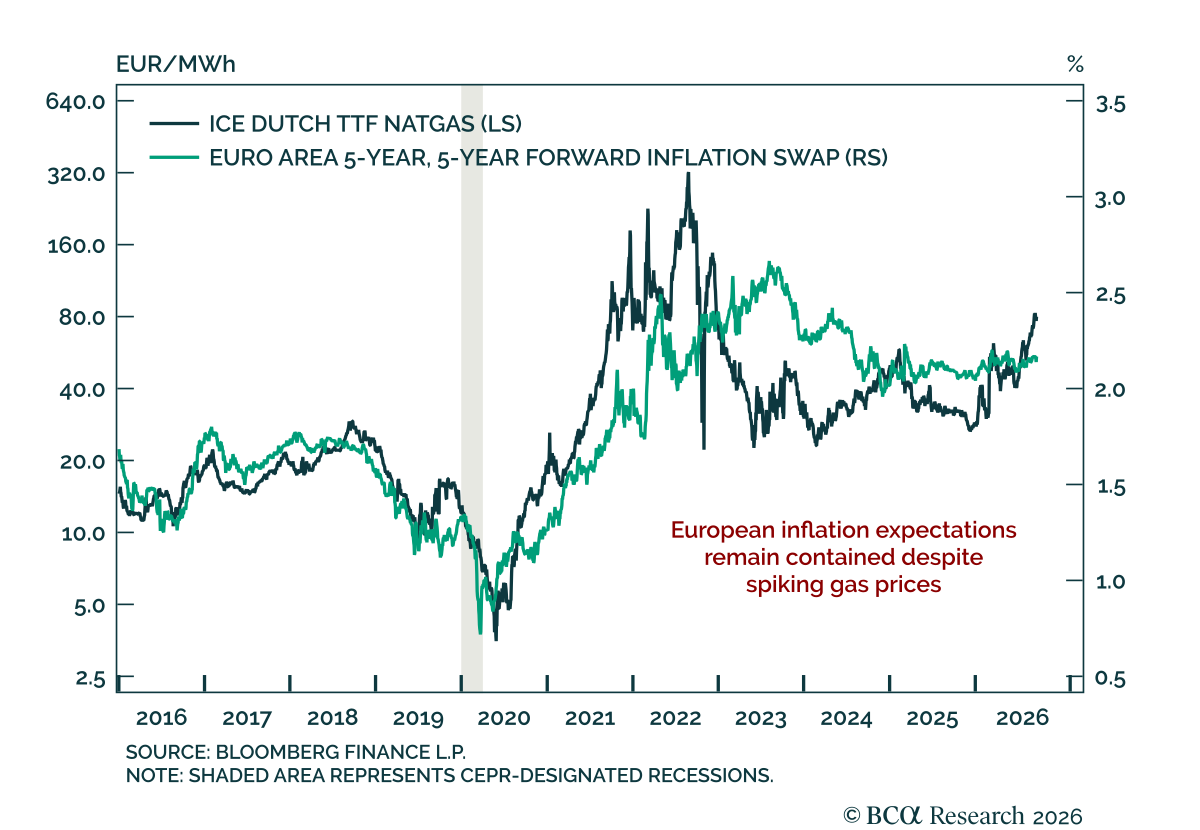
European natural gas prices have surged above recent highs, but the absence of a corresponding rise in longer-term inflation expectations argues against the ECB hiking deeply into restrictive territory. ICE Dutch TTF prices, the European benchmark, have moved…
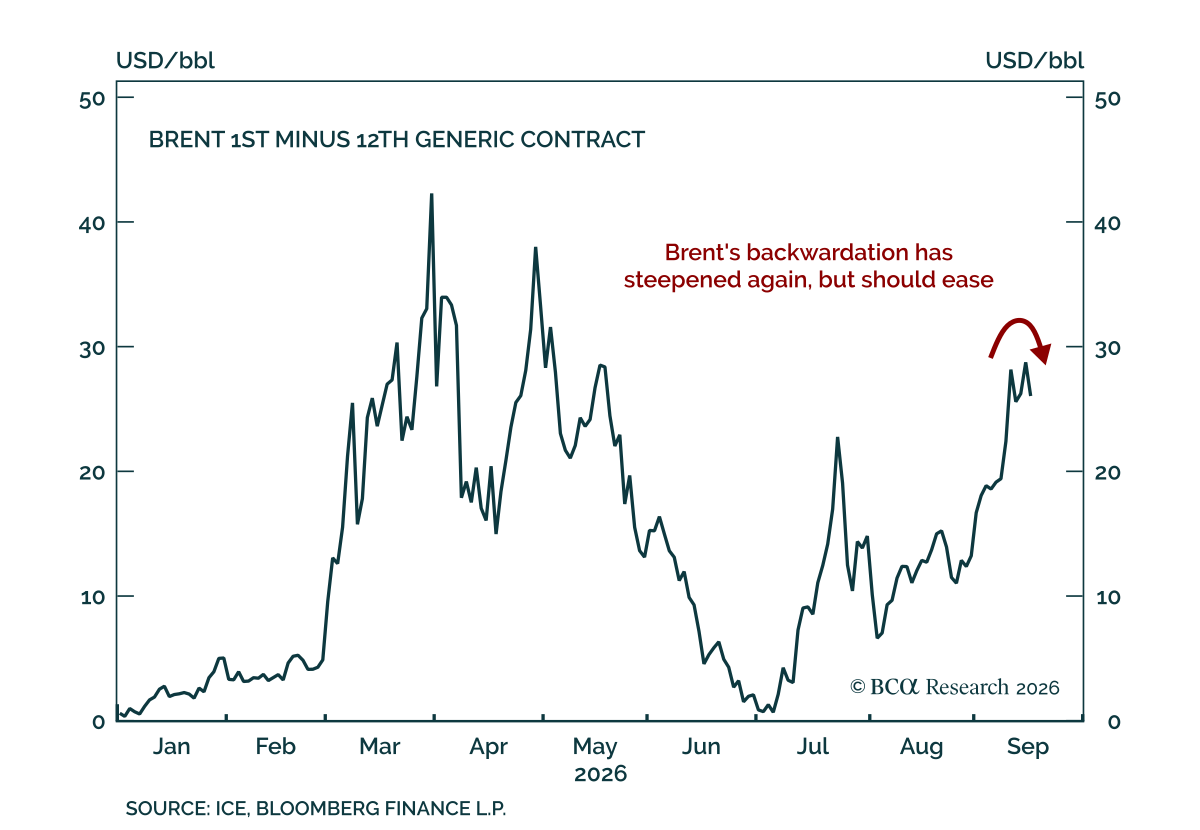
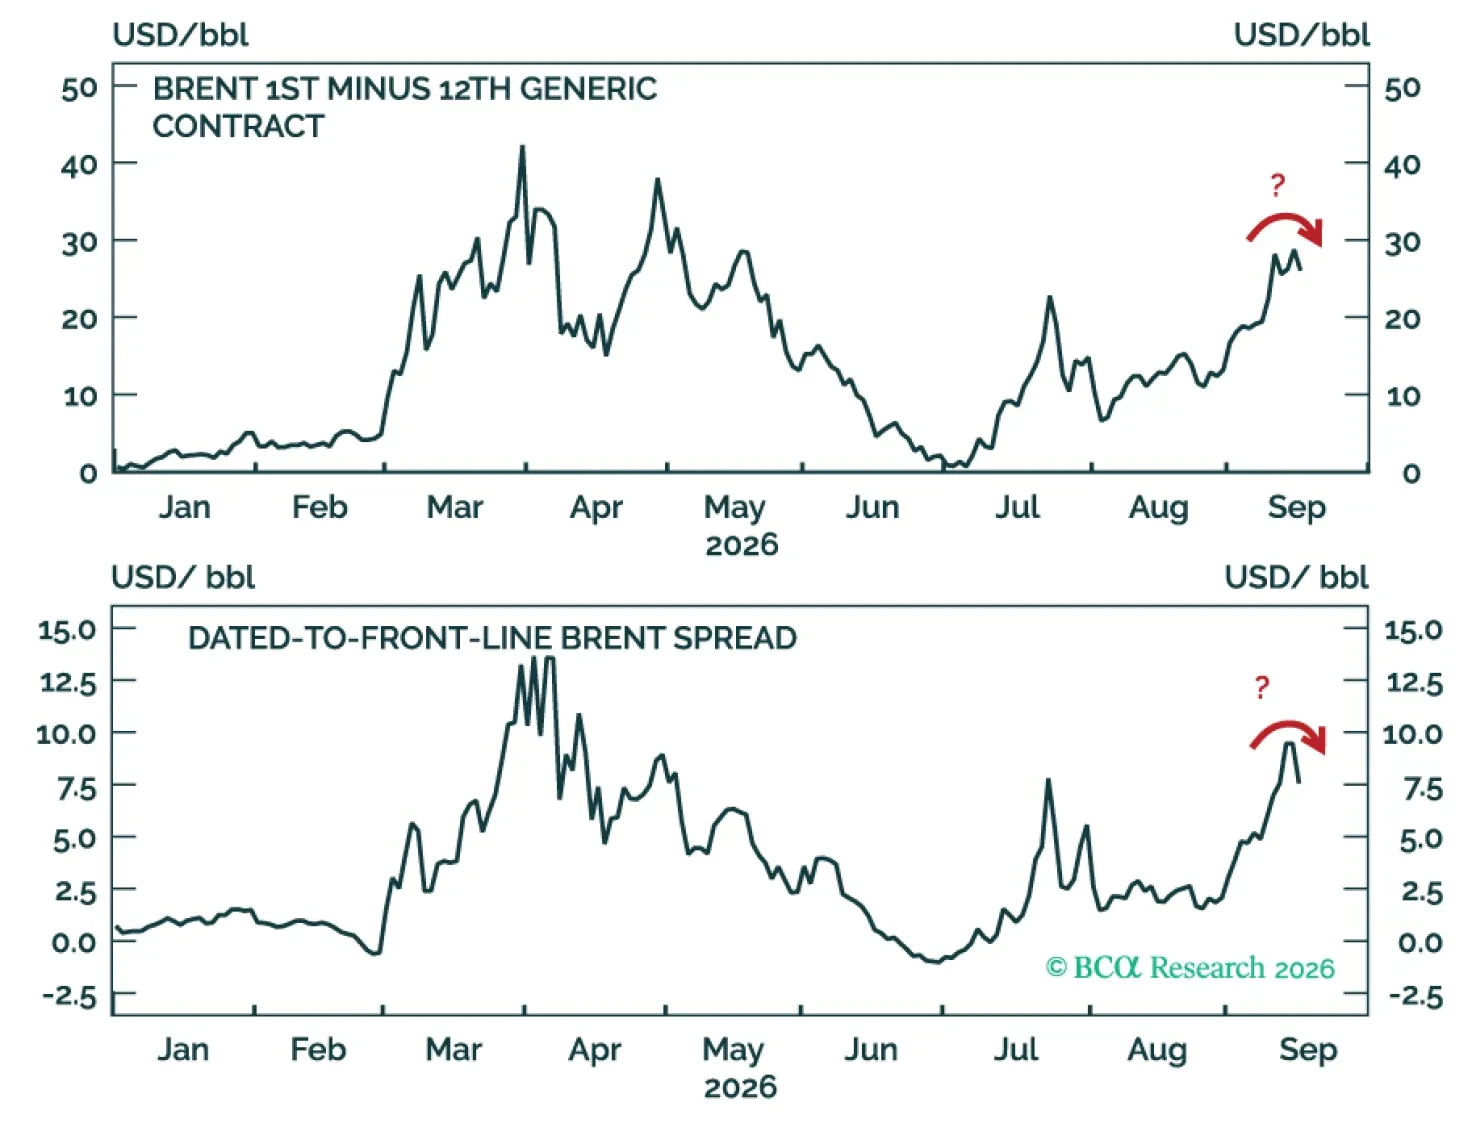
Our Commodity strategists expect rising dark transits through the Strait of Hormuz to keep cushioning the blow to global crude supplies. Middle Eastern seaborne exports have continued to climb through September despite the latest escalation in hostilities, a…

Recent oil market developments expose the limits of the adjustment mechanisms that have cushioned the global market since the Hormuz closure began. Fortunately, Hormuz dark transits have become the dominant shock absorber in recent months, and rising flows should help mitigate the latest supply disruption going forward.
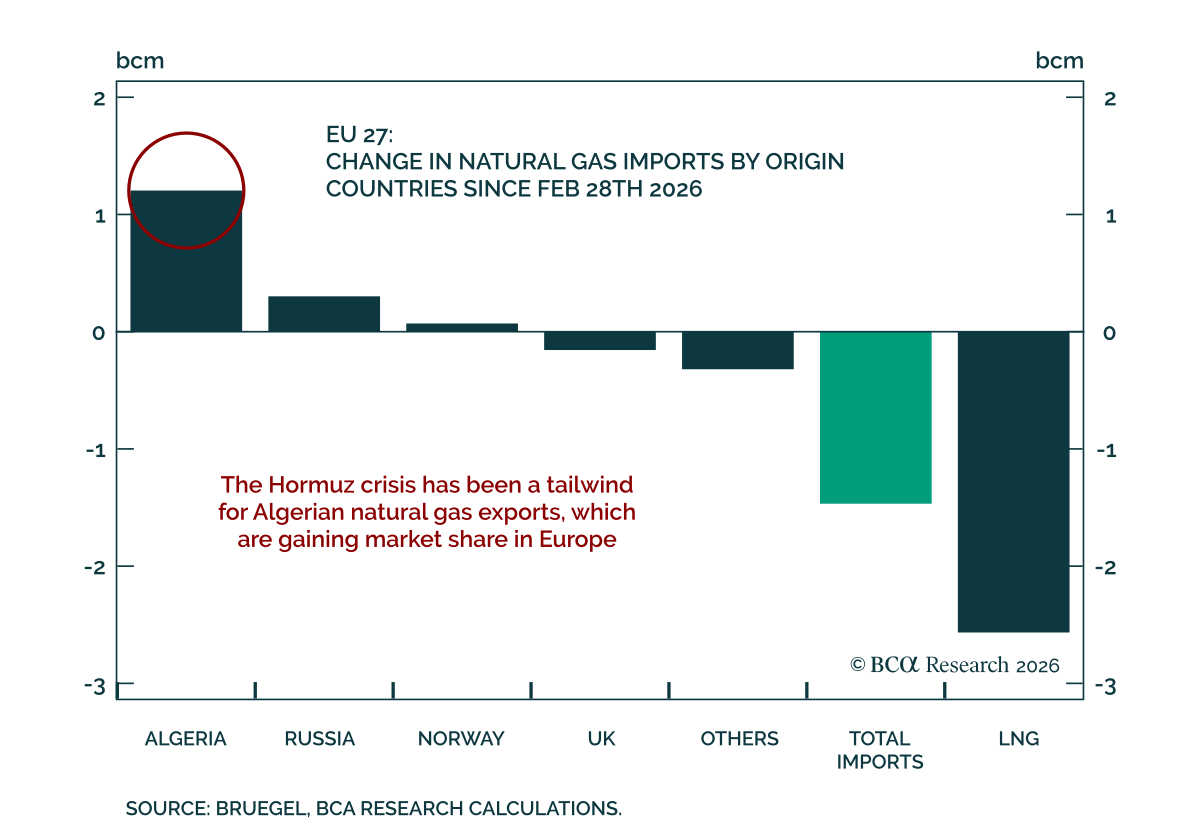
Algeria may offer the European Union some relief from its natural gas supply squeeze. Algeria has become the EU’s third-largest natural gas supplier, delivering around 40 billion cubic meters in 2025, accounting for roughly 14% of total EU imports. The timing…
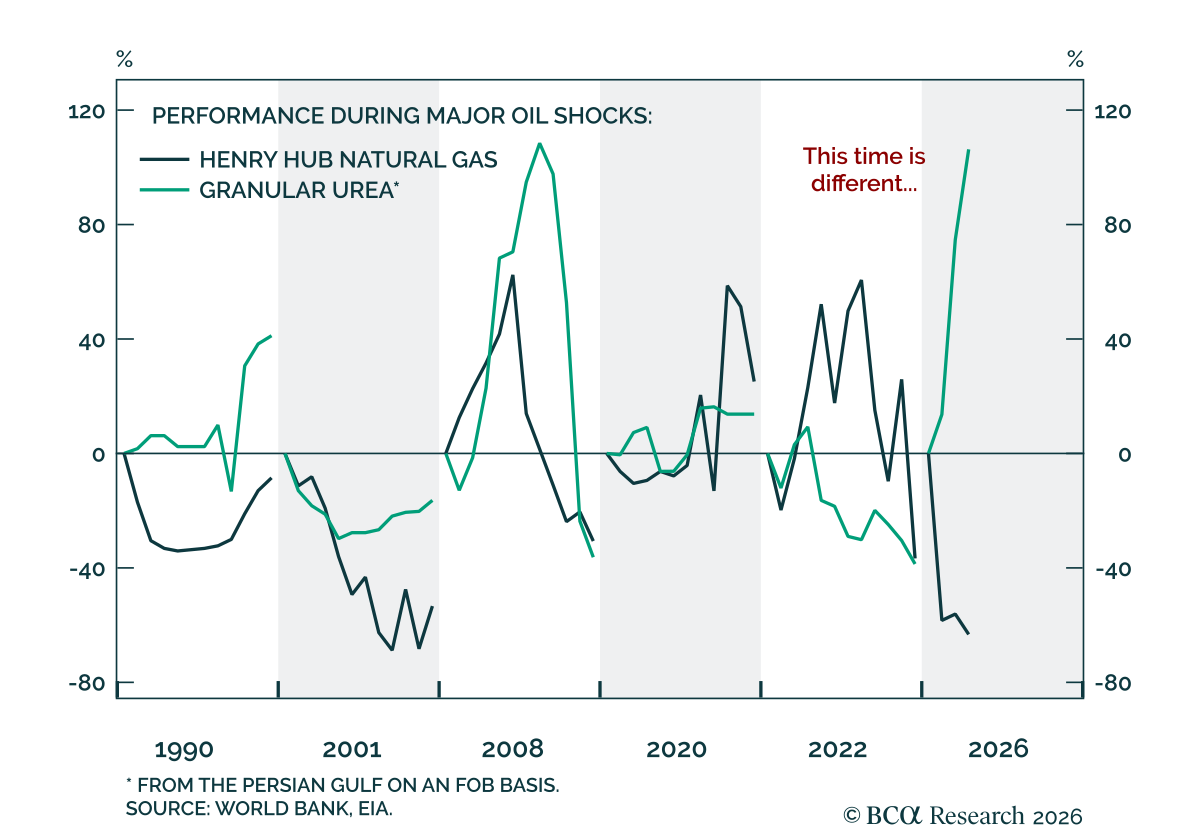
The Hormuz crisis is likely to disrupt urea markets; trade routes and production capacity can only adjust slowly and at meaningful cost. Our Chart Of The Week comes from Jose Yanes, analyst in our GeoMacro team. In the Hormuz crisis, urea sits between the…
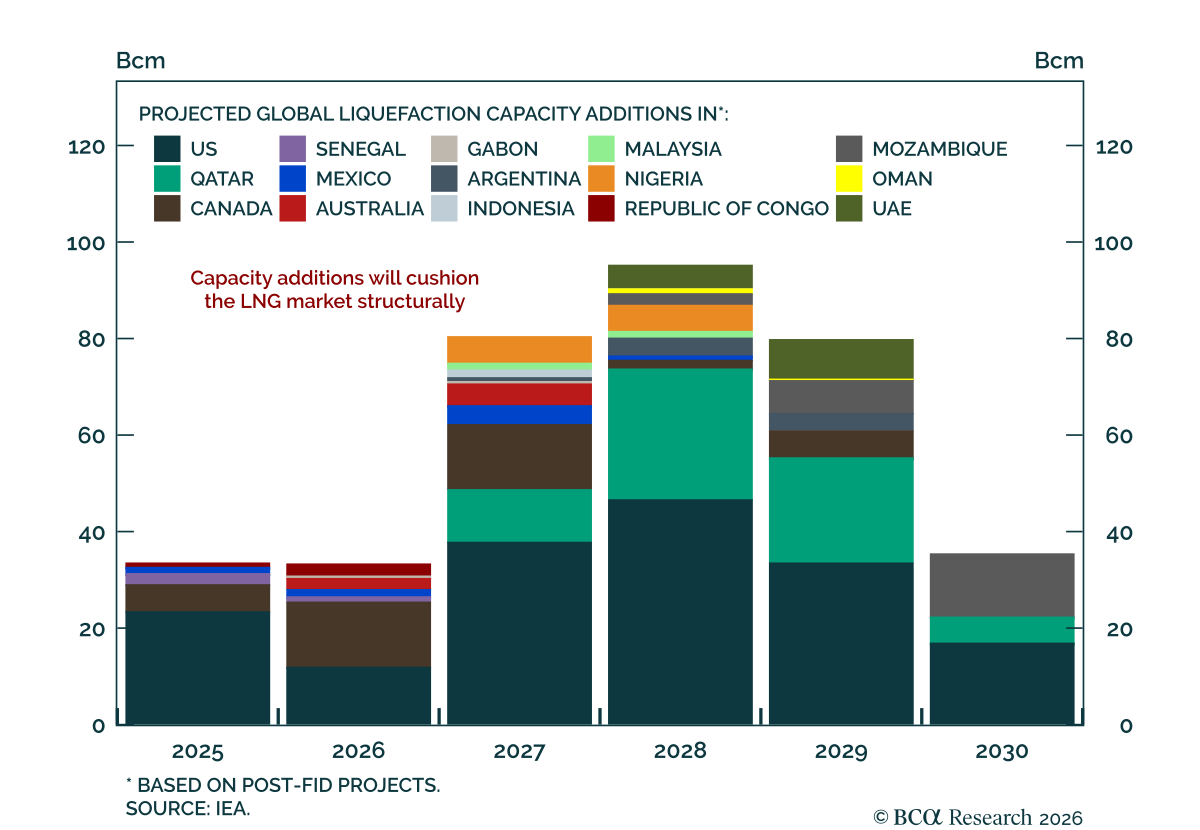
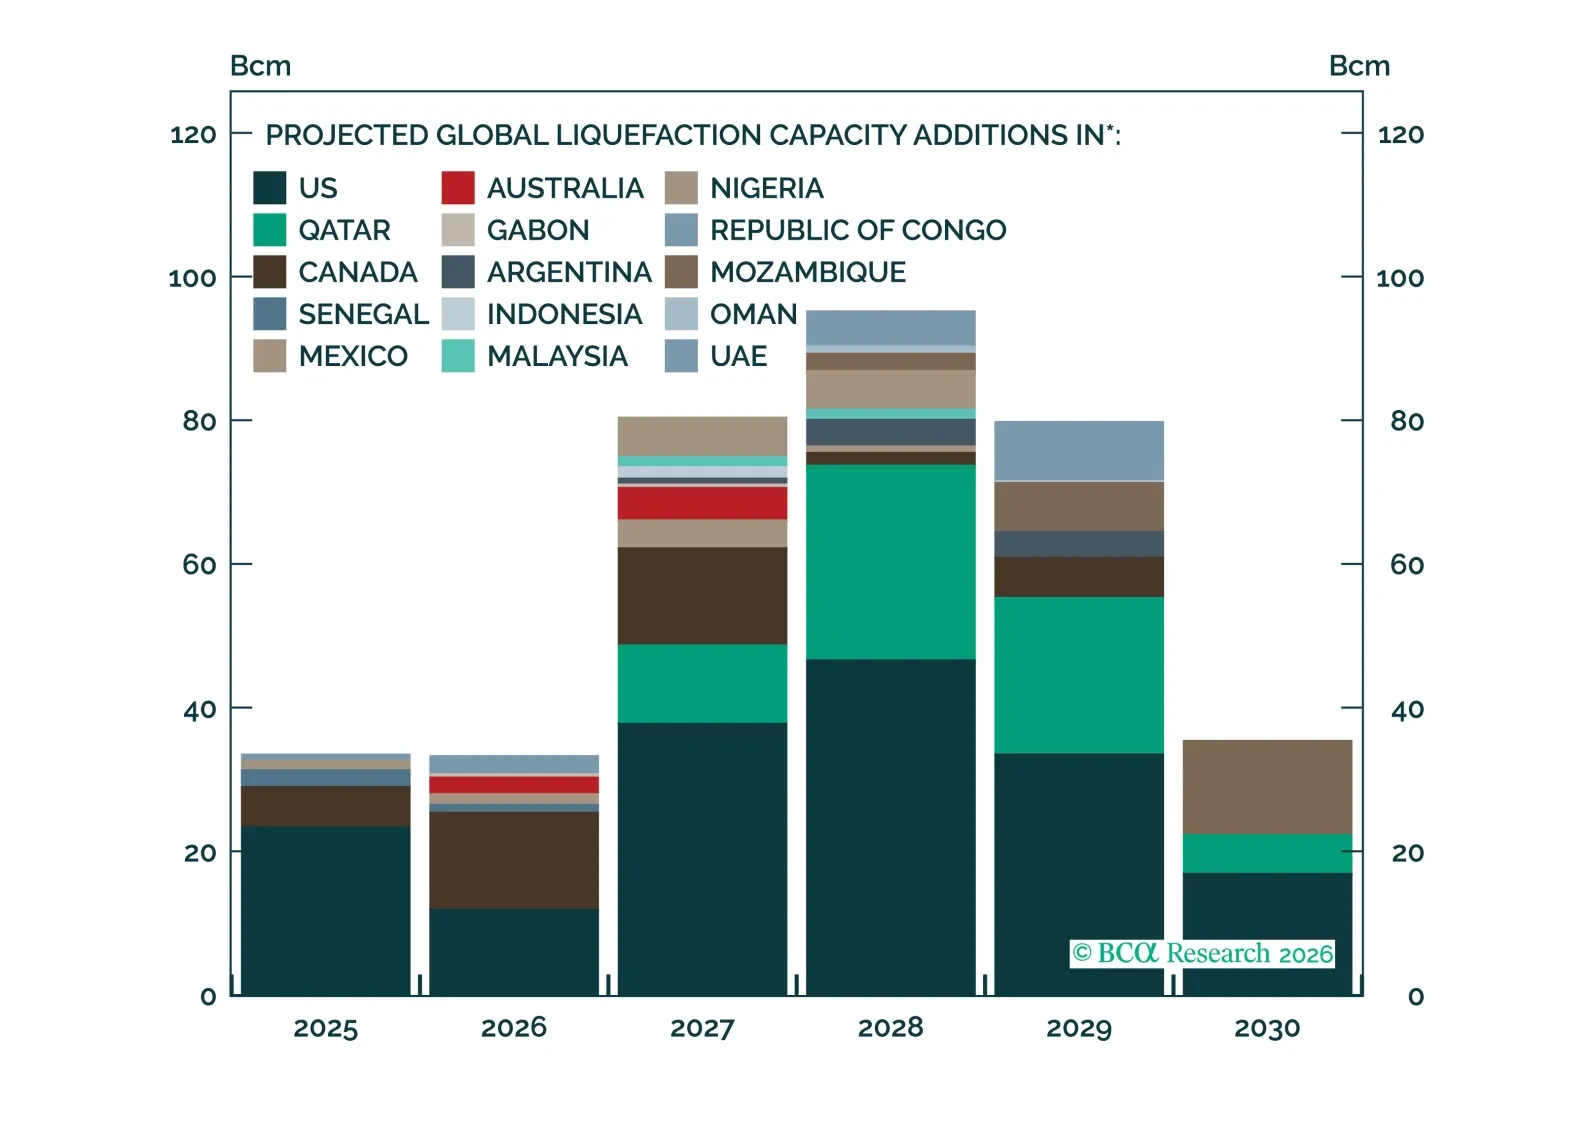
Our Commodity strategists expect natural gas prices to stay elevated through 2026, with a structural shift into oversupply coming from 2028 onward. The Strait of Hormuz disruption remains the binding constraint on Persian Gulf LNG exports, and even a May…

The Iran war has damaged LNG production capacity and halted tanker flows through the Strait of Hormuz. We assess the conflict's impact on LNG markets over cyclical and structural horizons.
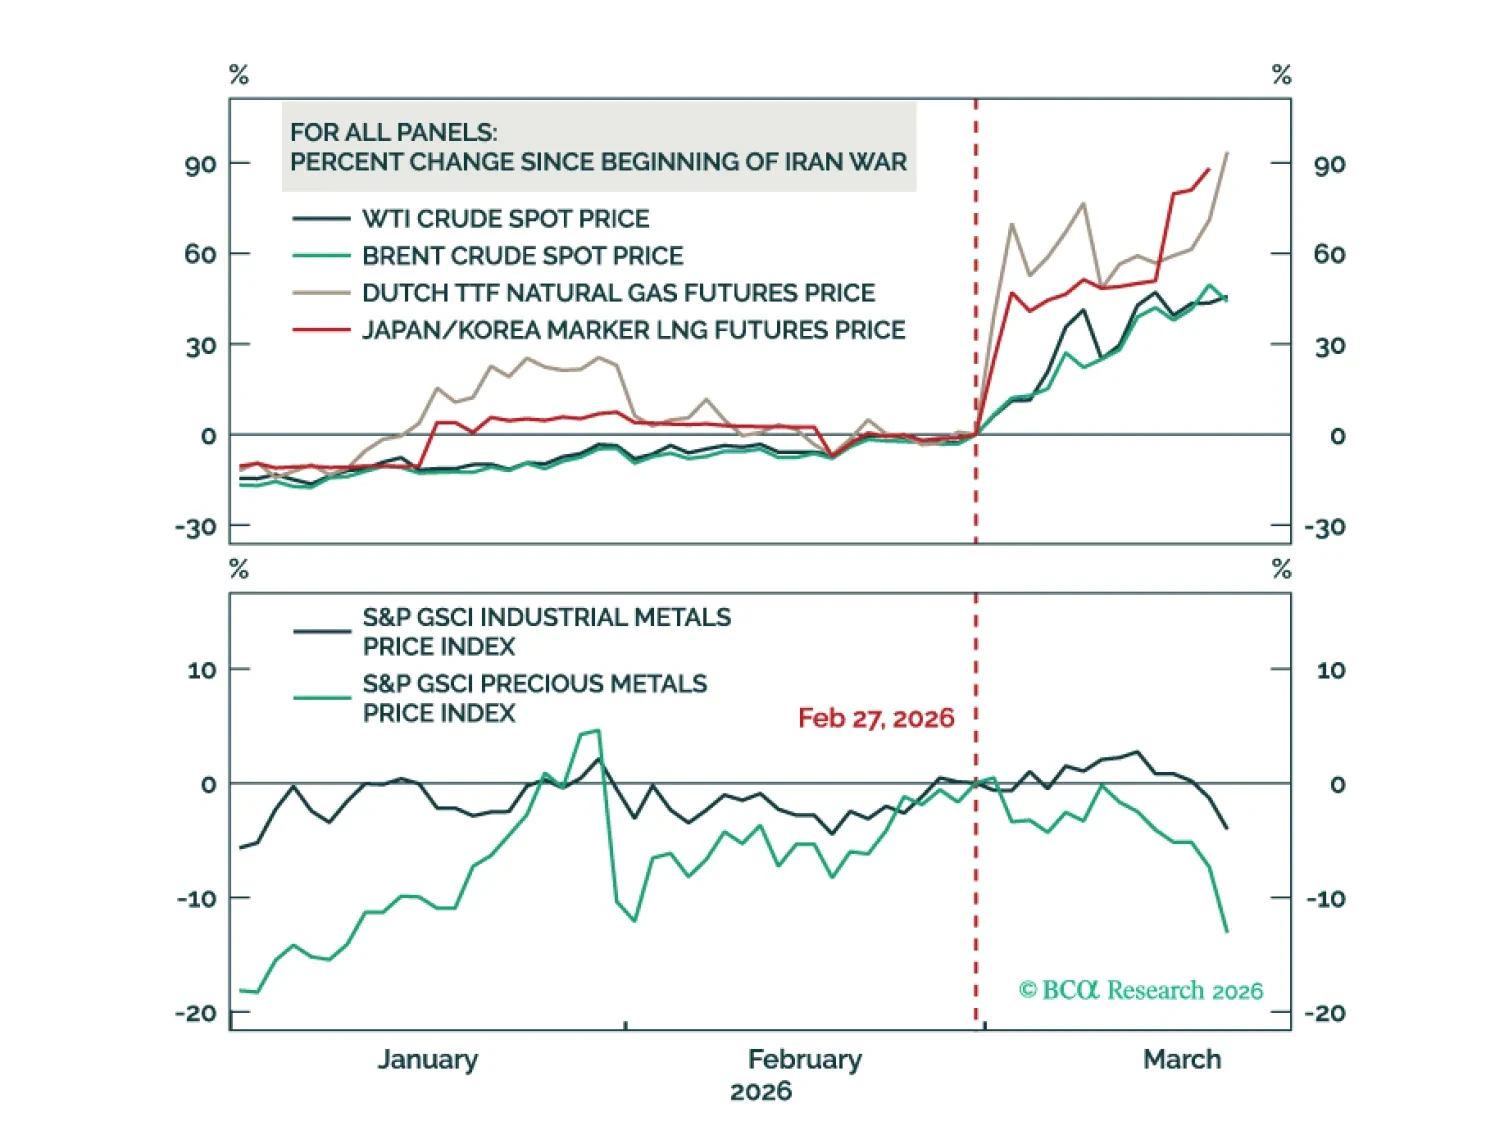
Higher oil prices threaten the global economy, warranting an underweight stance on equities. Over the long haul, industrial metals will fare better than crude.
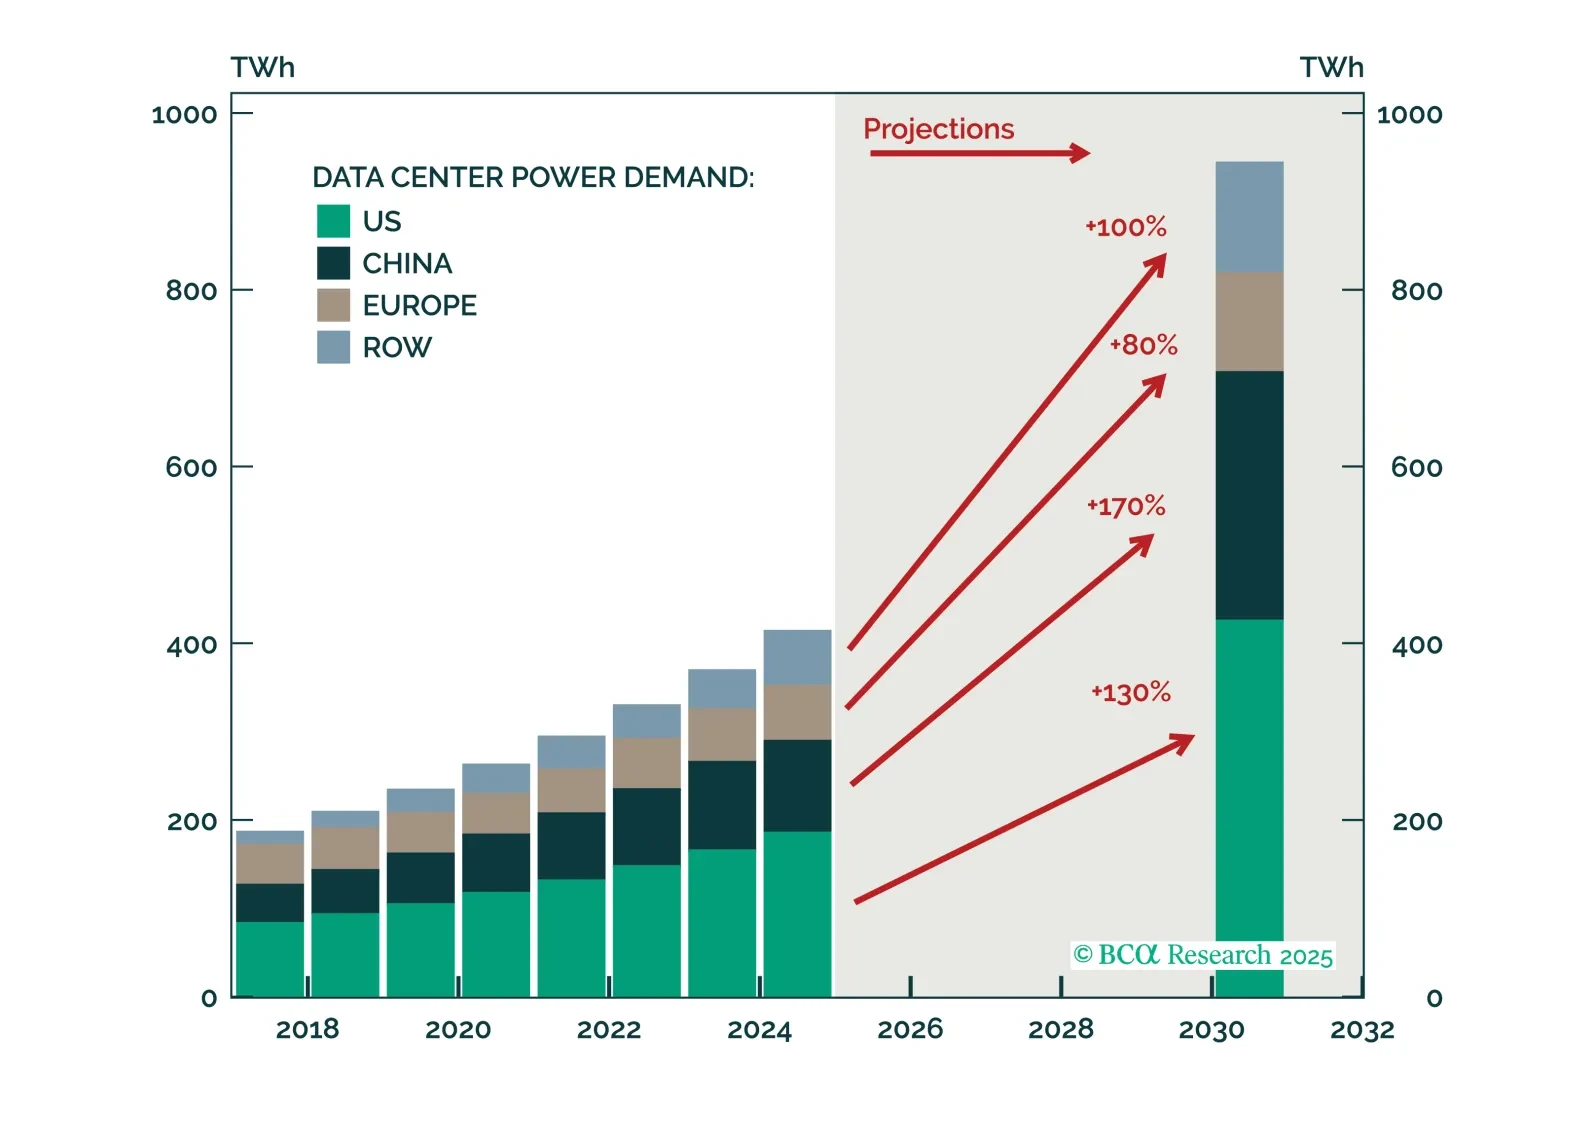
Renewables’ role in power-hungry data centers is overstated. Natural gas will fill clean electricity’s data center supply shortfall, particularly in the US and Europe.