Europe
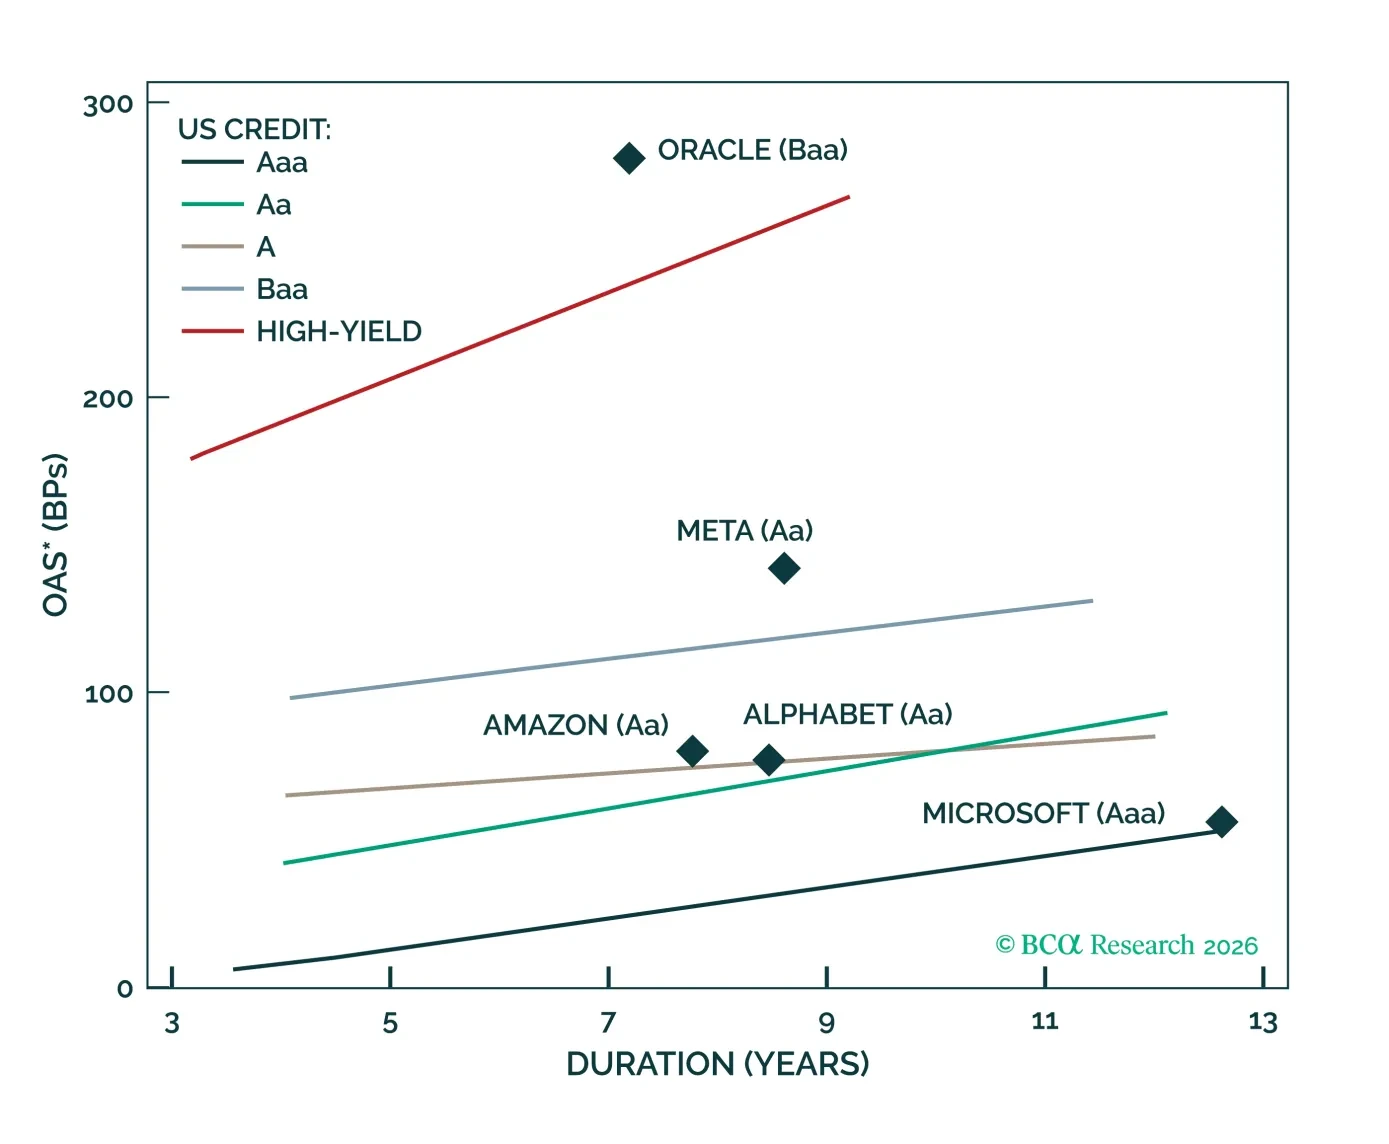
The hyperscaler repricing, European growth worries and stress in the lowest-rated junk bonds each tell a different story. We assess what drives spreads in each market and what it means for our corporate credit allocation.
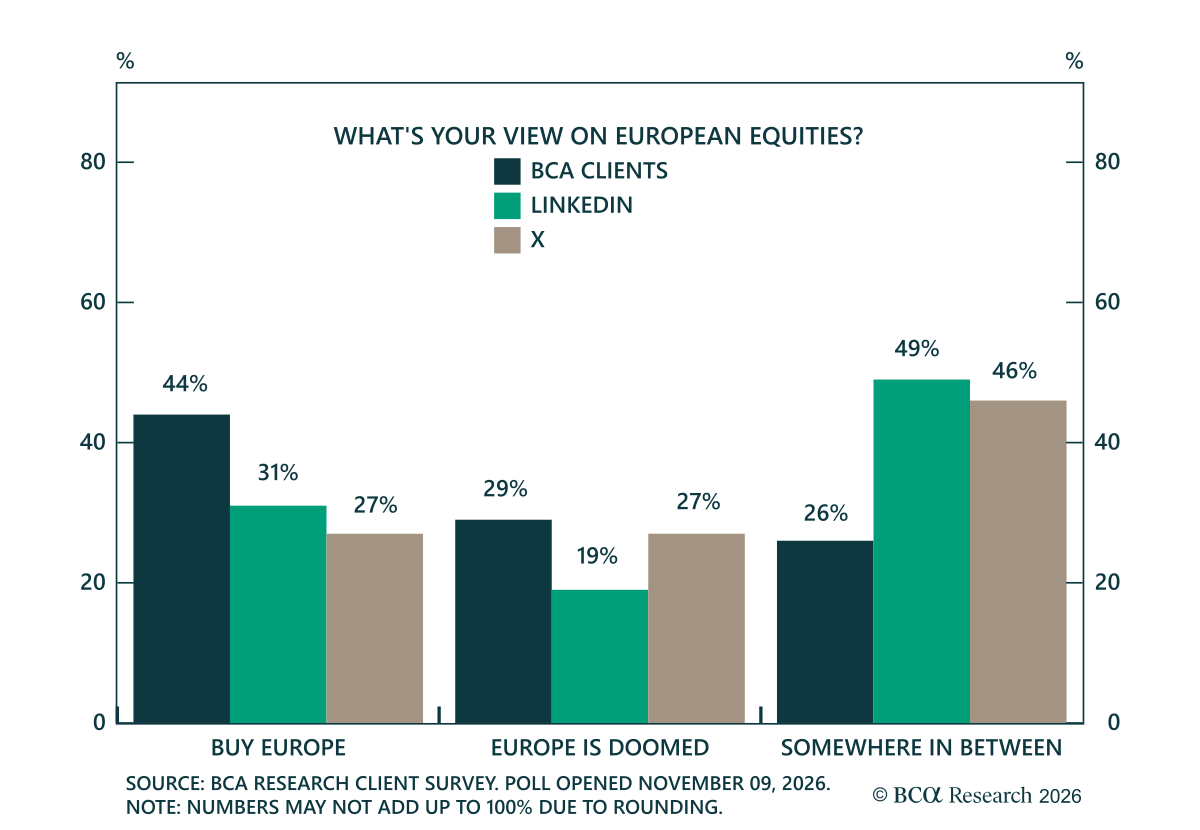
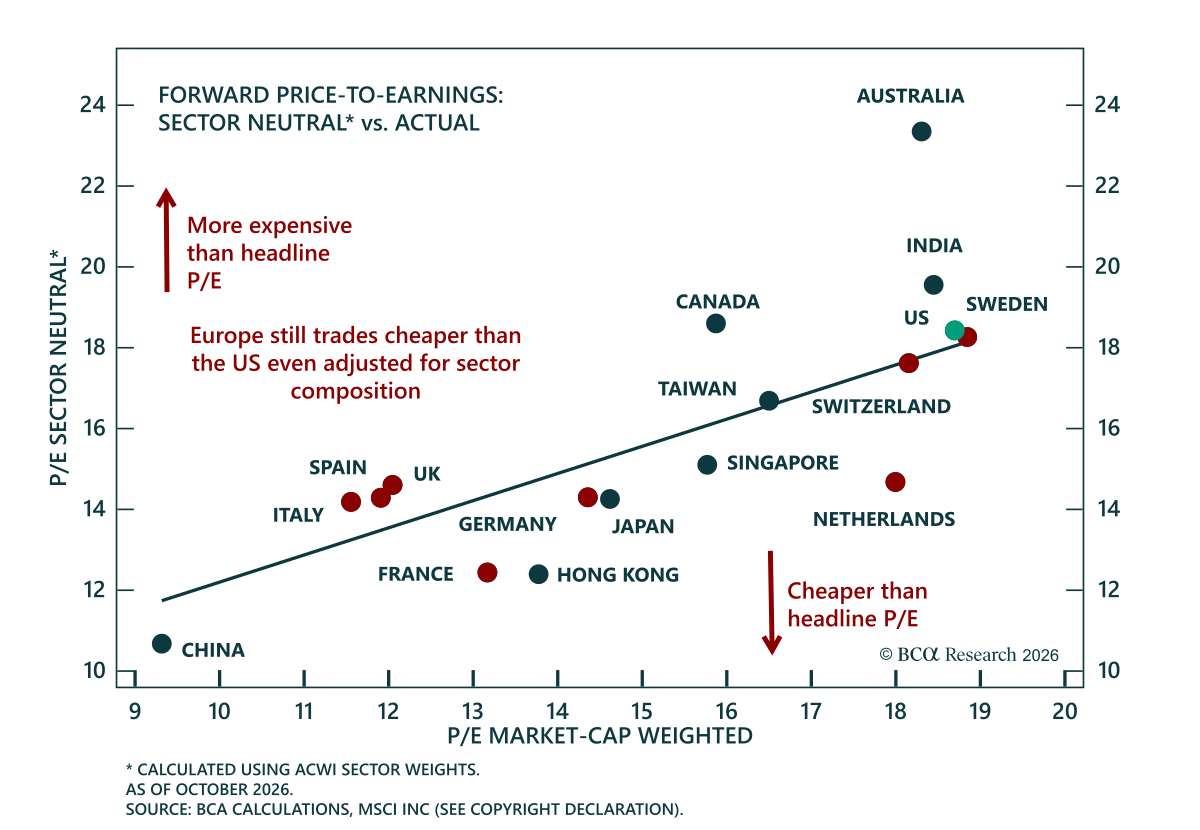
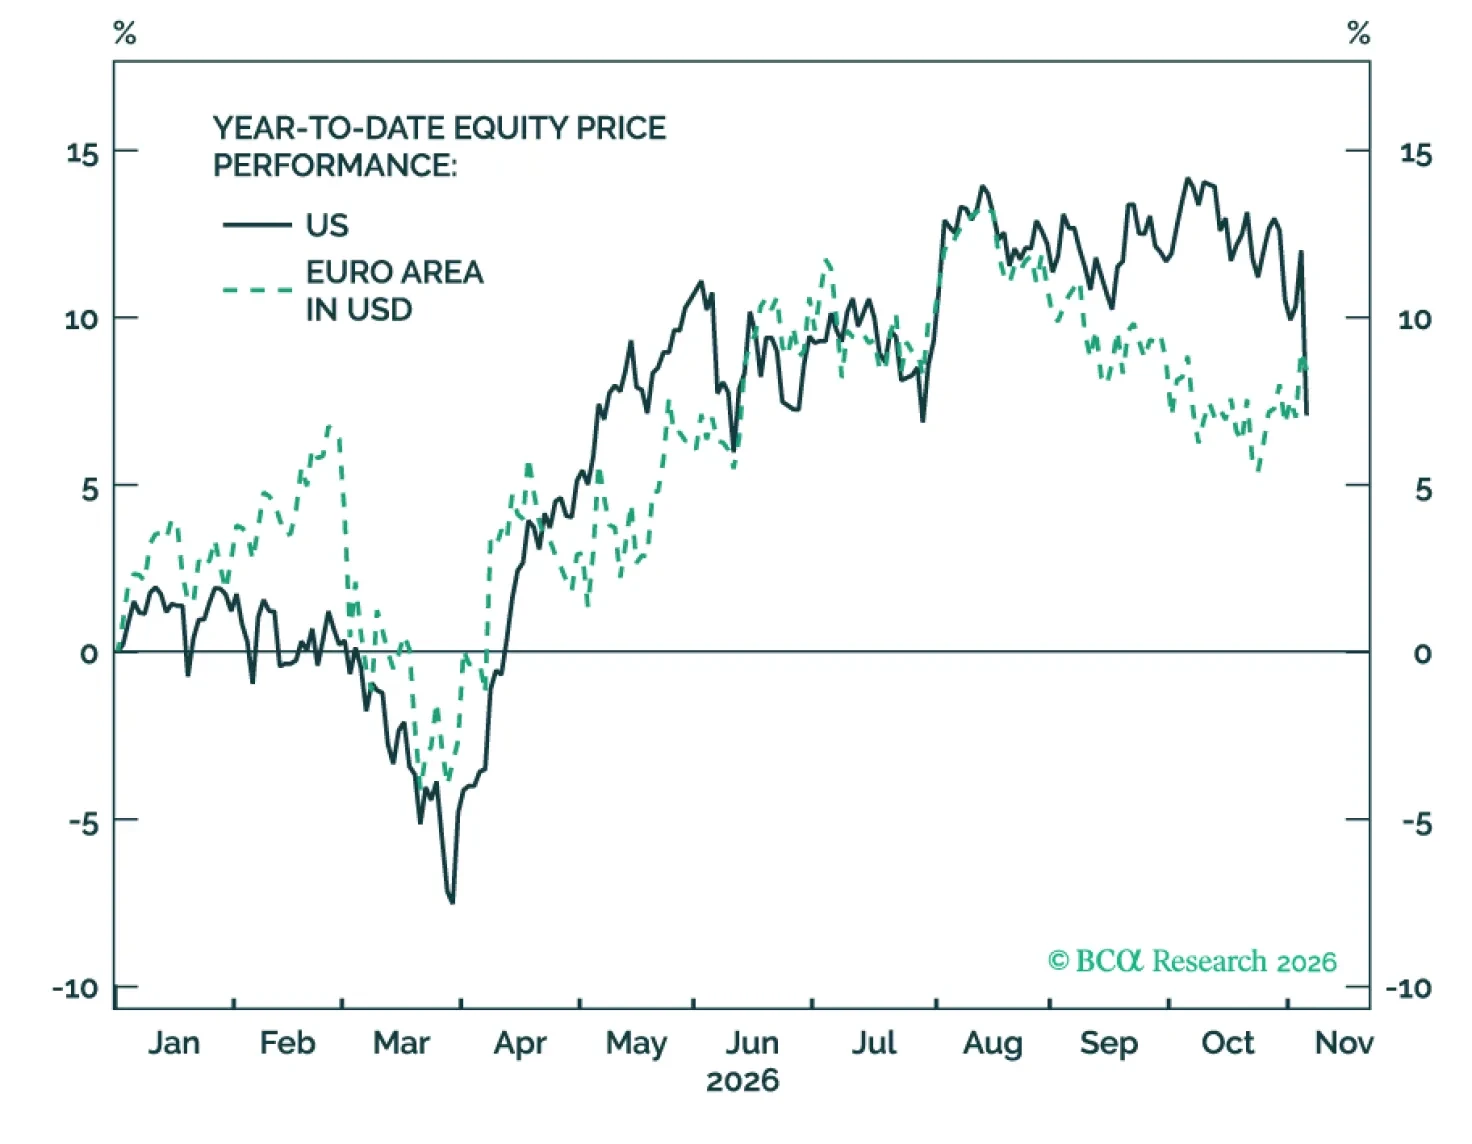
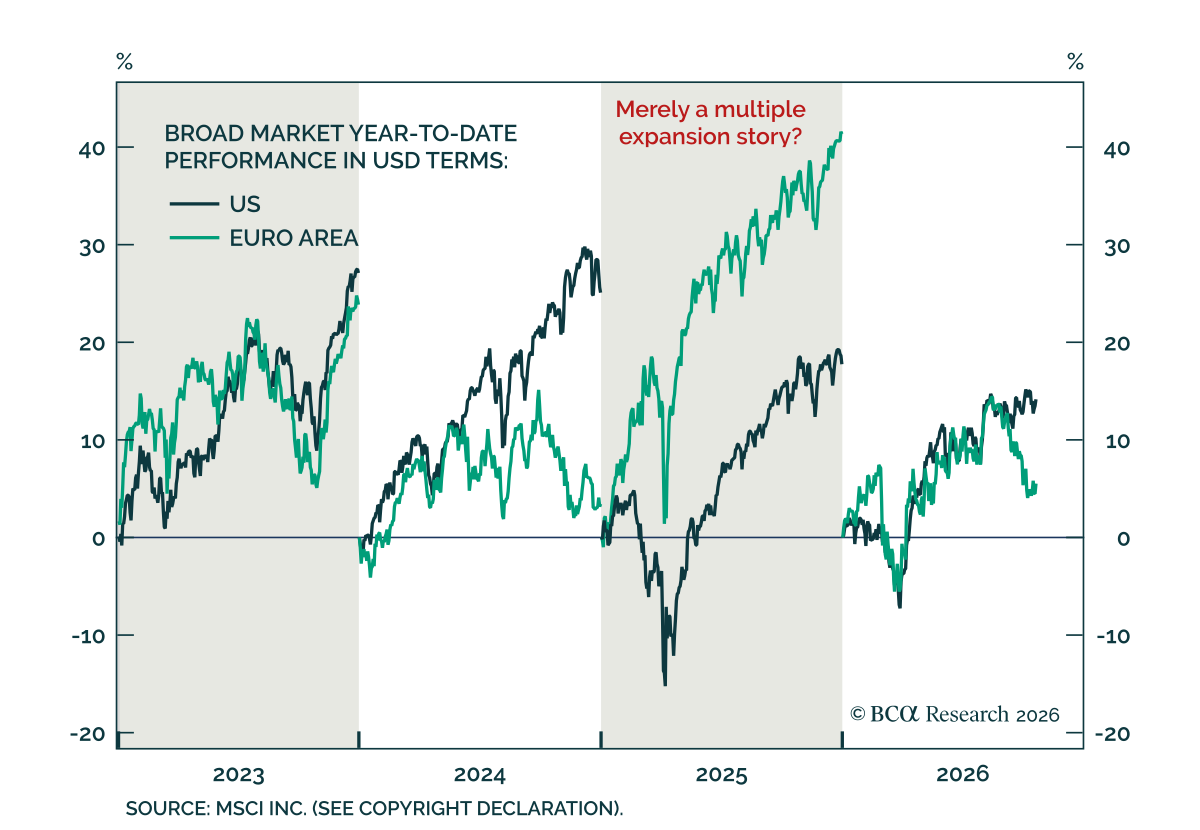
Europe was shunned while AI could do no wrong. That trade is looking tired. Falling energy prices and cracks in the AI boom favor rotating out of US equities and into cheaper European stocks. Favor defensives: Europe can win the relative race even if both markets fall.
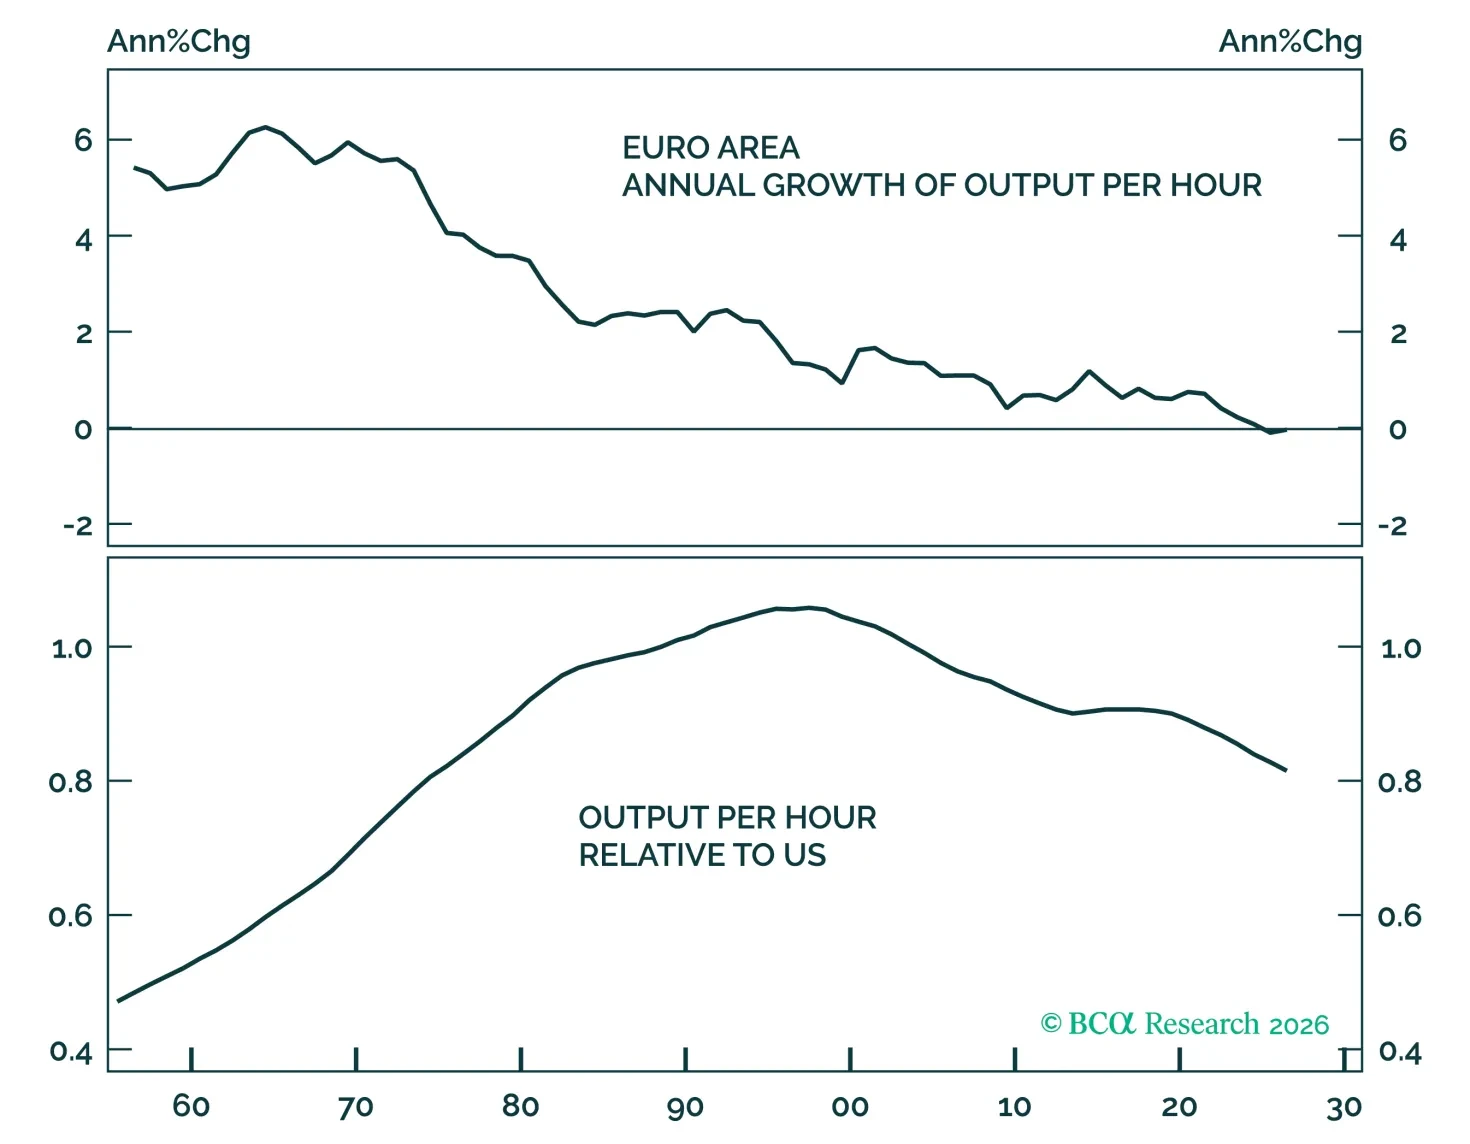
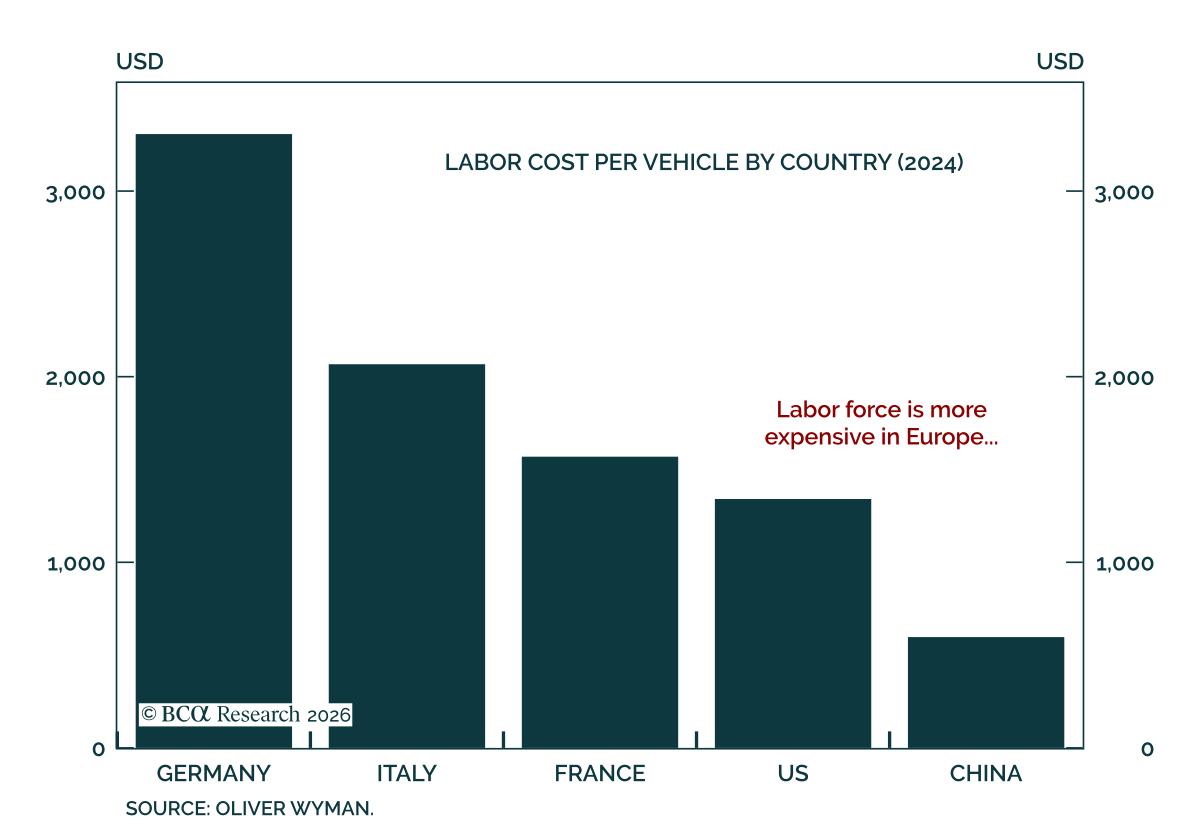
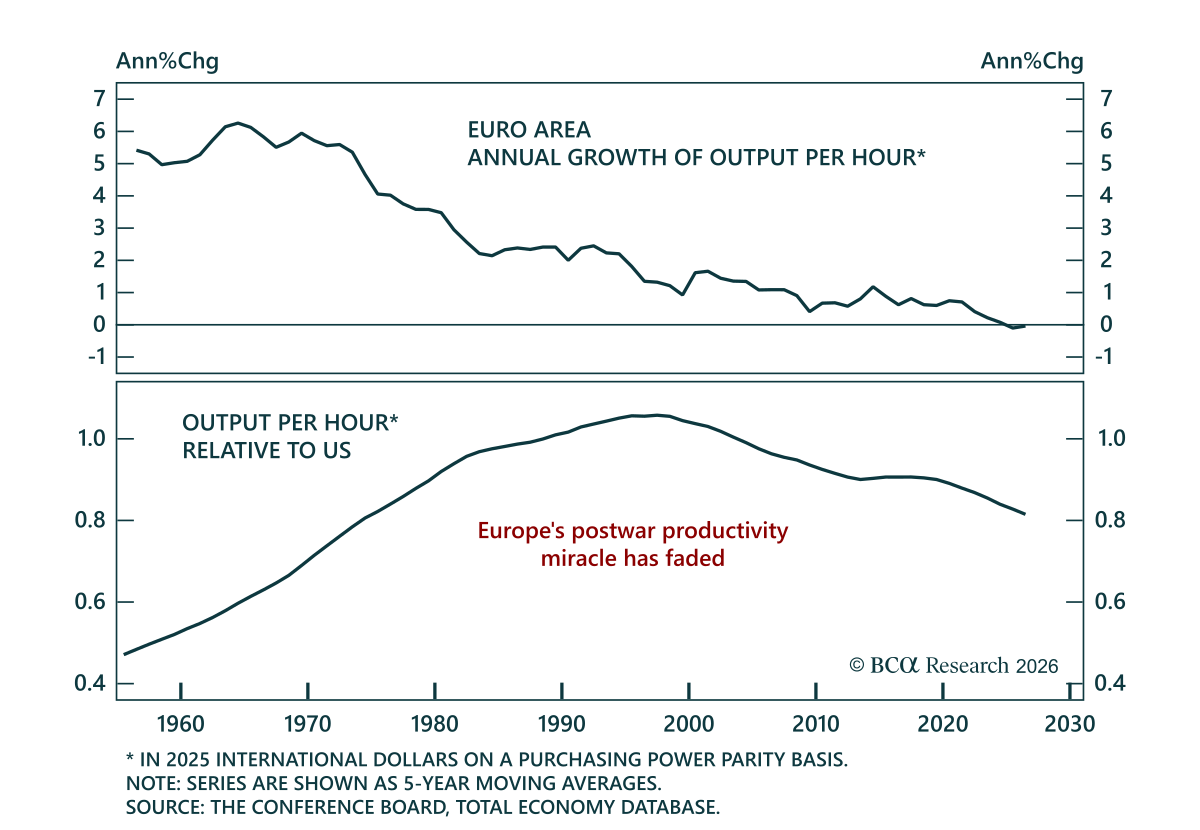
Europe faces deep structural problems. Dismantling large parts of the welfare state might be necessary to rectify these problems, which is unlikely to happen before there is a major crisis. Until then, investors should “sell Europe” on any rallies.
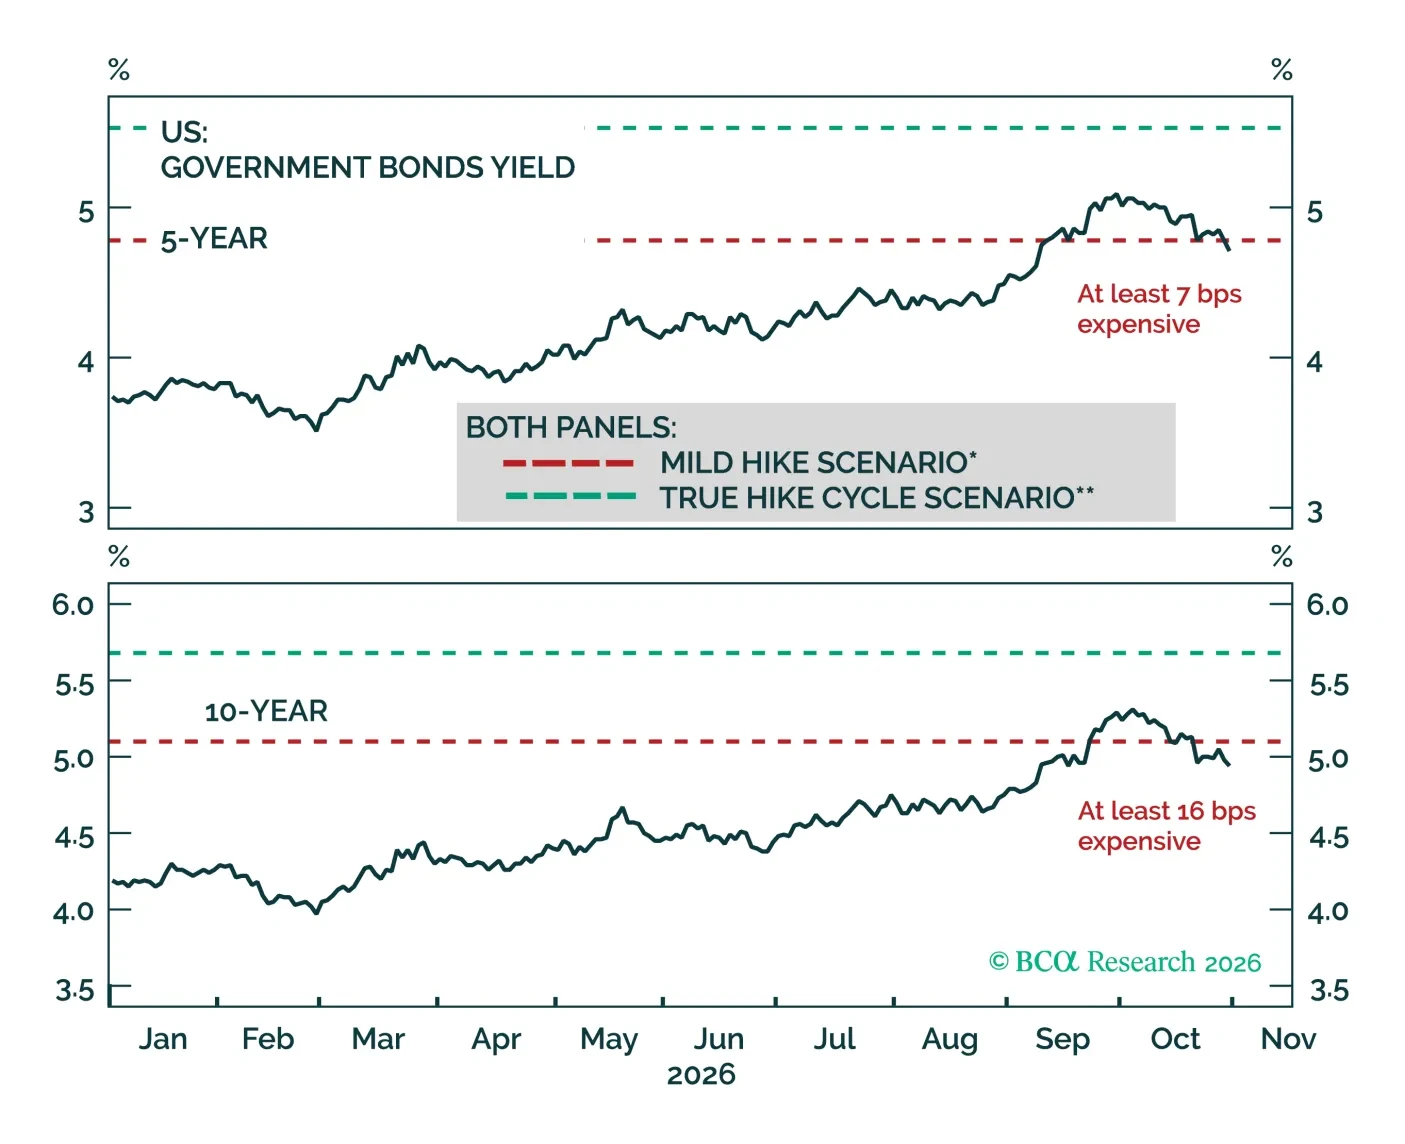
US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.