Latest from BCA Research
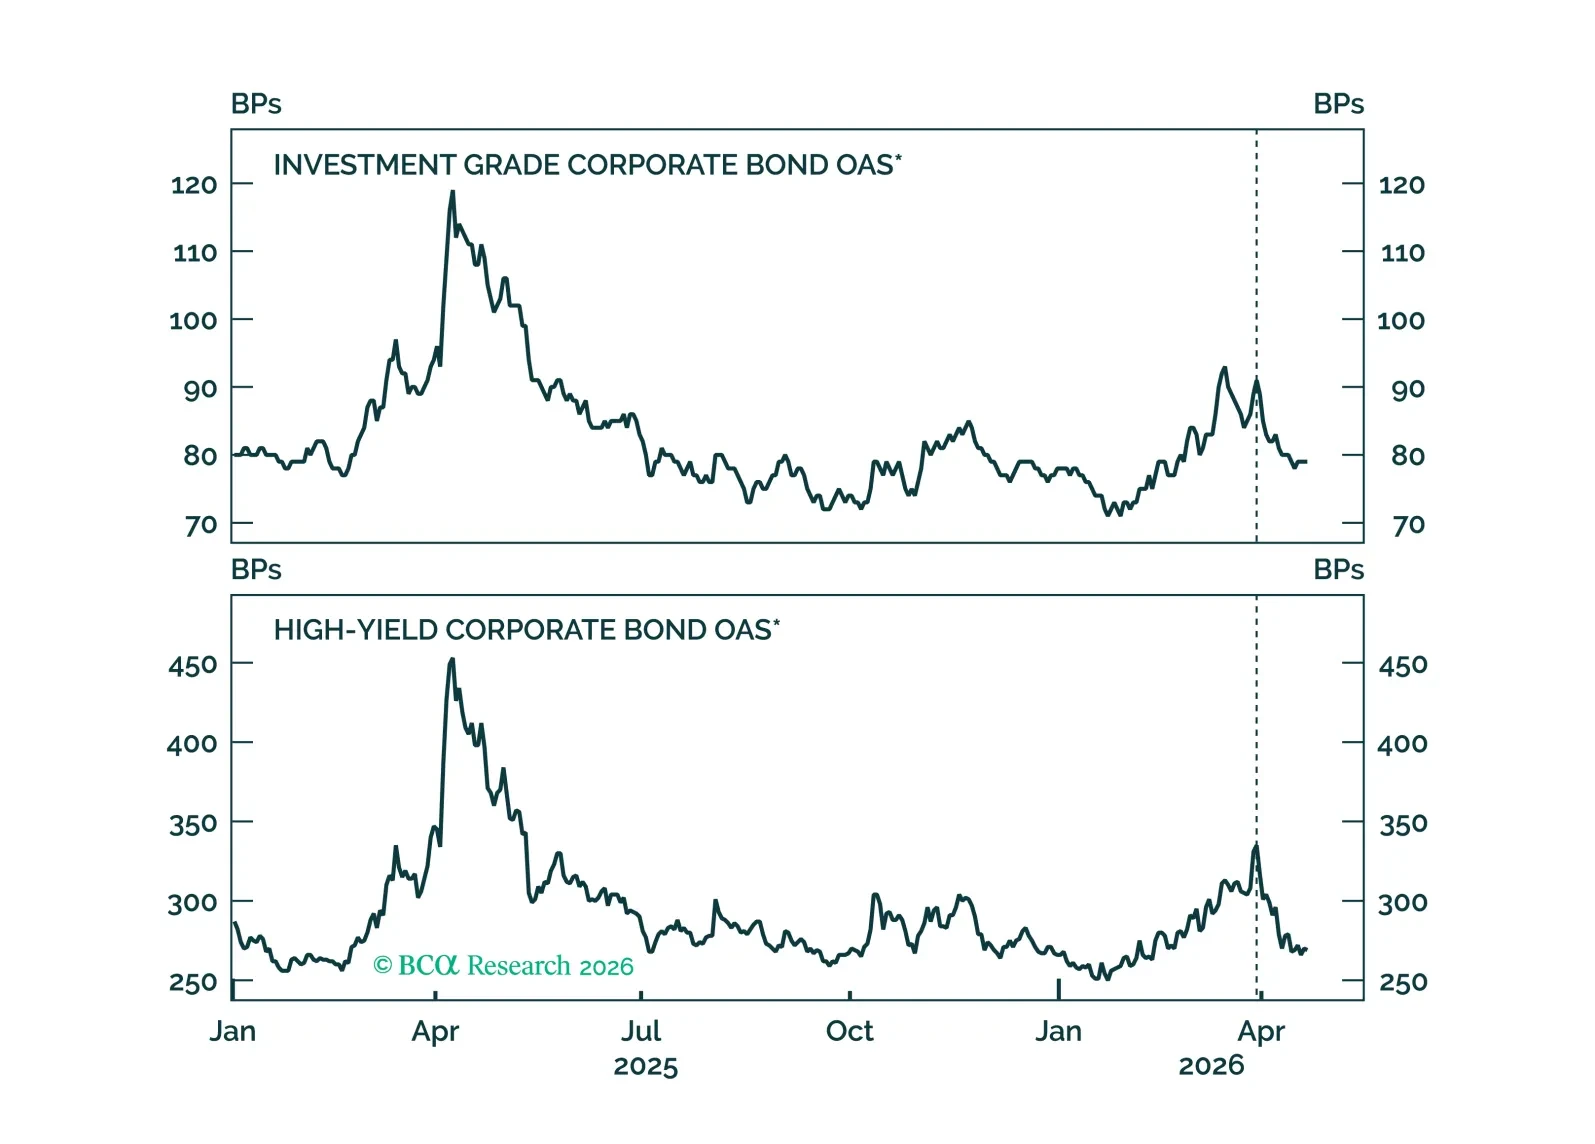
We recommend increasing exposure to spread product as the US economy transitions back into a low rate vol regime.
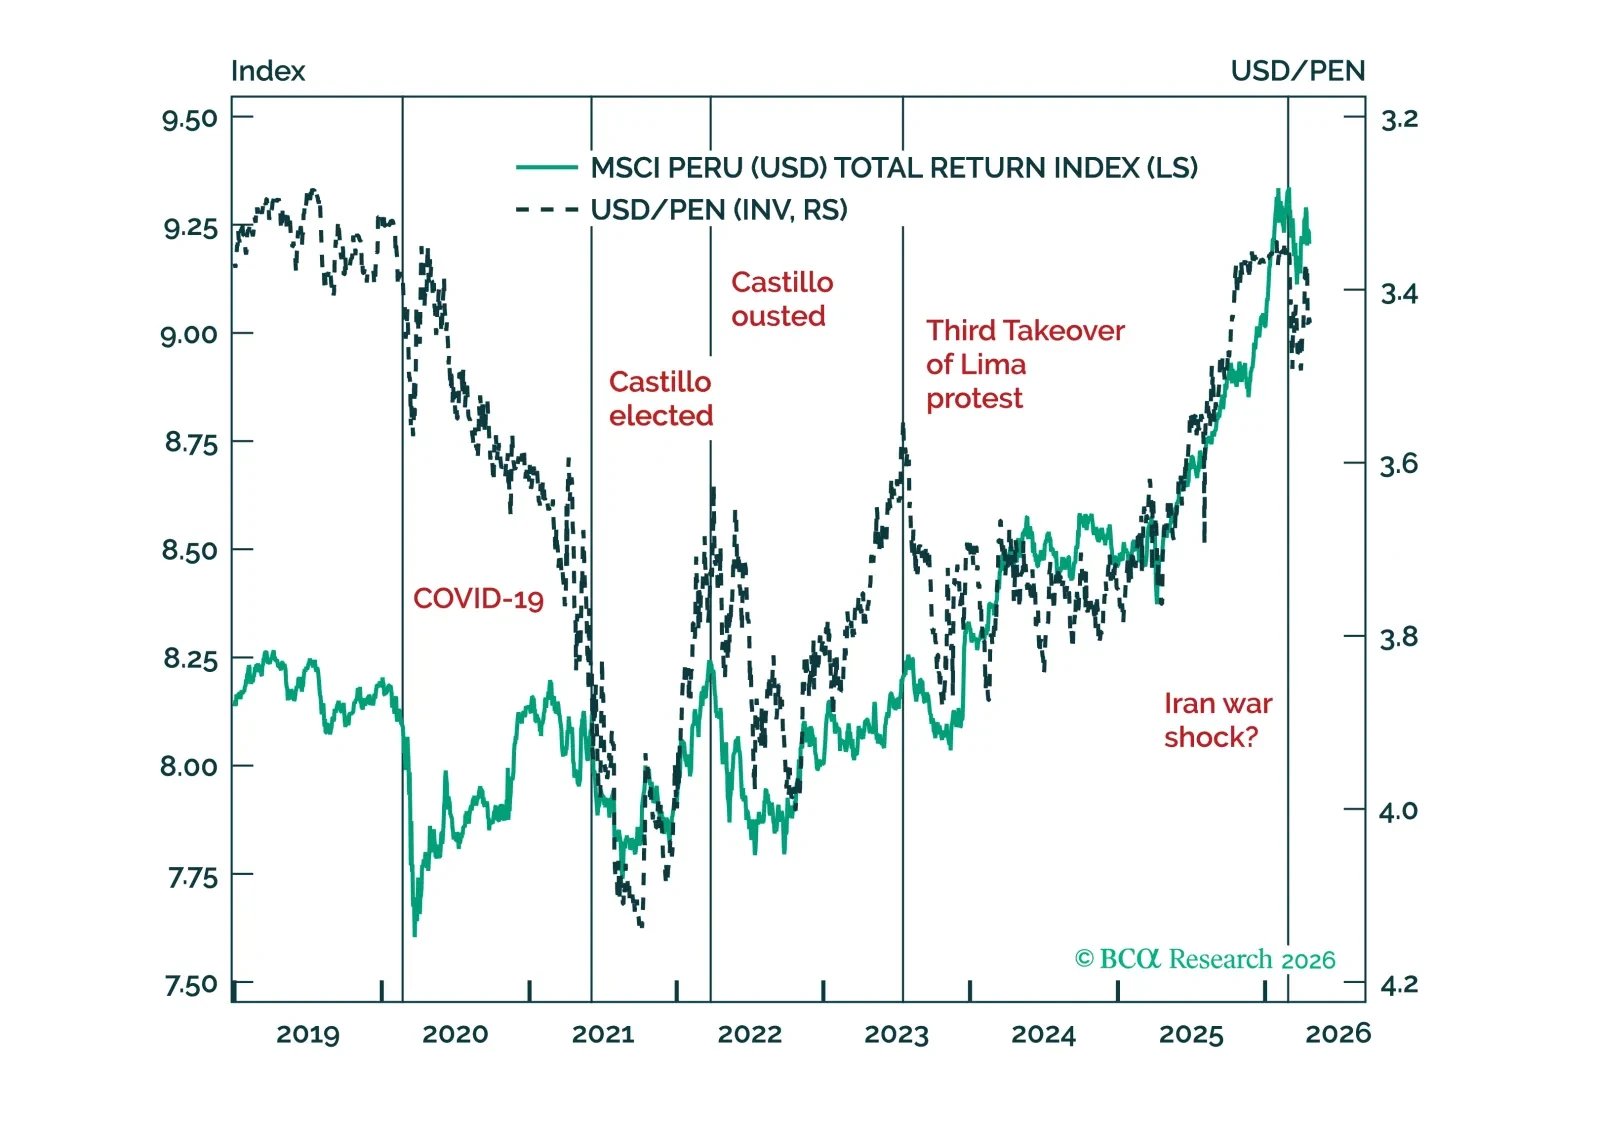
Peru is well established to elect a pro-market government in the June 7 run-off, with institutional constraints limiting left-tail policy risks. We will go long Peruvian assets when Hormuz volatility subsides.
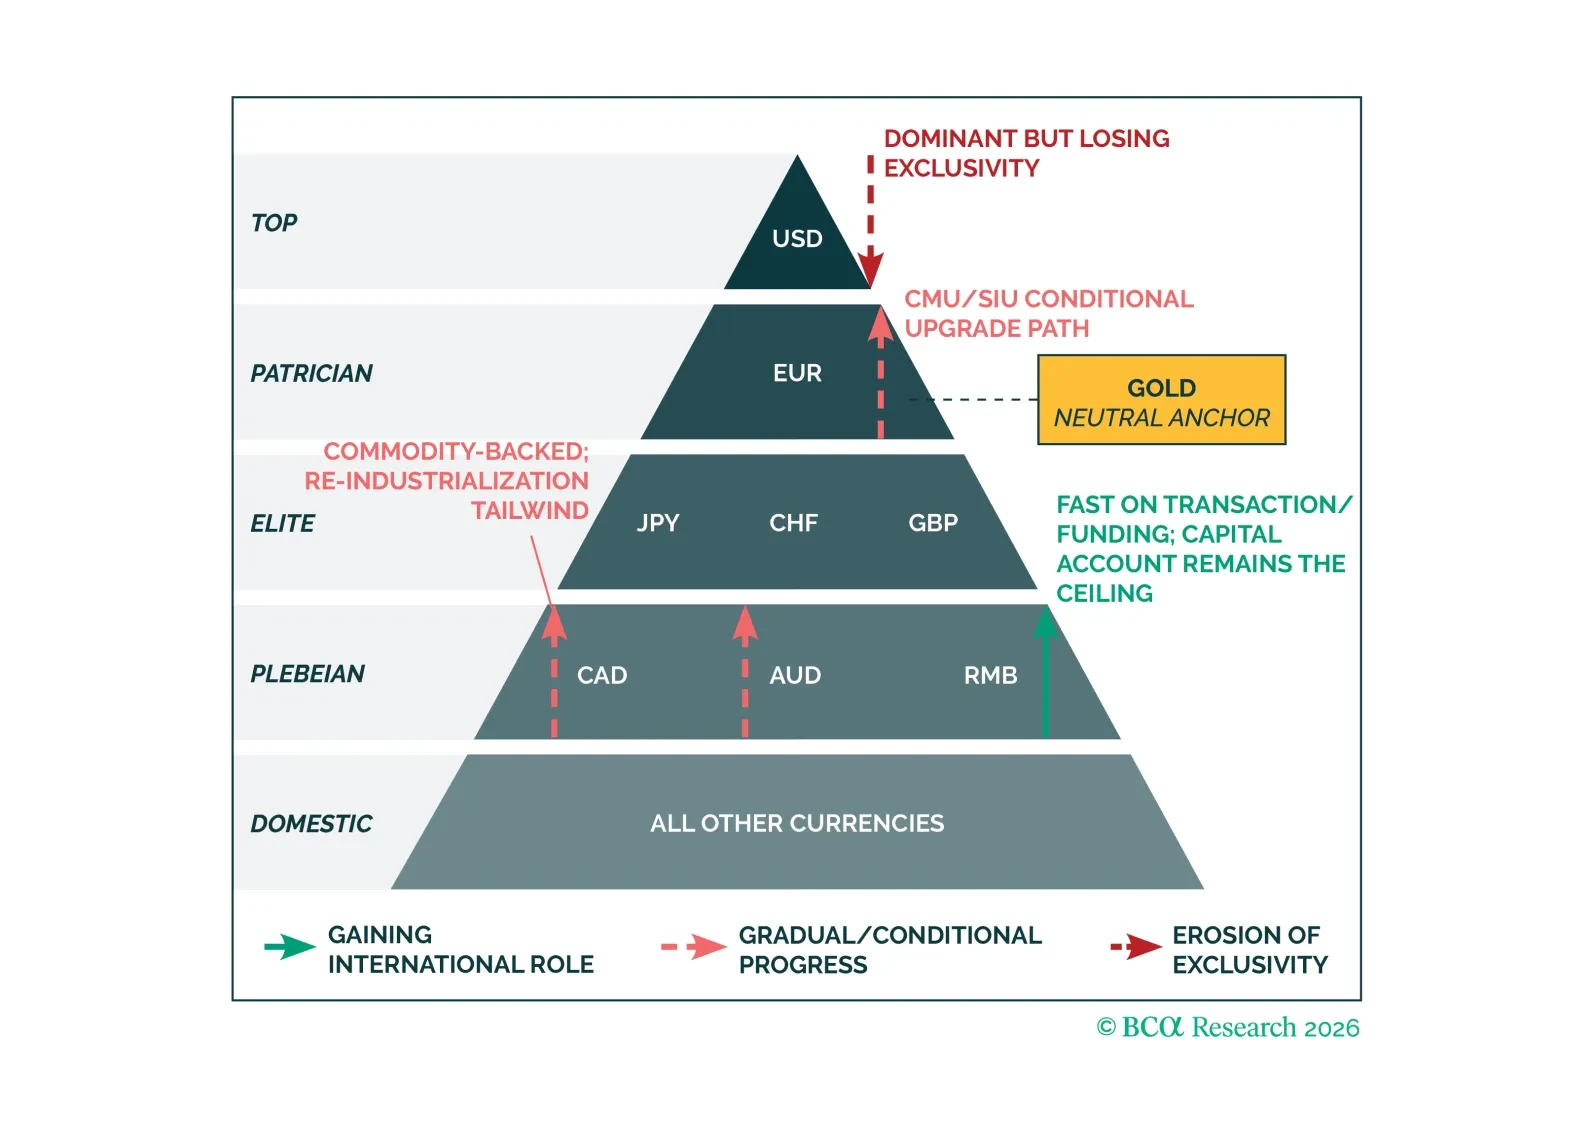
The debate over “what replaces the dollar” is misguided. The real shift is toward a multi-anchor system where reserve functions fragment. That changes everything from term premia to cross-asset correlations. The implication: portfolios built for the old regime are already behind the curve.
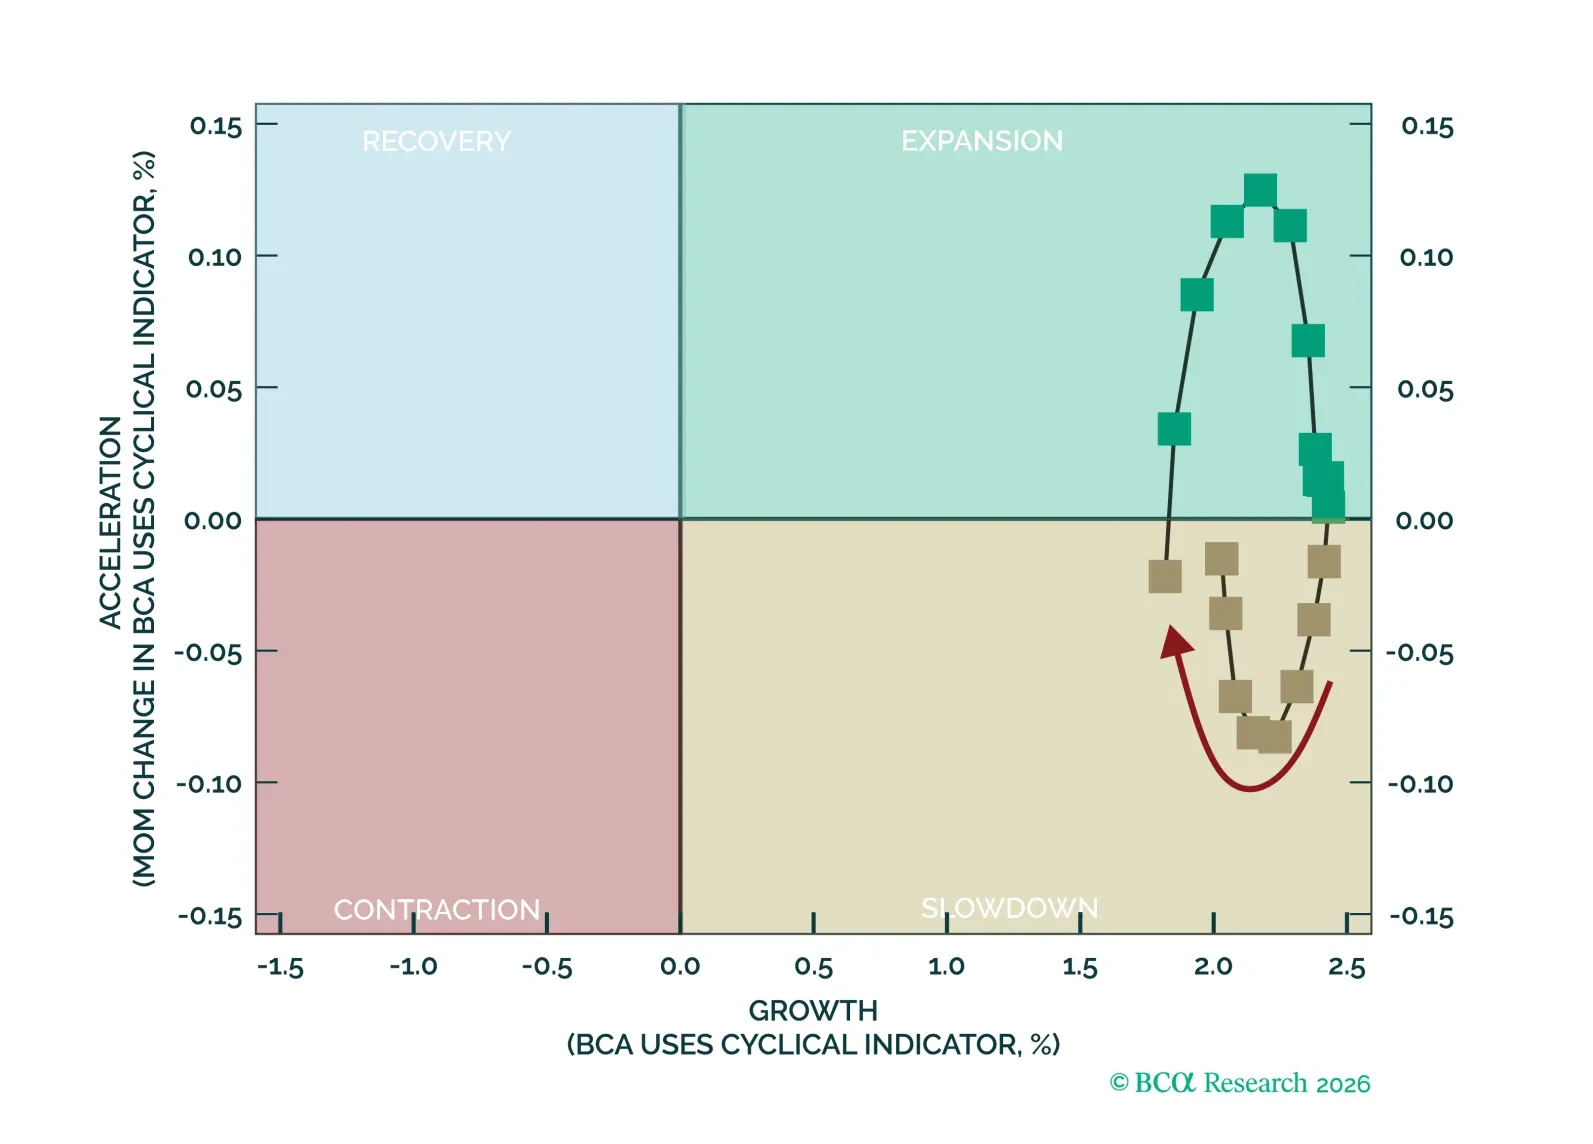
The S&P 500 rally is likely more than just risk-relief. Market internals reflect strengthening economic growth and higher inflation, with support coming from robust earnings. Tight financial conditions have compressed valuations, particularly within the Tech sector. We are initiating a long Software trade ahead of earnings season, given that multiples have declined and earnings growth is strong.
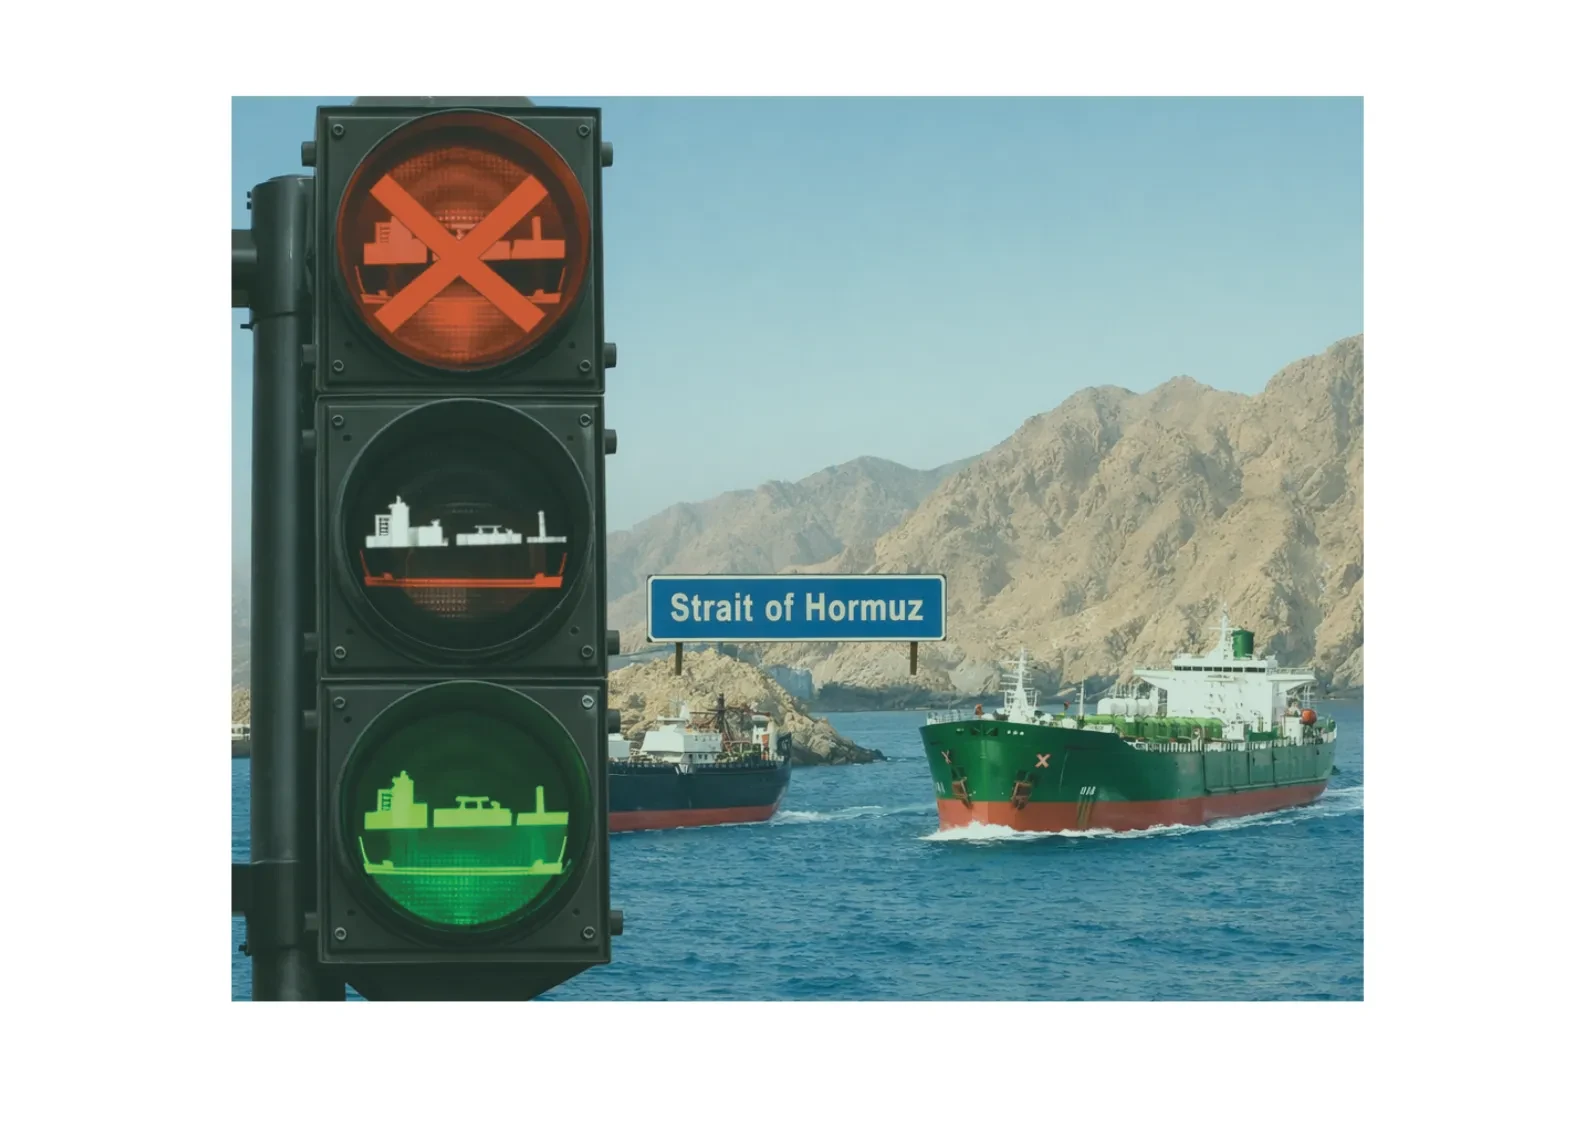
Red Light. Green Light. So much for the “all clear” in the Hormuz saga.
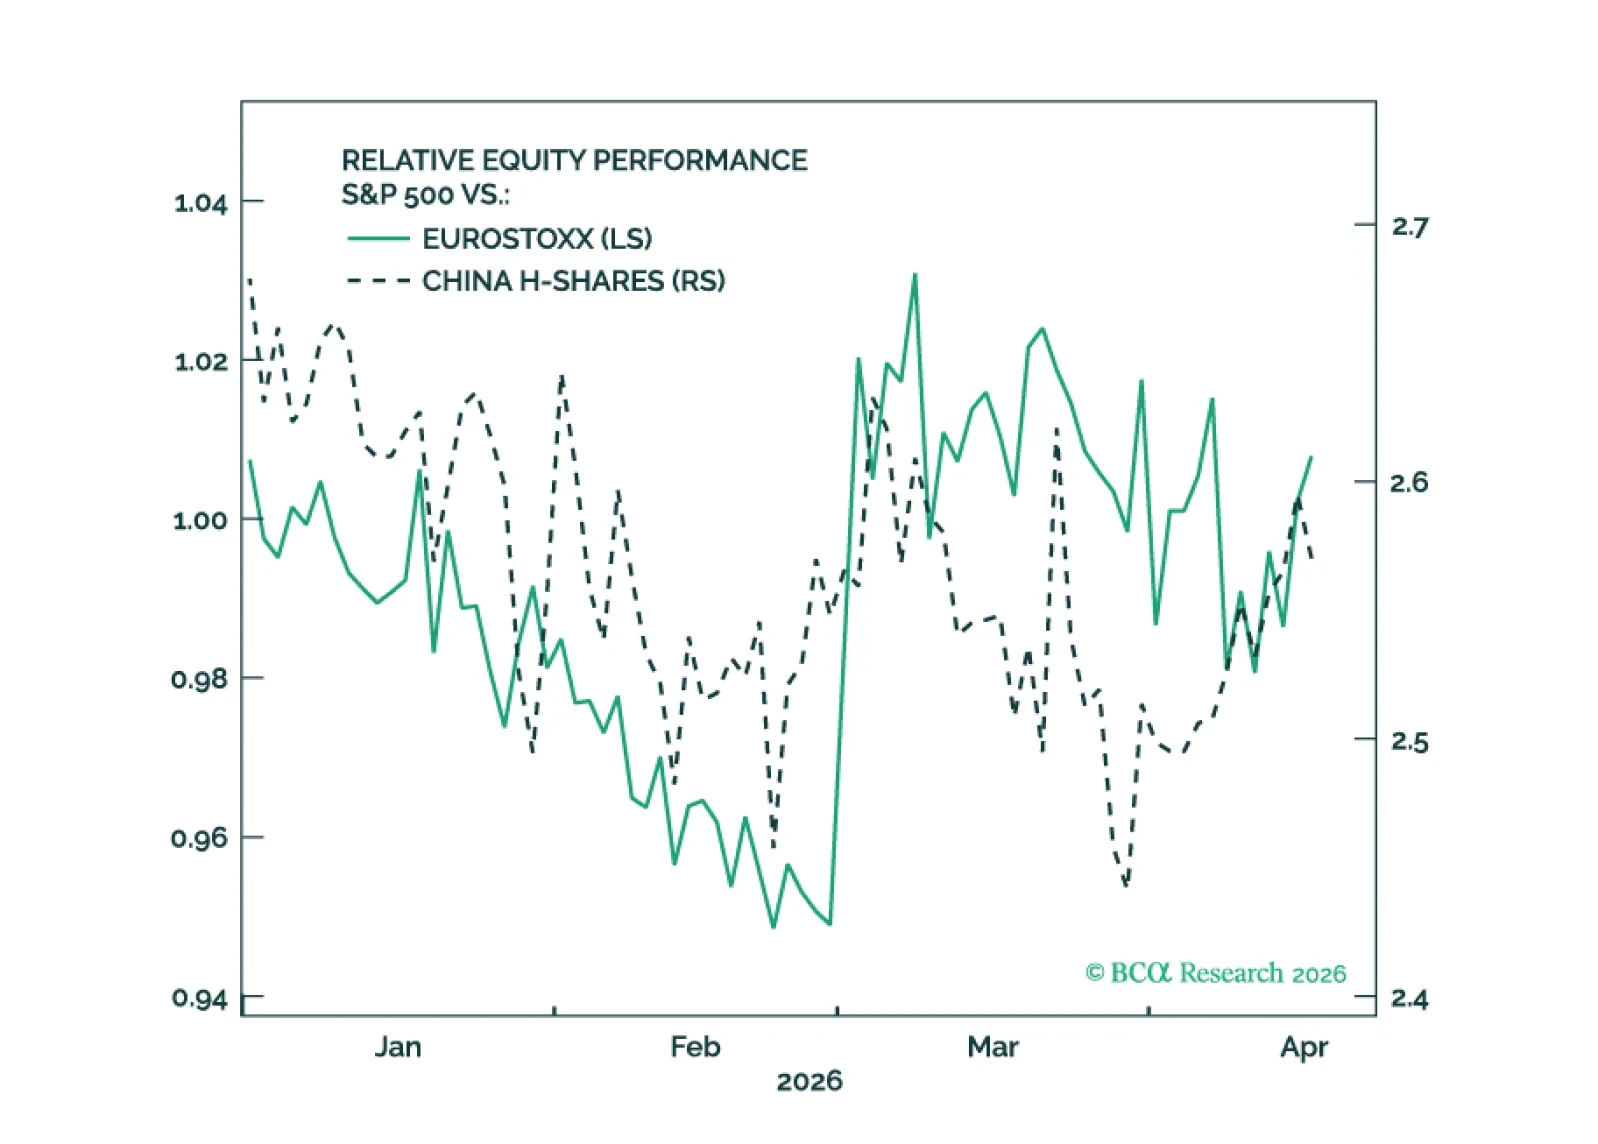
The Iran war is deescalating further — against our expectations — setting up an aggressive return to the risk-on rally.
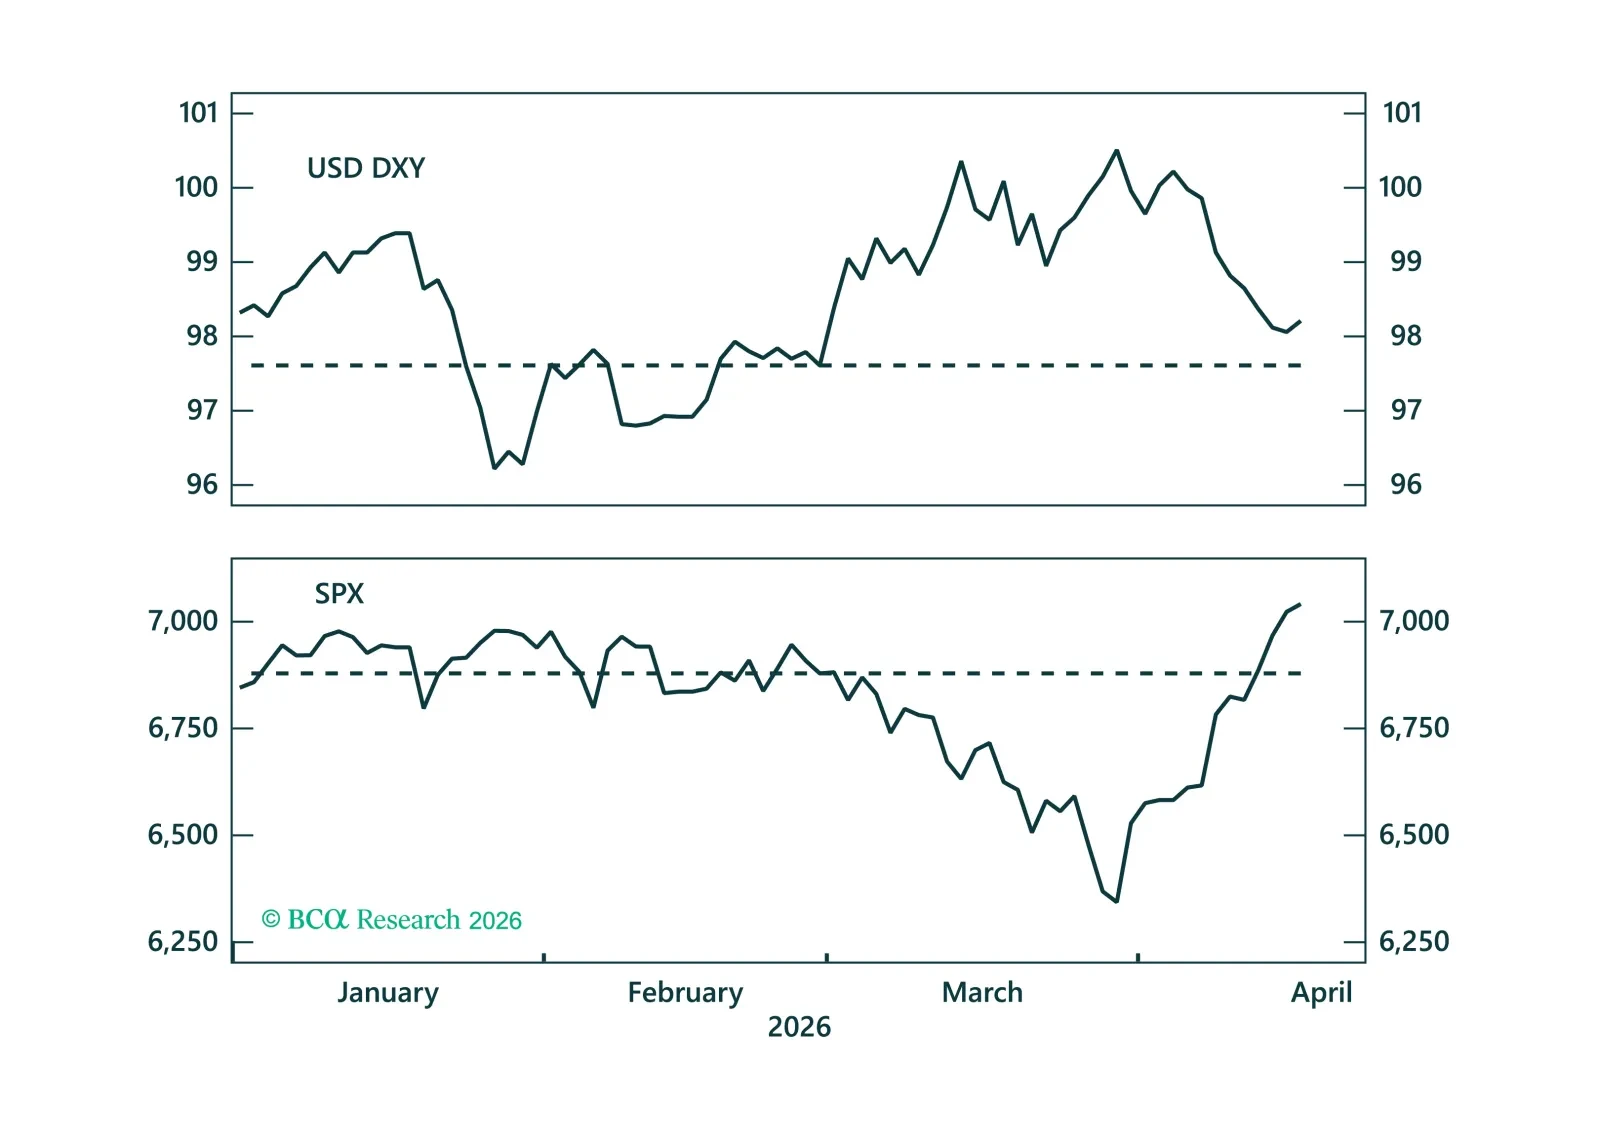
The dollar’s pullback masks a quiet improvement in its cyclical backdrop, with growth, monetary policy, and flows turning in its favor. As markets fully price out geopolitical risk, the USD should decouple from oil and better reflect these gains, despite lingering structural headwinds.
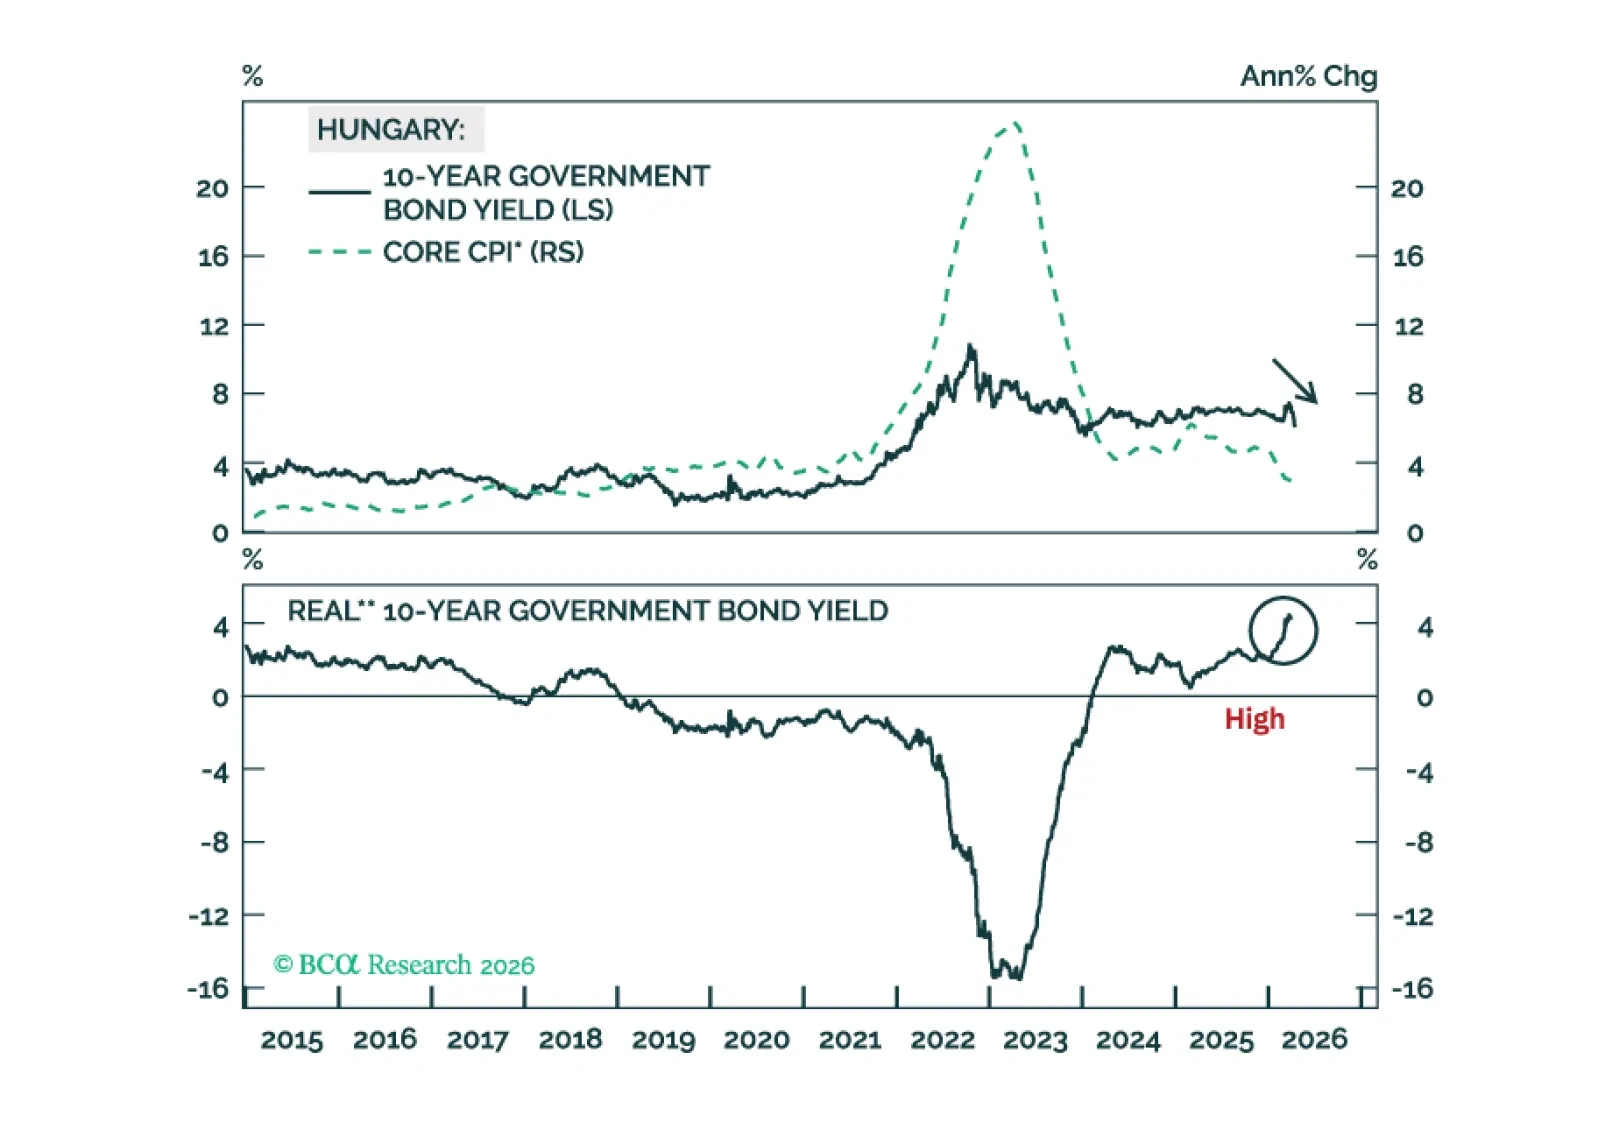
Hungary’s growth outlook has improved as the election of a new government will likely unlock significant EU funds for the country. Currency traders should go long the Hungarian forint / short US dollar.
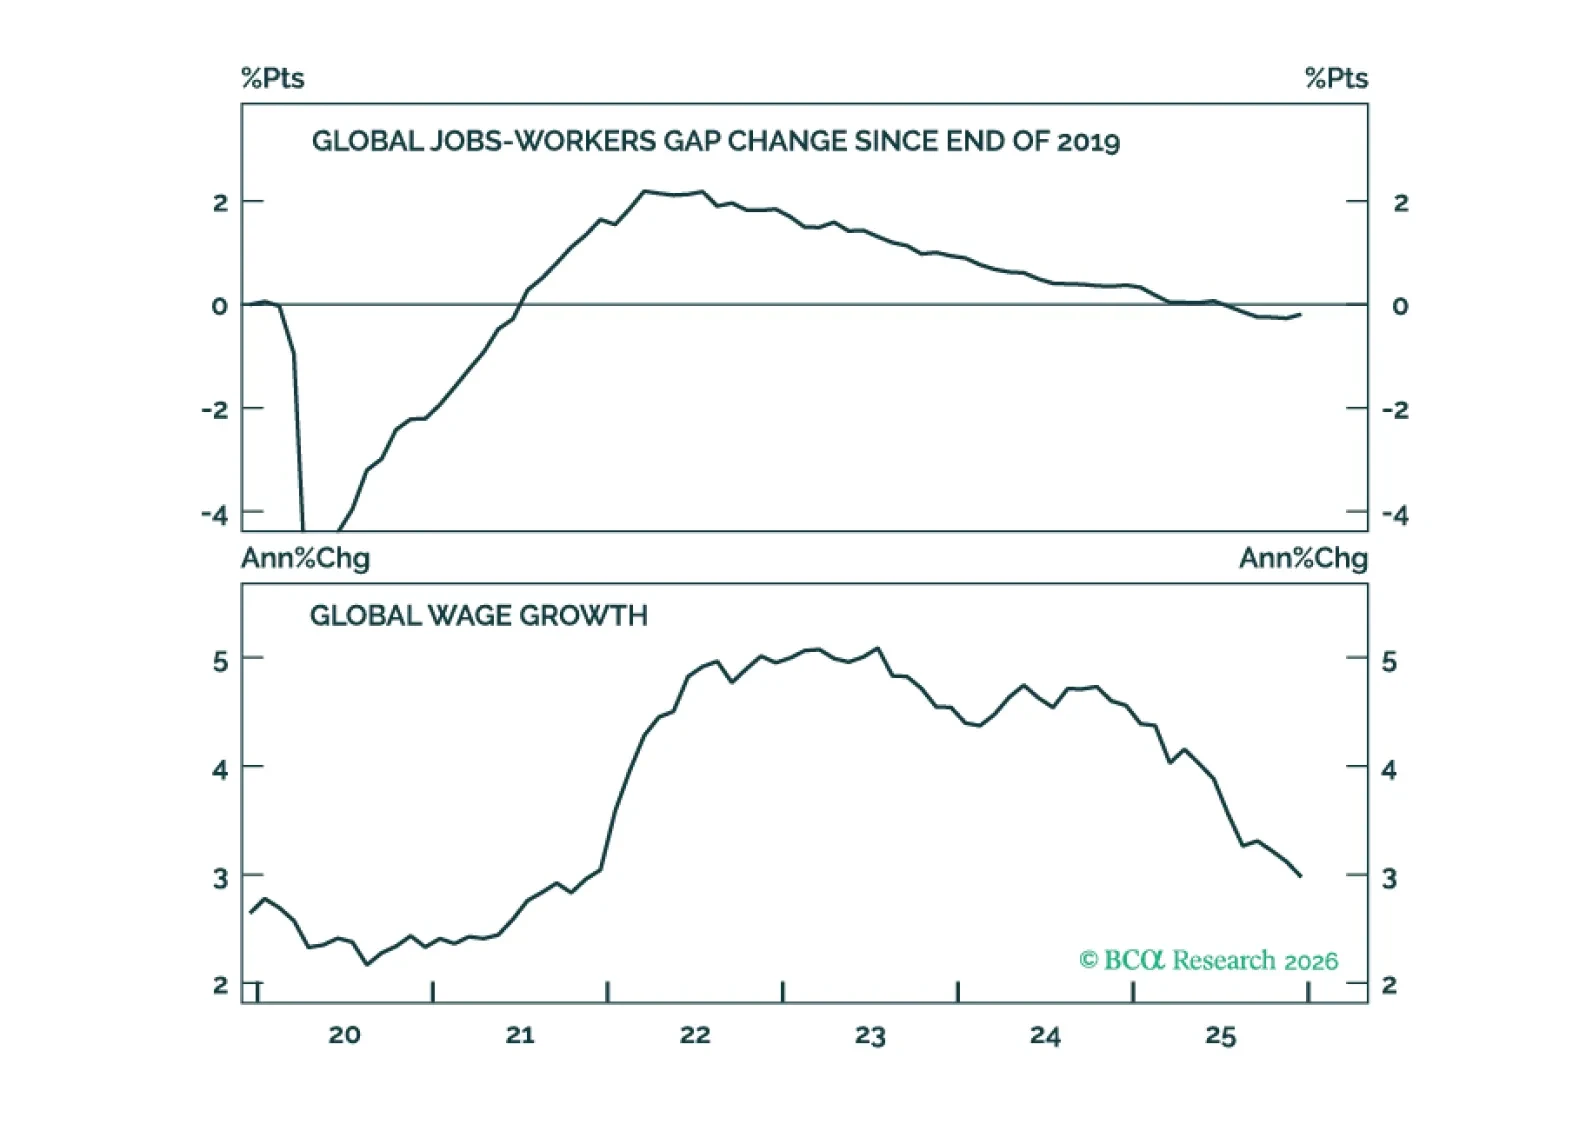
We do not expect the oil shock to have a lasting effect on inflation. Looking further out, a variety of structural forces will influence inflation, including fiscal policy, globalization, demographics, and AI.