Skip to main content

Essentials

Concise macro insight that cuts through daily noise, helping clients stay informed on what matters in markets, why it matters, and how to talk about it, without spending hours reading research.
Explore Essentials
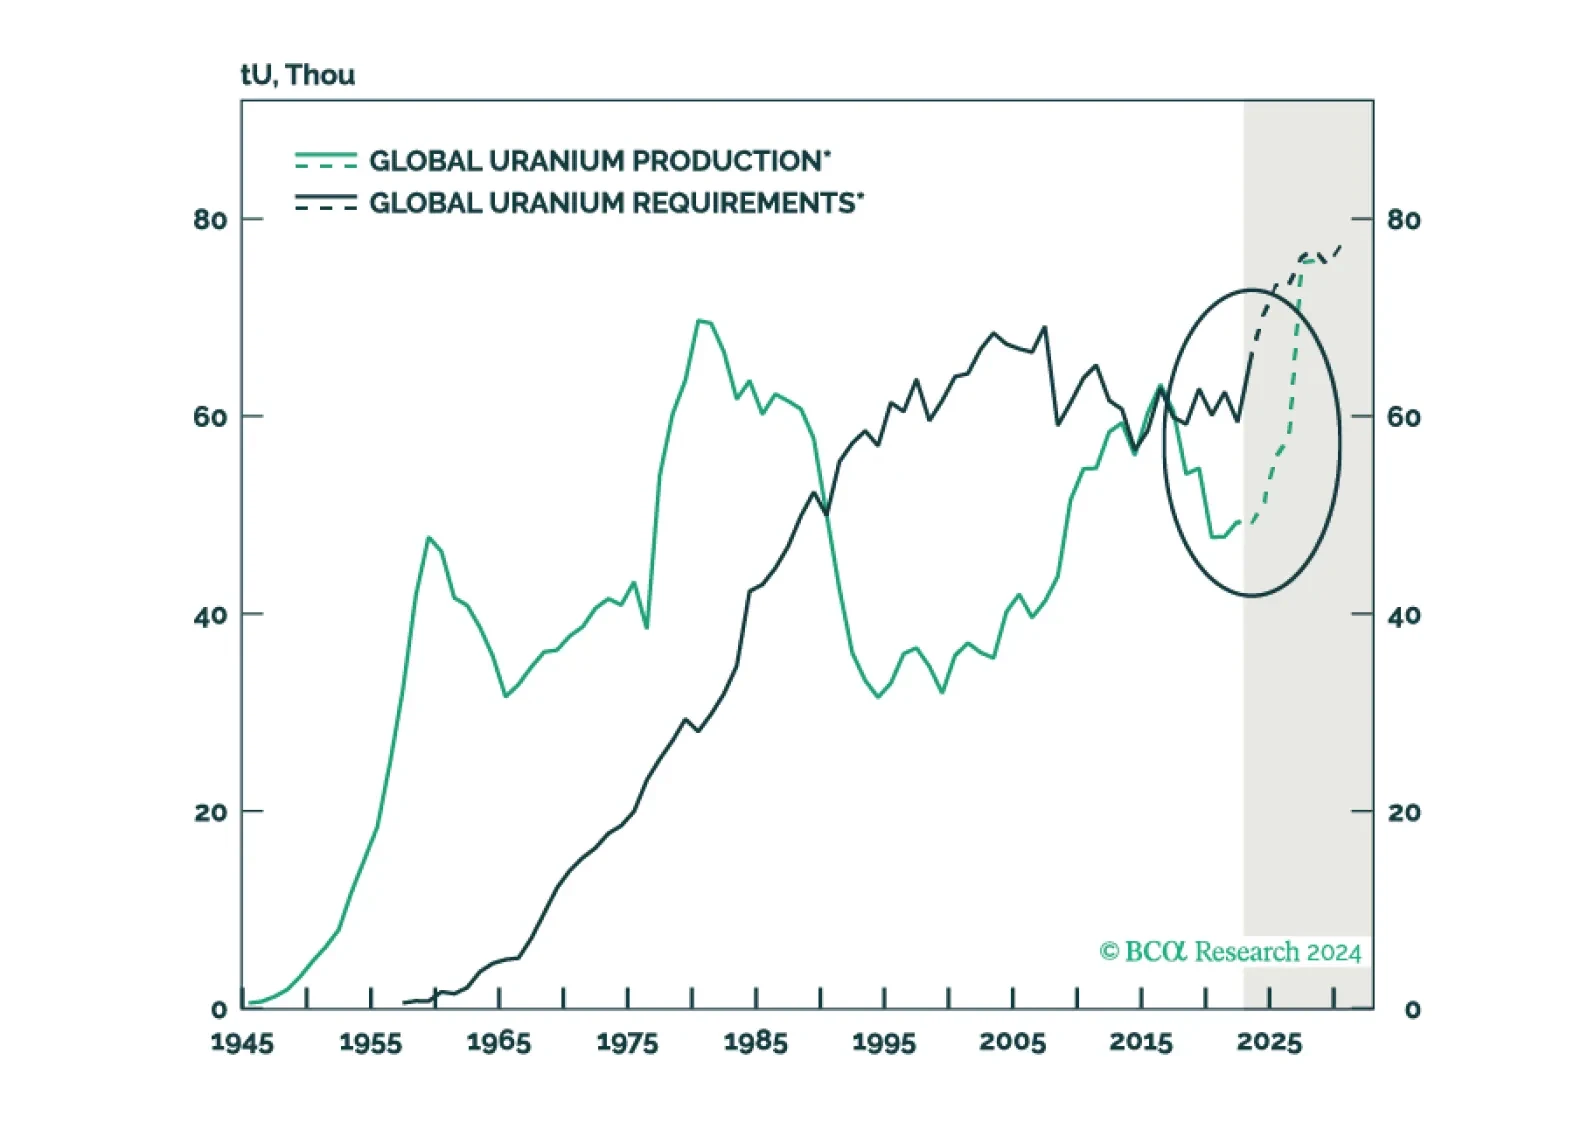
Bank Credit Analyst The uranium market is at a crossroads of economics and geopolitics. This report presents an overview of supply and demand factors that have led to the formation of the present supply deficit.
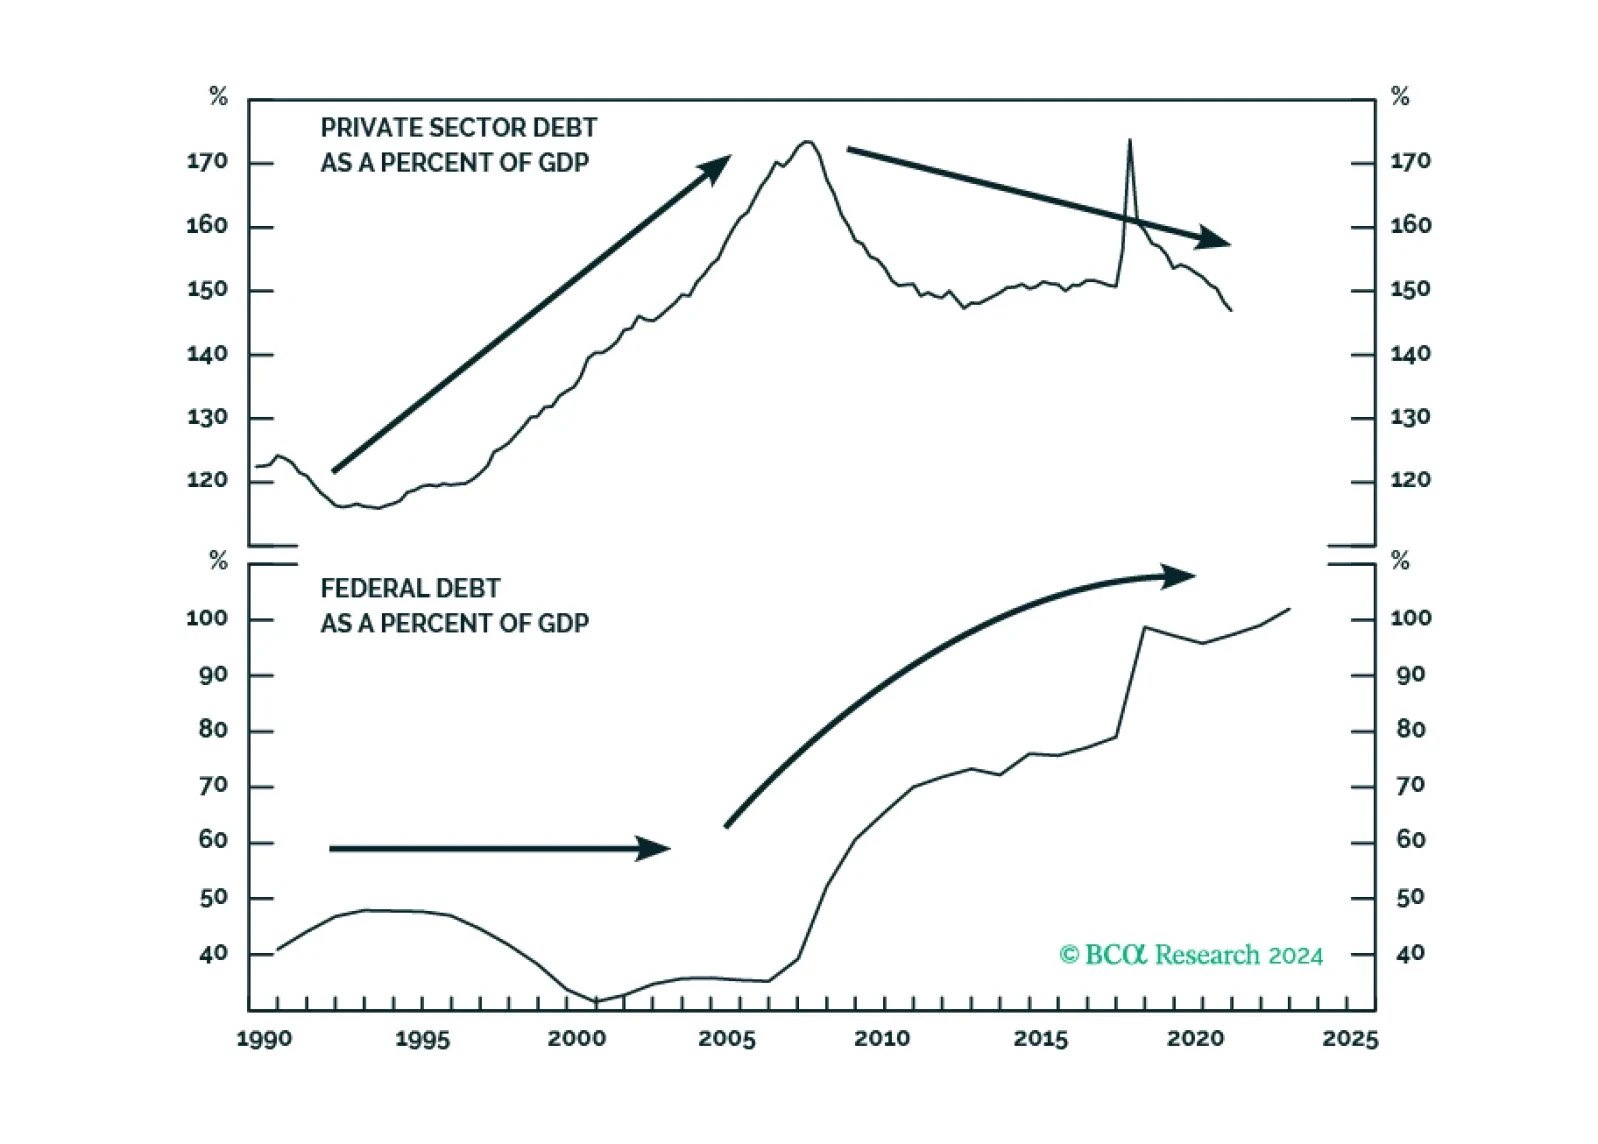
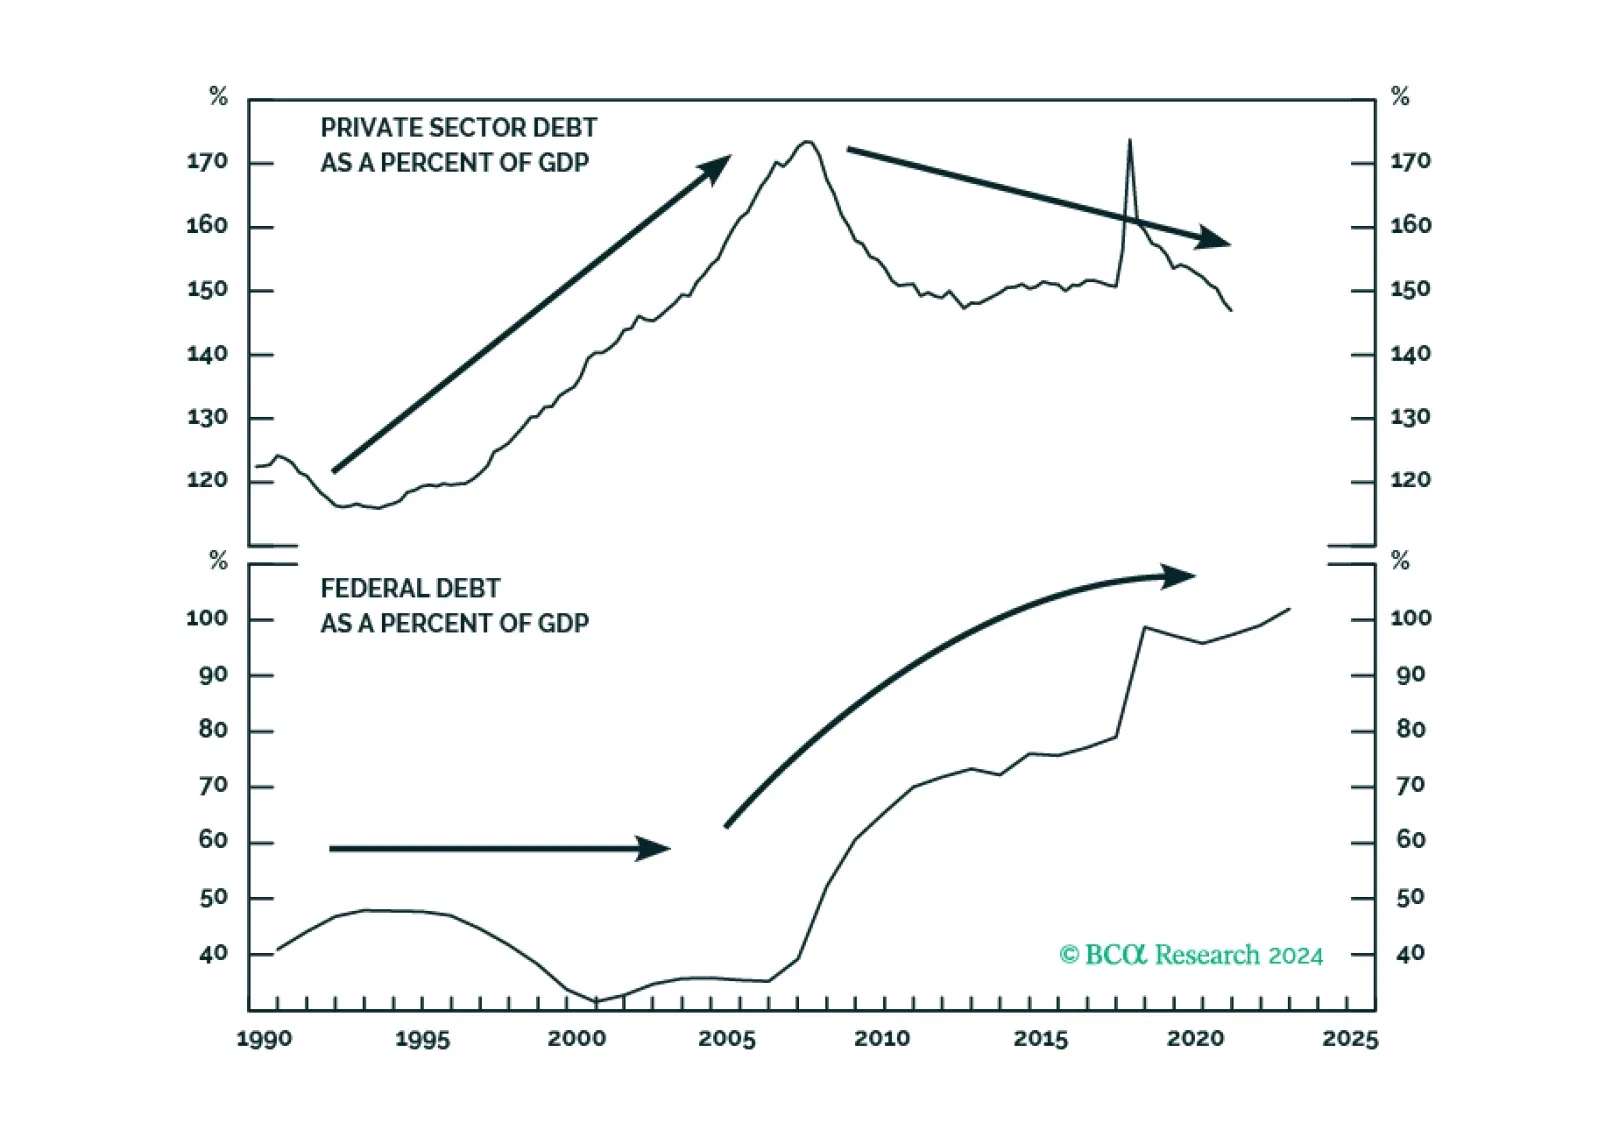
Bank Credit Analyst In a guest research report, Martin Barnes, BCA’s former Chief Economist, revisits the idea of the Debt Supercycle and discusses how its true end may emerge in response to a fiscal crisis in the US over the coming few years.
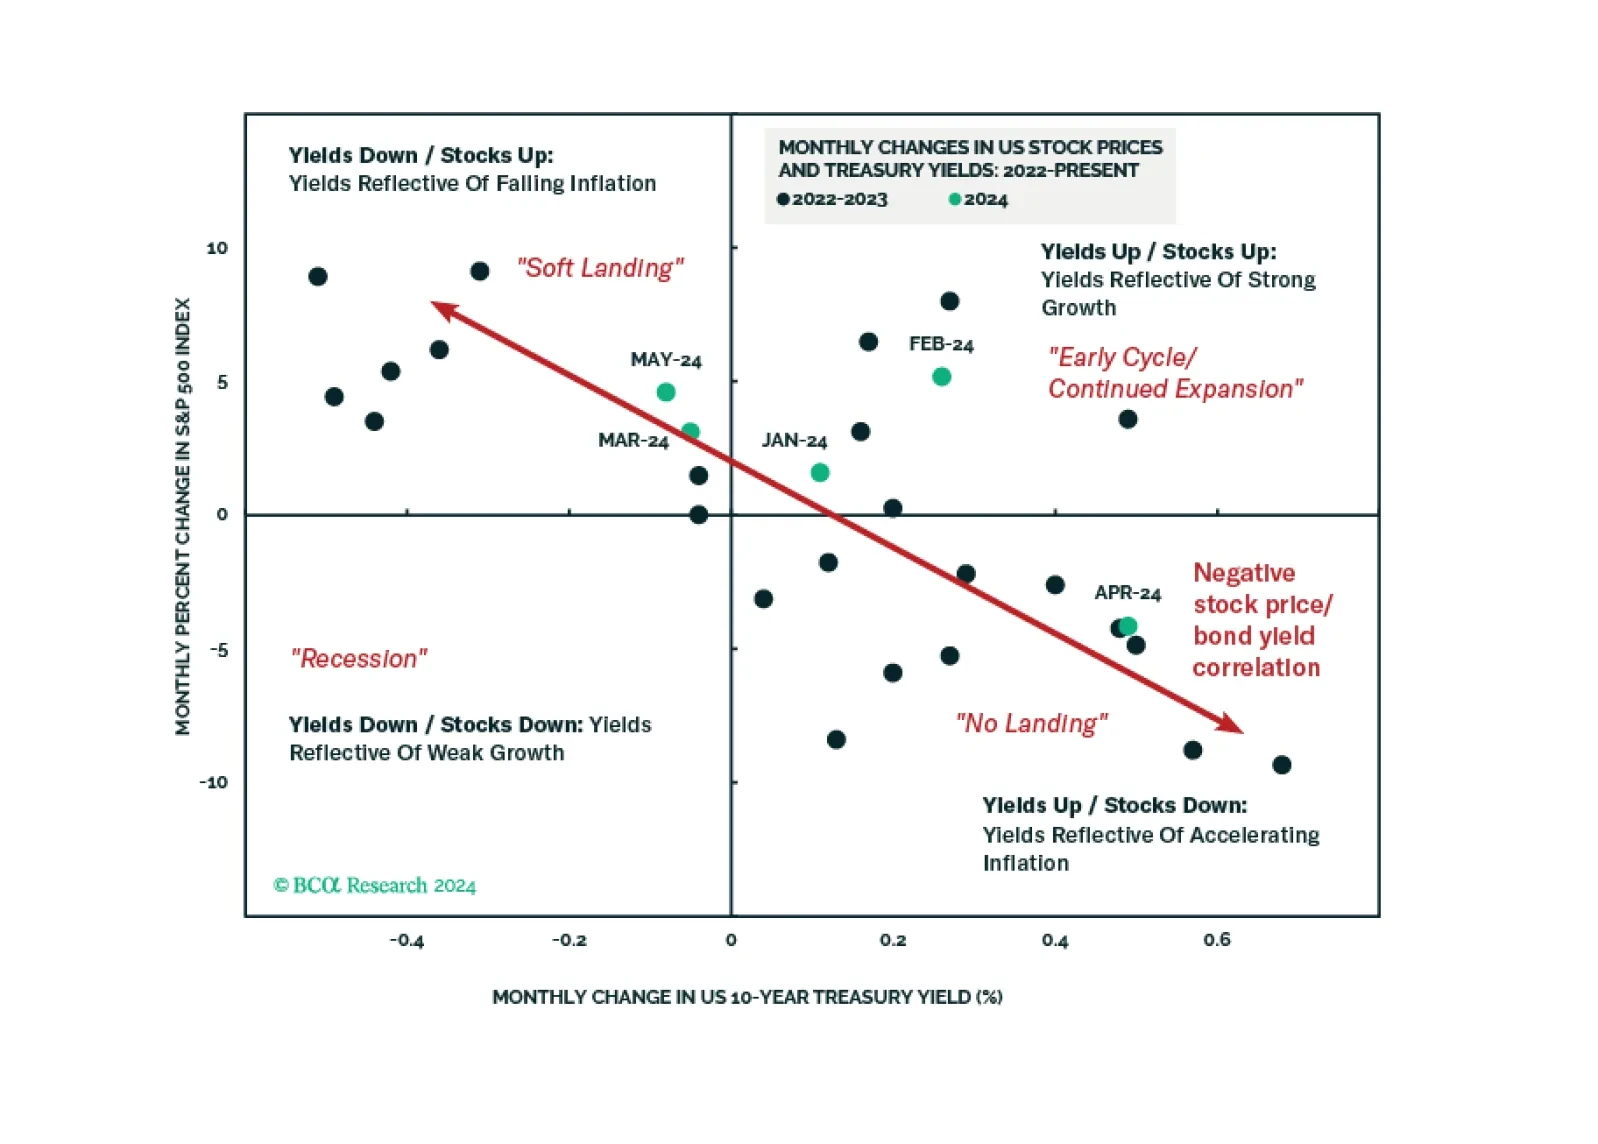
Bank Credit Analyst In Section I, we argue that global investors have been lulled into a false sense of security concerning the resiliency of the US economy. Tight monetary policy means that something must change for a recession to be avoided, and developed market rates cuts will likely be too modest and come too late to save the day. Nimble investors or those highly sensitive to tracking error should not be underweight stocks over the coming 3-6 months. Over a 6-12 month time horizon, we continue to recommend that investors remain underweight global equities versus US$-hedged long-maturity developed market government bonds. Section II is a guest report written by Martin Barnes, BCA’s former Chief Economist. Martin revisits the idea of the Debt Supercycle and discusses how its true end may emerge in response to a fiscal crisis in the US over the coming few years.
Bank Credit Analyst In a guest research report, Martin Barnes, BCA’s former Chief Economist, revisits the idea of the Debt Supercycle and discusses how its true end may emerge in response to a fiscal crisis in the US over the coming few years.
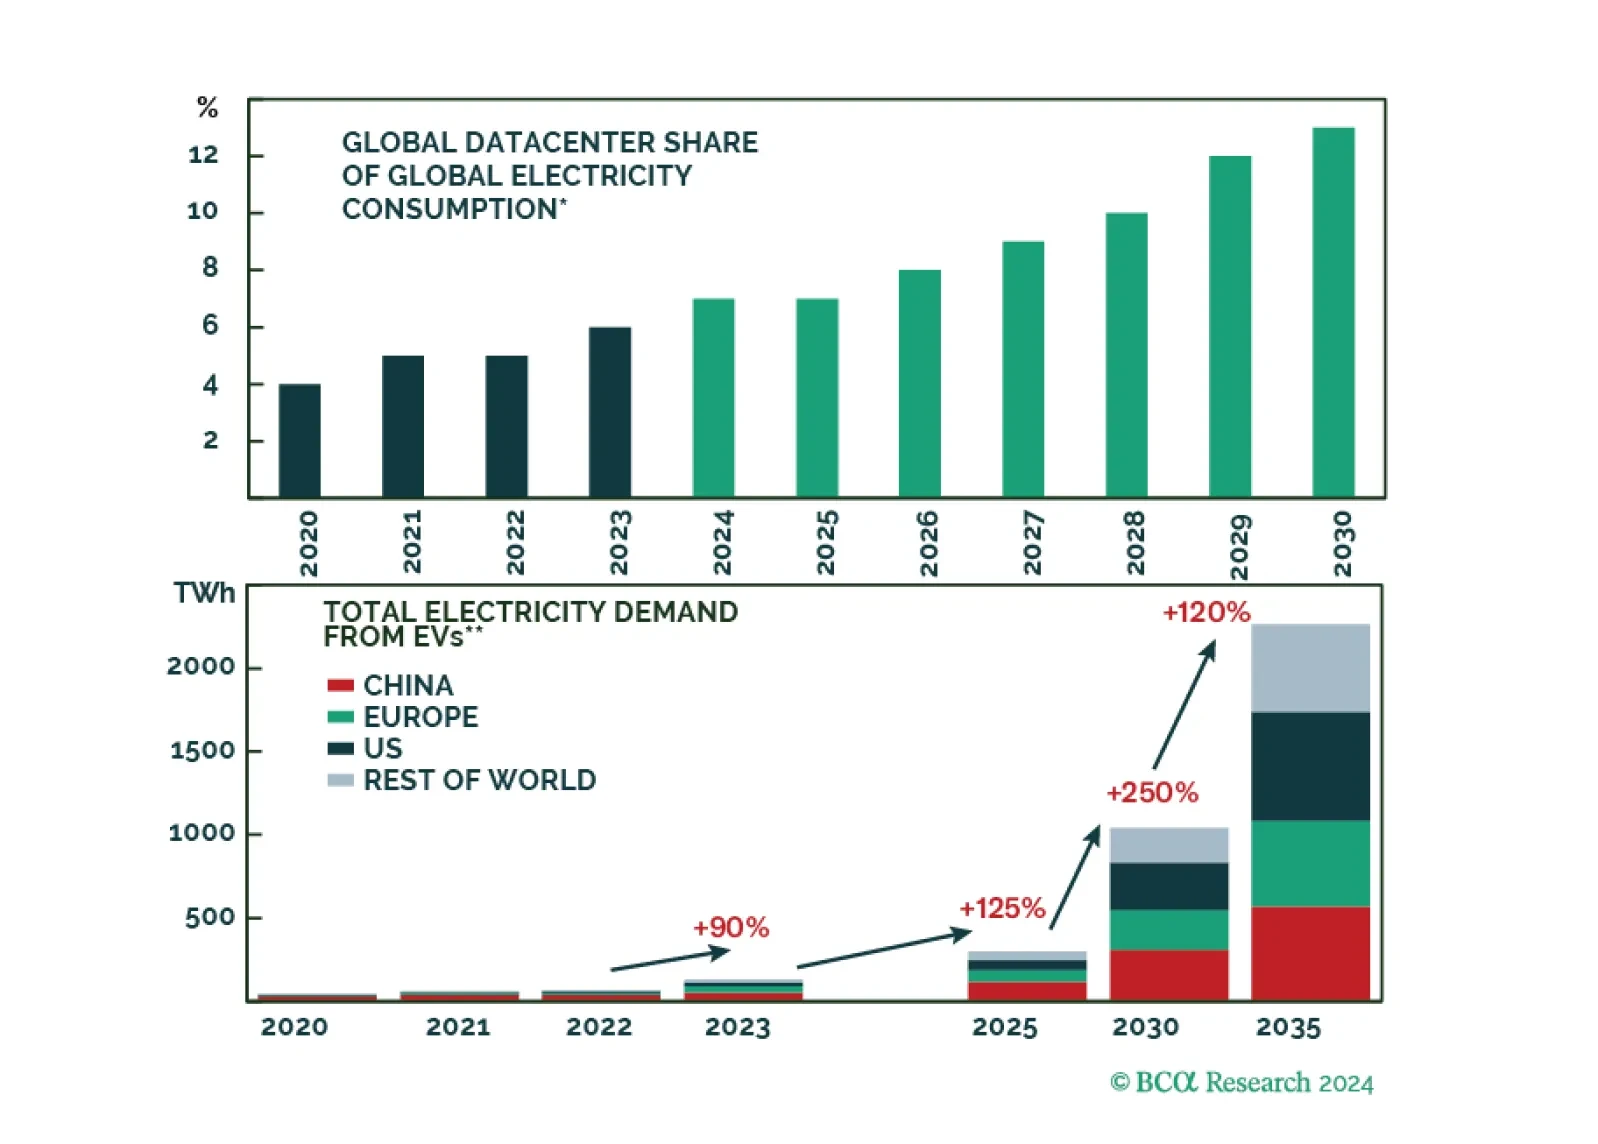
Bank Credit Analyst AI, EVs, and reshoring will lead to a massive surge in demand for electricity. Carbon-free, cheap, baseload nuclear energy stands to greatly benefit from these megatrends going forward.
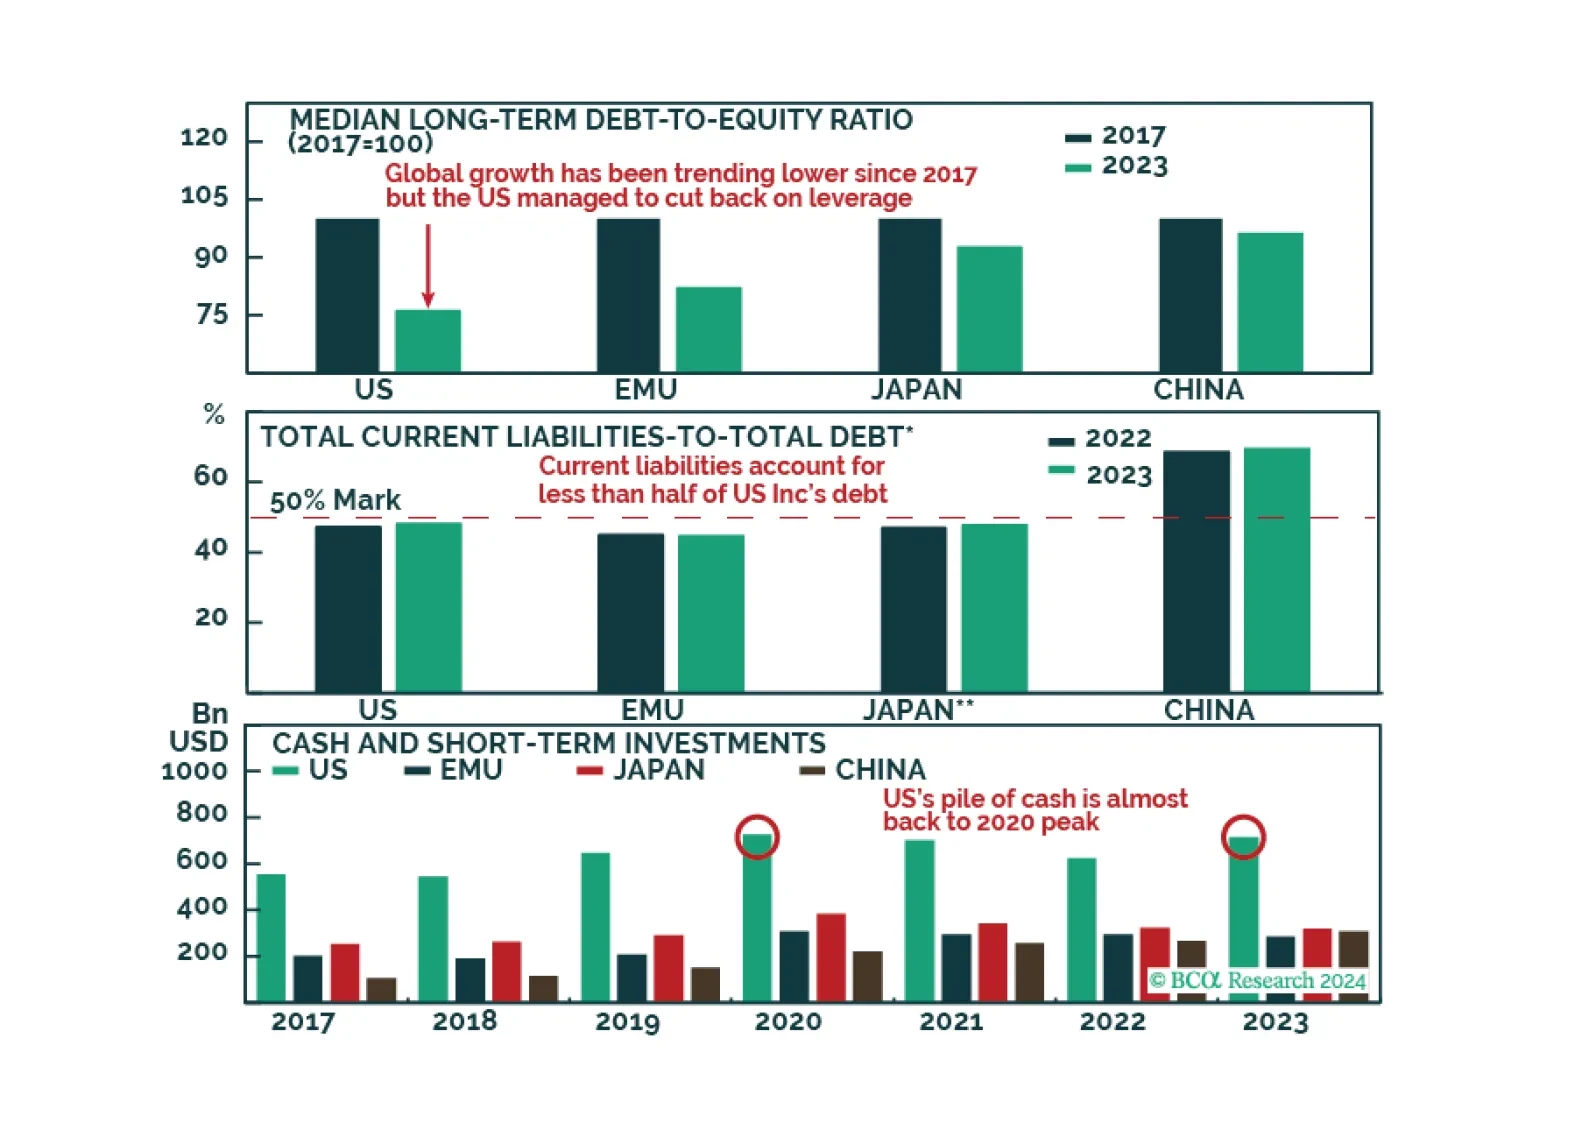
Bank Credit Analyst In a guest authorship of Section I, Doug Peta addresses the recession skepticism often raised by investors. Excess savings are nearly or already drained, labor market indicators remain consistent with an eventual contraction in payroll growth, and there are no signs that credit growth will keep consumer spending afloat. Additionally, this month’s Section II is a guest piece written by Ritika Mankar of BCA’s Global Investment Strategy service. Ritika checks in on the balance sheet health of large, global, listed nonfinancial firms. Firms in the US and Japan appear to be the most resilient in advance of a coming recession, followed by Europe. Chinese firms are the least resilient from a balance sheet perspective.
Bank Credit Analyst Stay overweight US equities versus world, long US energy sector versus Middle East stocks, and long Canada and Mexico versus global-ex-US stocks.
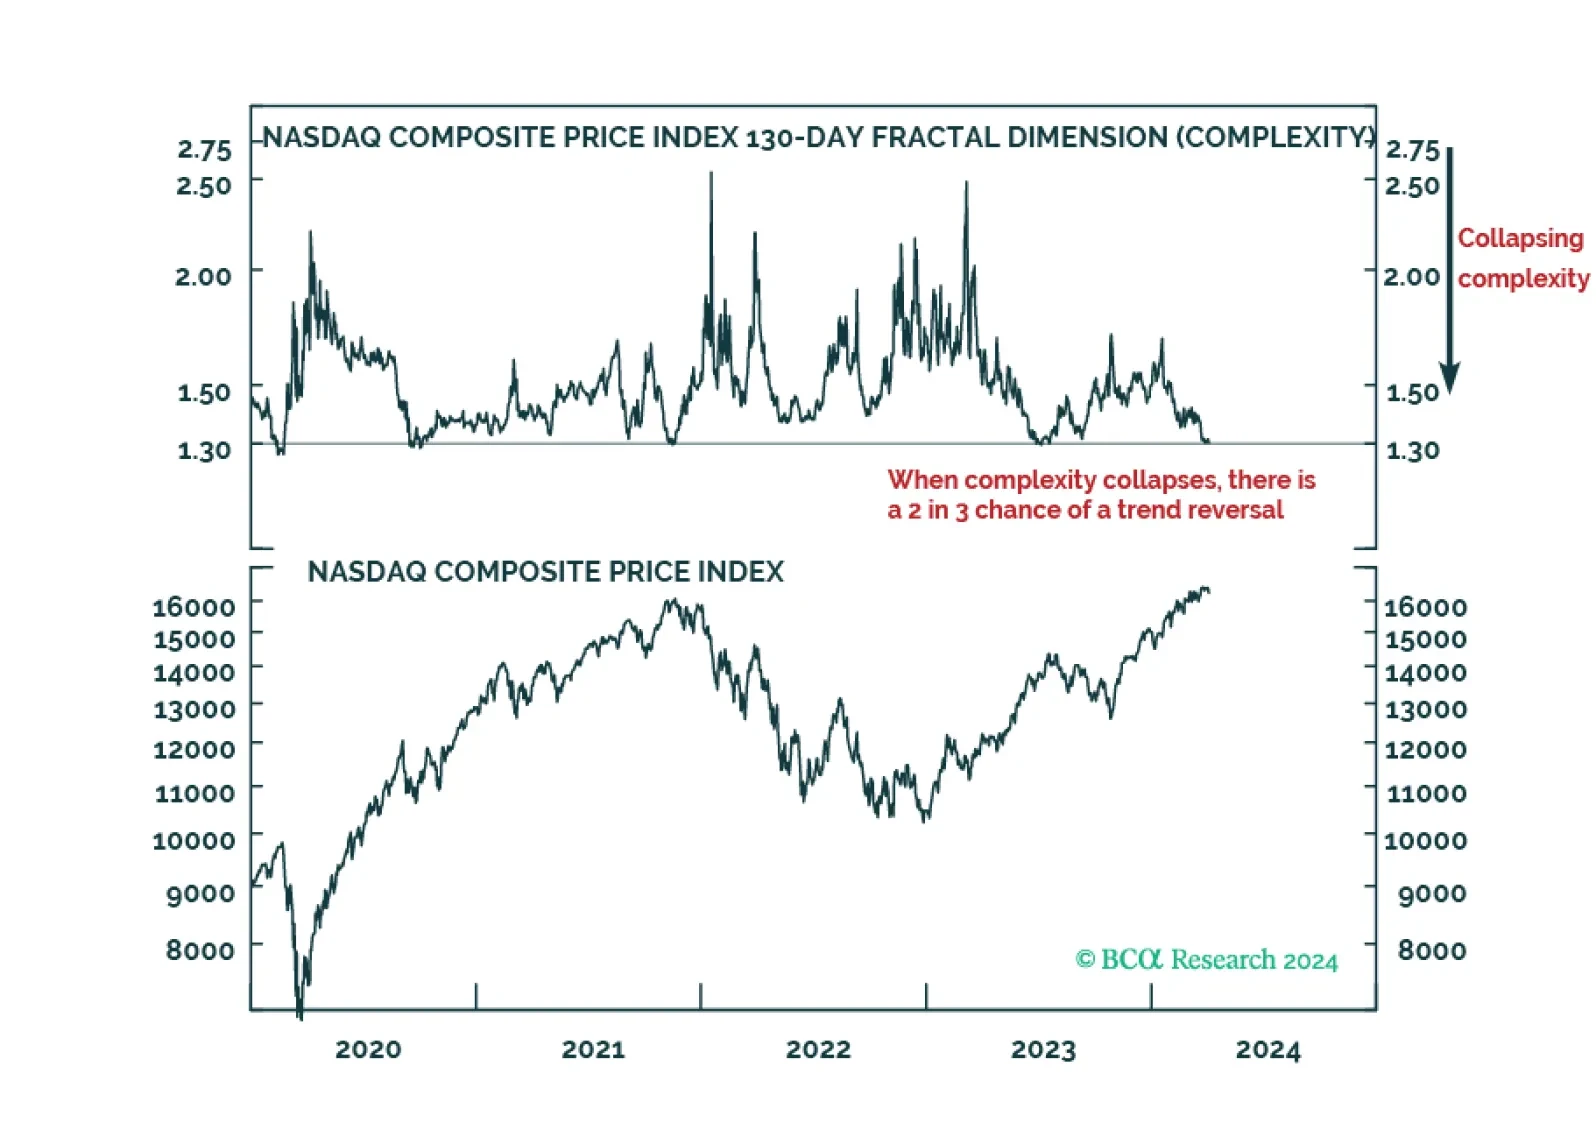
Bank Credit Analyst The analysis of complexity is a massive competitive advantage in investing, and from today, clients will be able to monitor the complexities of the world’s 17 major investments on our webpage in real-time.