Latest from BCA Research
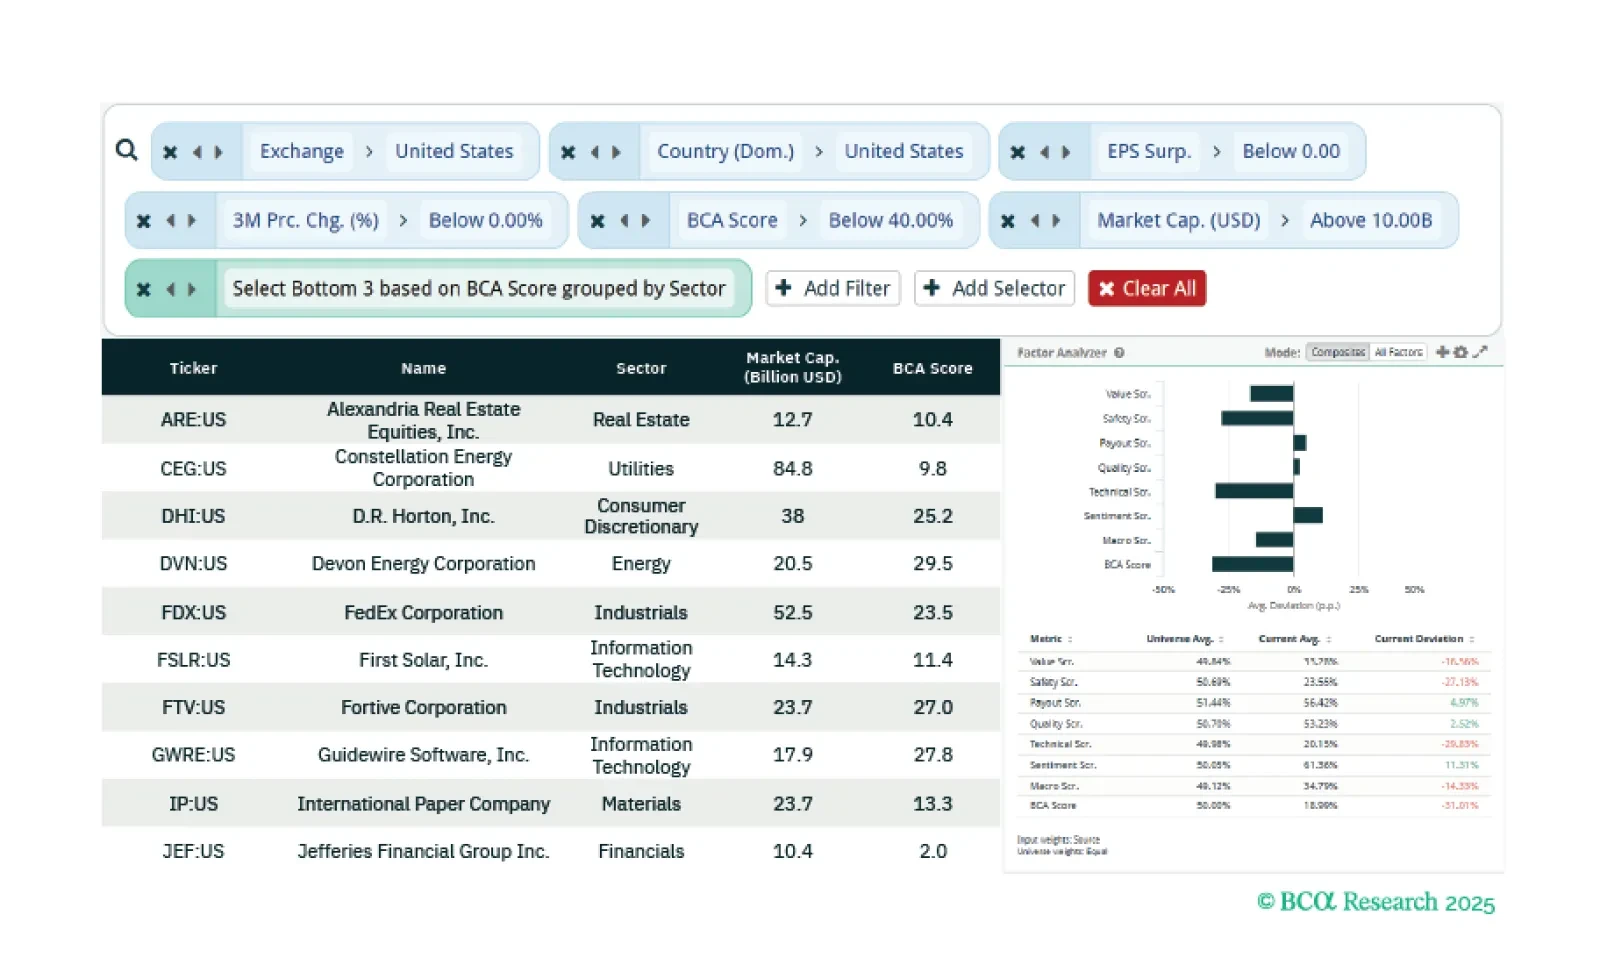
This week, our three screeners cover: Identifying stocks with negative earnings leading into Q2; picking out losing stocks from a tariff-induced margin squeeze; and a tactical opportunity in high-scoring sentiment stocks.
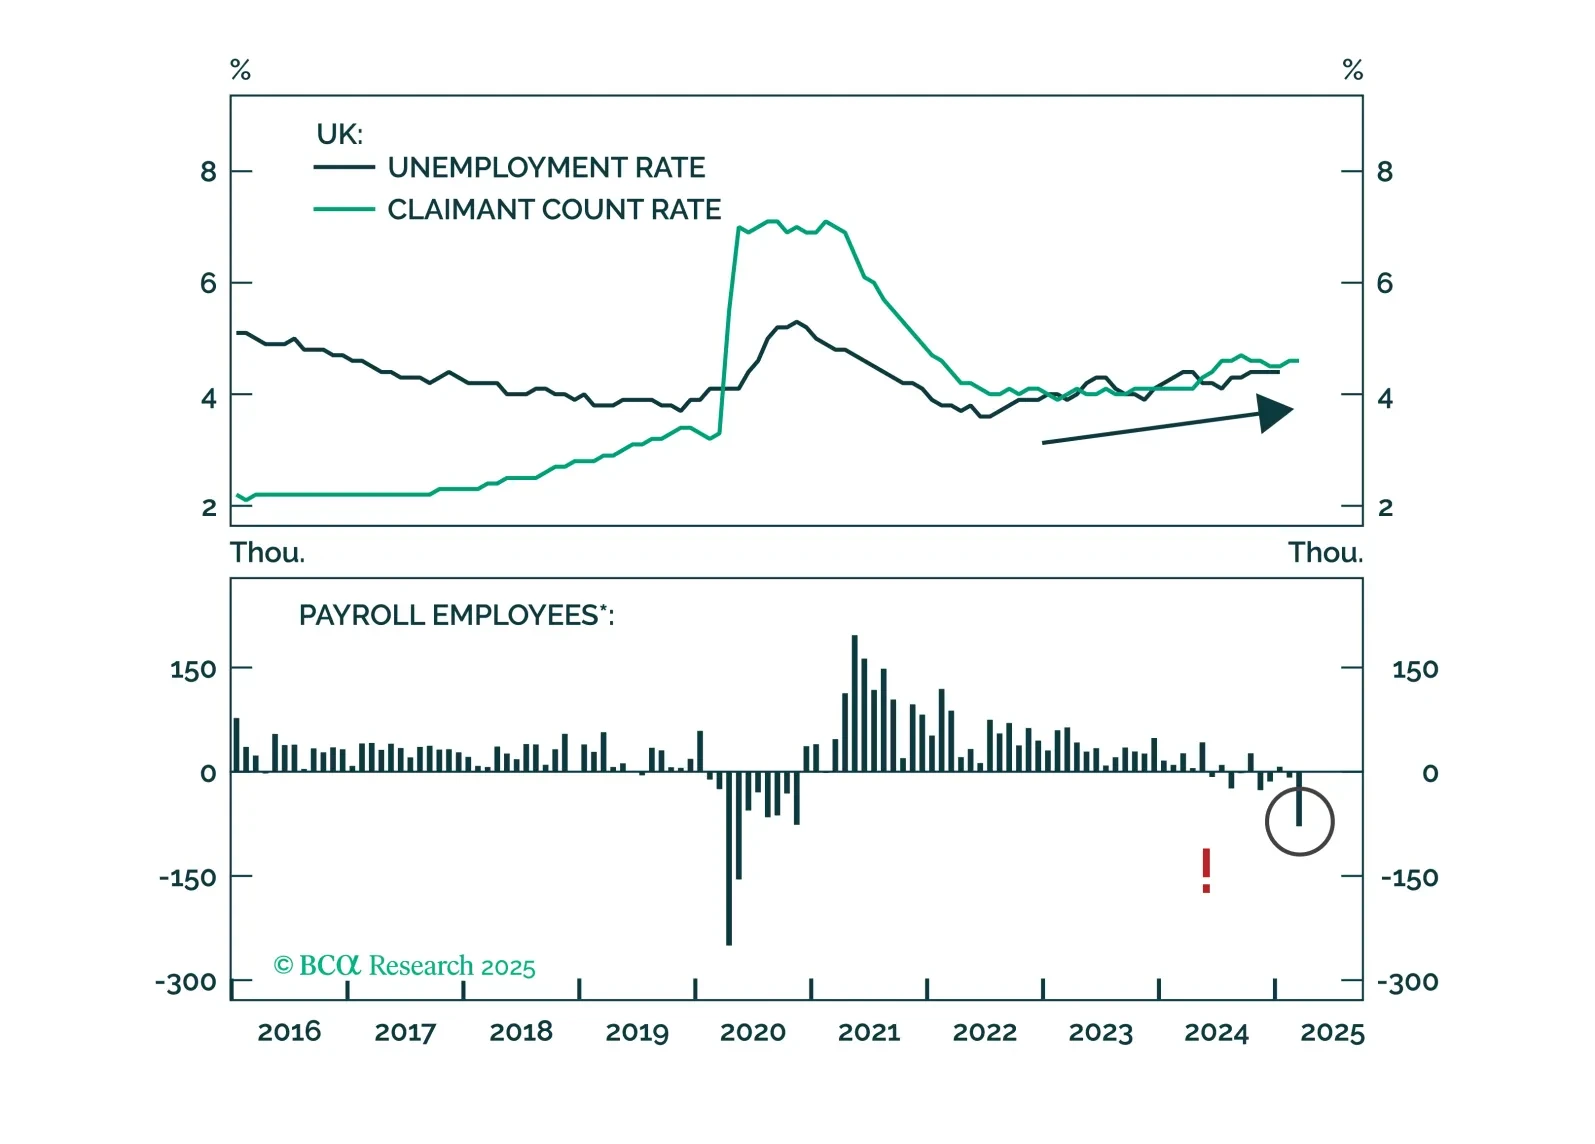
Rate cuts, recession risks, and relative value. This report unpacks how the BoE, Riksbank, and Norges Bank are reacting to global trade turmoil and where the opportunities lie.
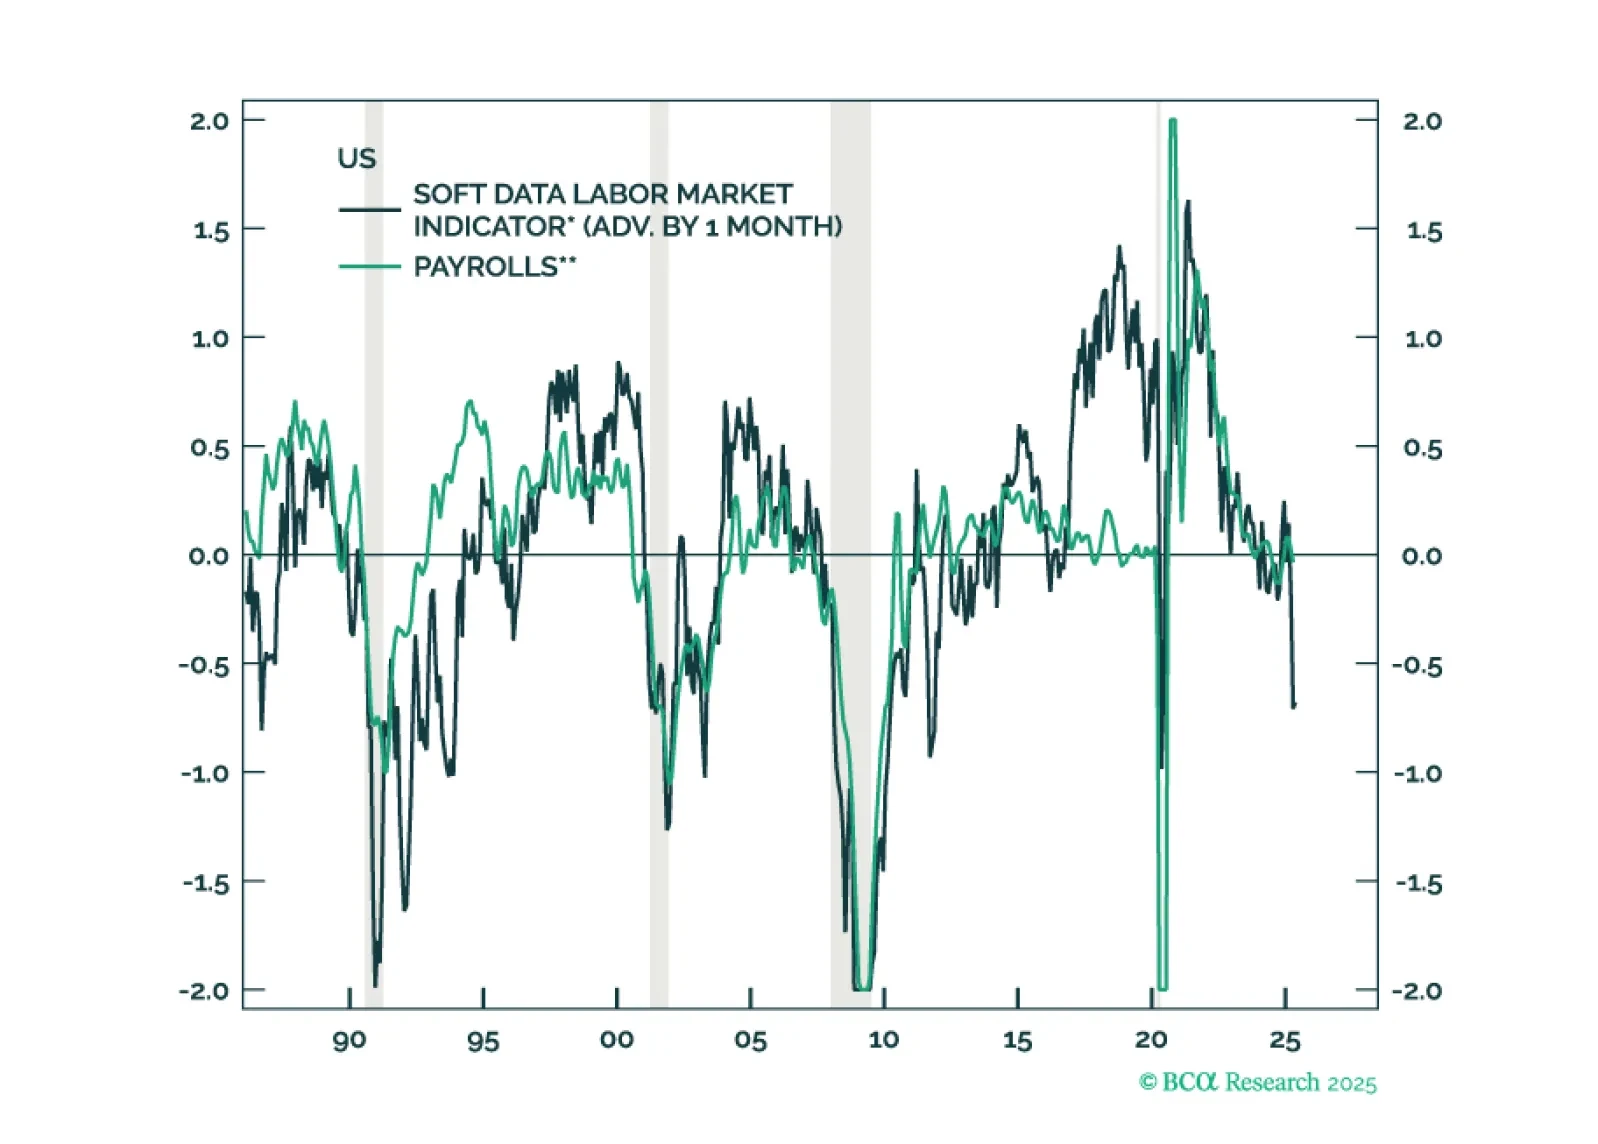
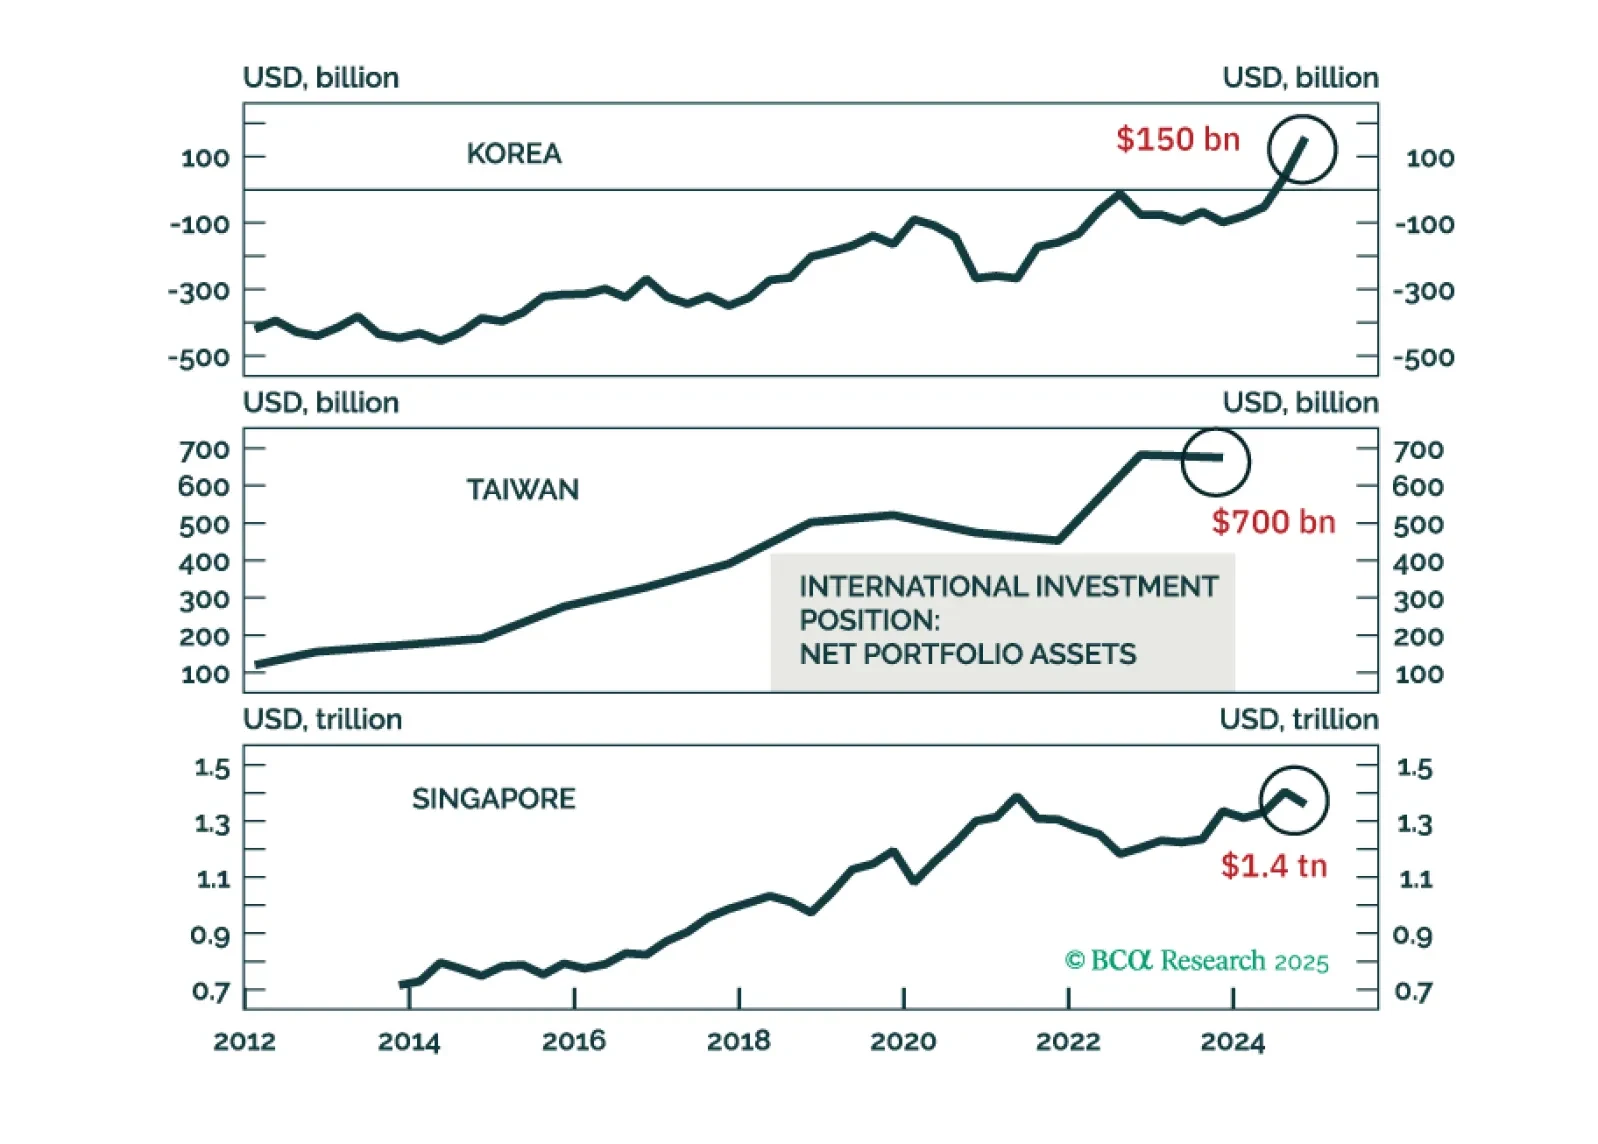
Taiwan, Singapore, and Korea's currencies might appreciate versus the USD, driven by capital repatriation from domestic private investors away from the US. This thesis is less pertinent to India, Indonesia, and the Philippines because they have large net foreign portfolio liabilities. Malaysia and Thailand fall in the middle, while China is an exception. Investors should play intensifying deflationary pressures in Asia by betting on lower interest rates in the region.
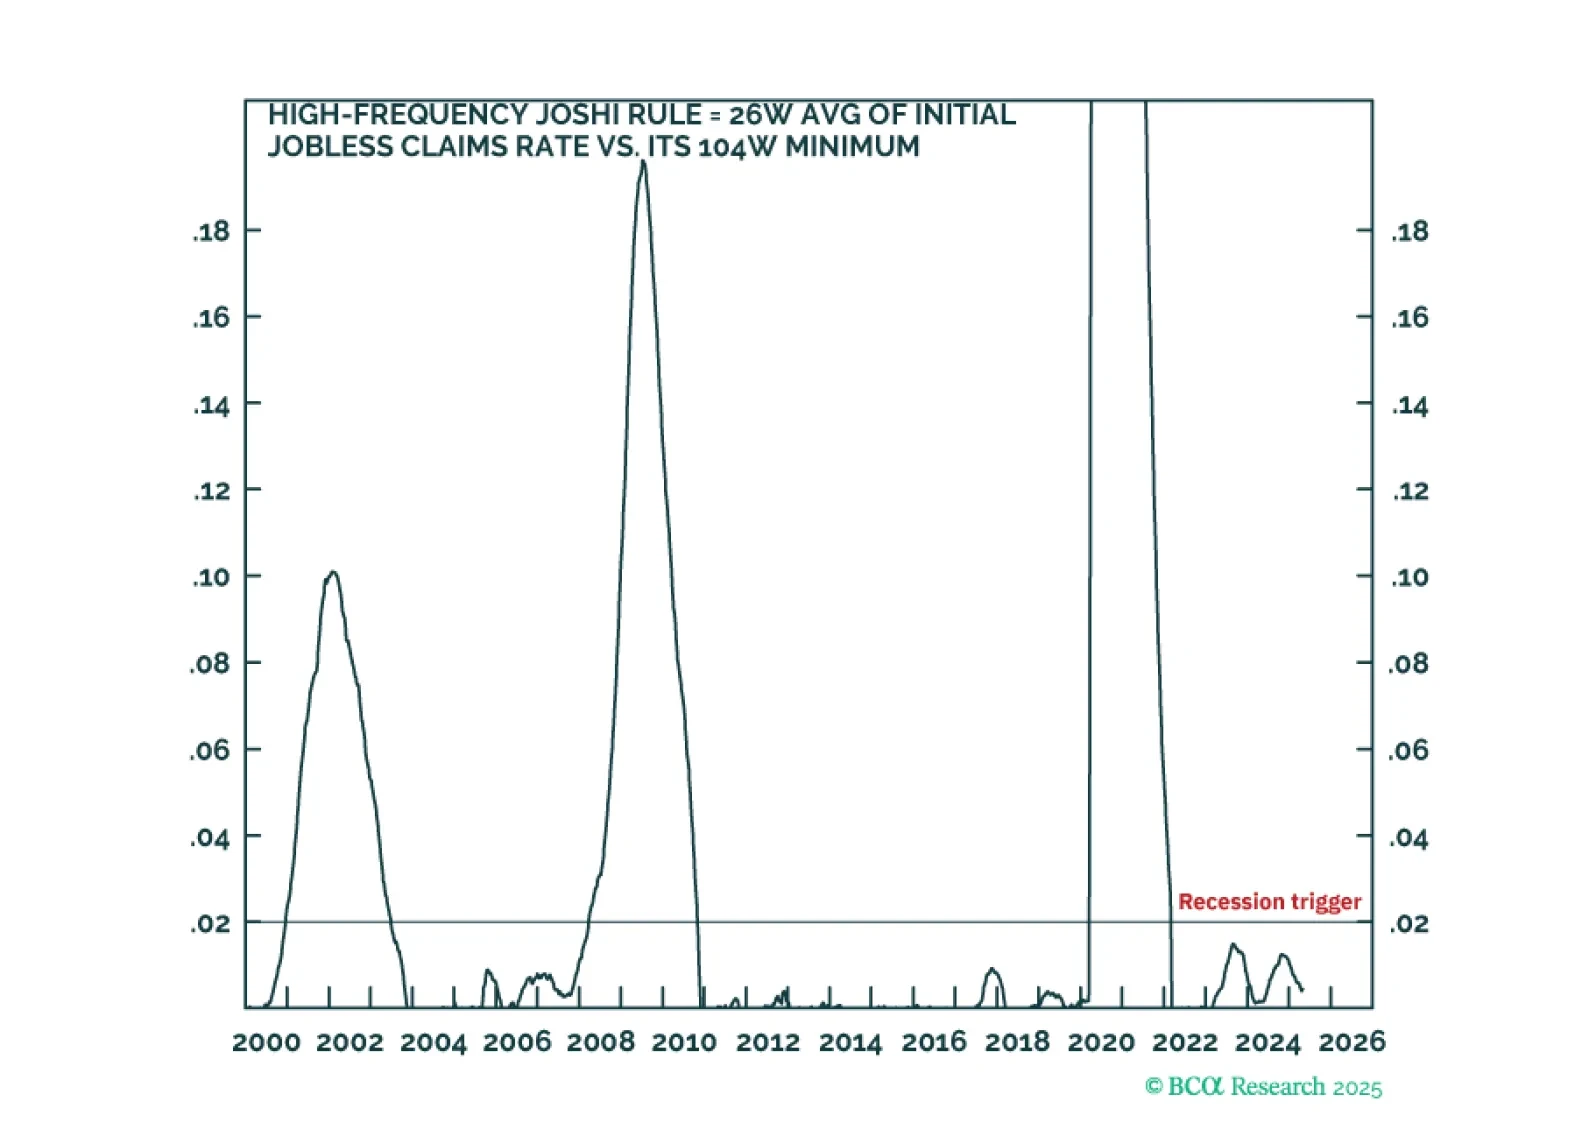
Today, we are introducing an additional ‘high-frequency Joshi rule’ which is updated weekly. The Joshi rules tell us that a US recession is not imminent. Until the Joshi rules are triggered, overweight non-US government bonds, and especially UK gilts, versus US T-bonds. And shift cyclical asset allocation from overweight to neutral-weight bonds. Plus: tactically long USD/GBP and tactically underweight global industrials (EXI).
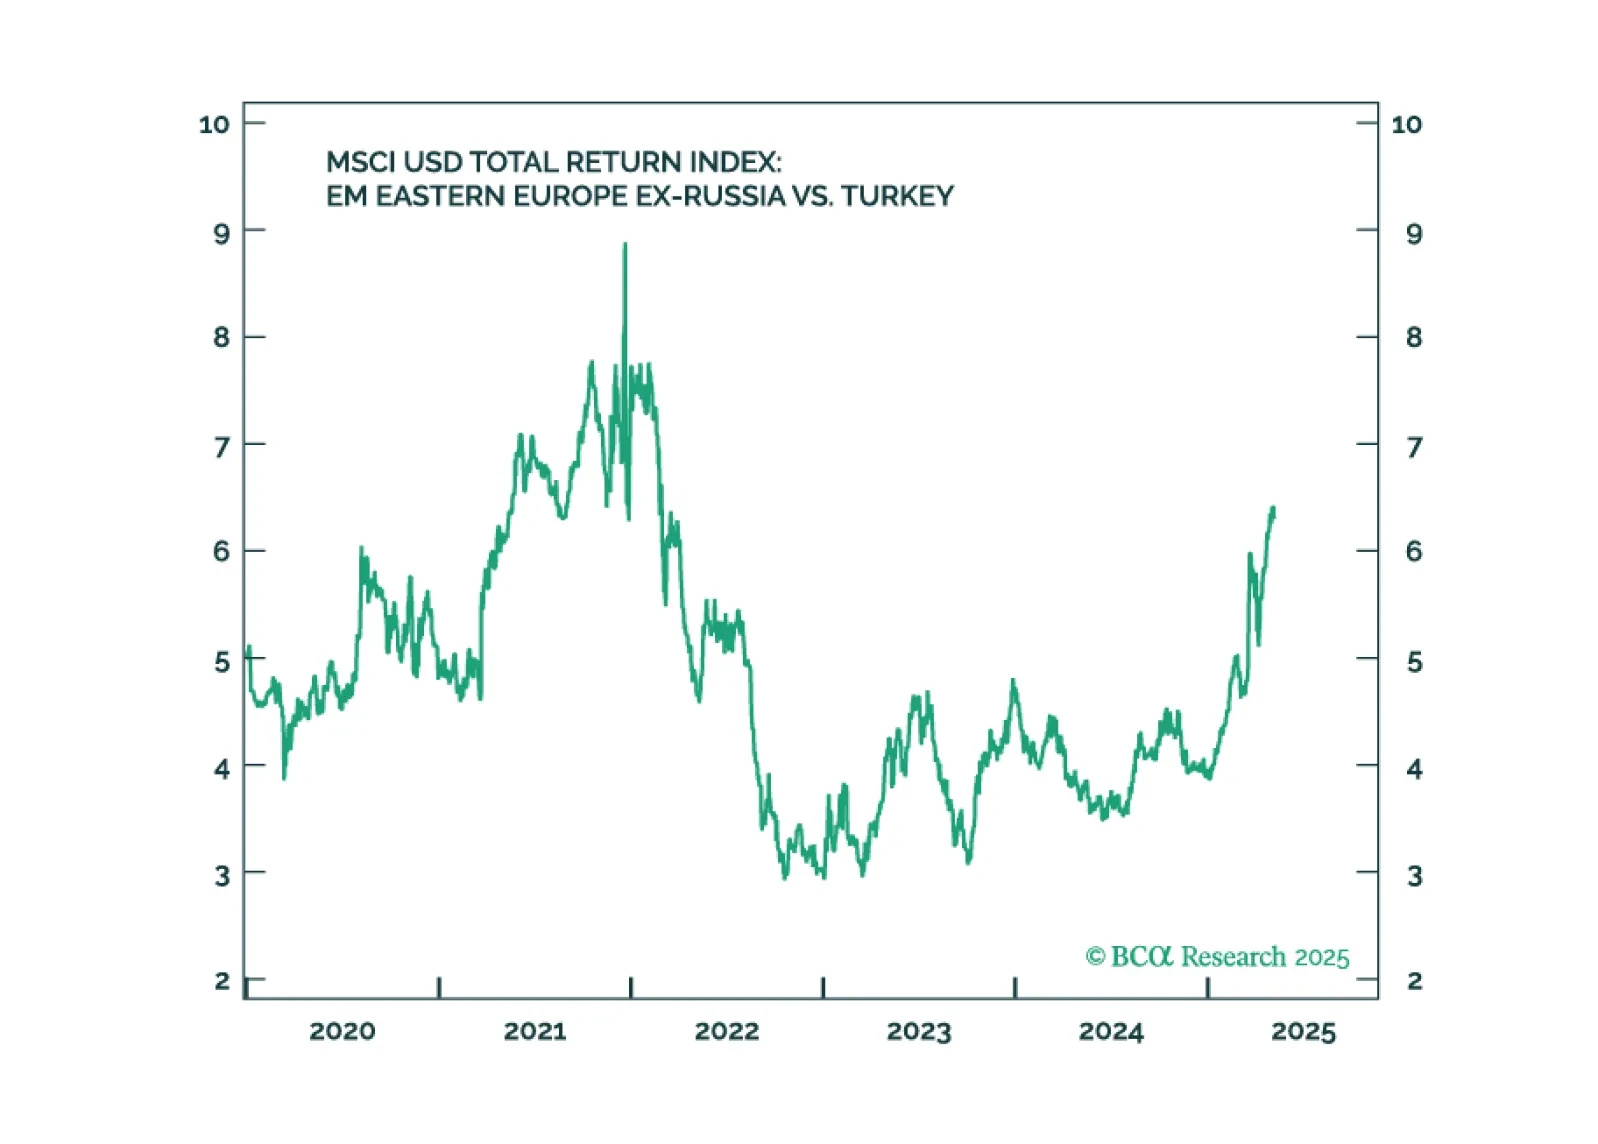
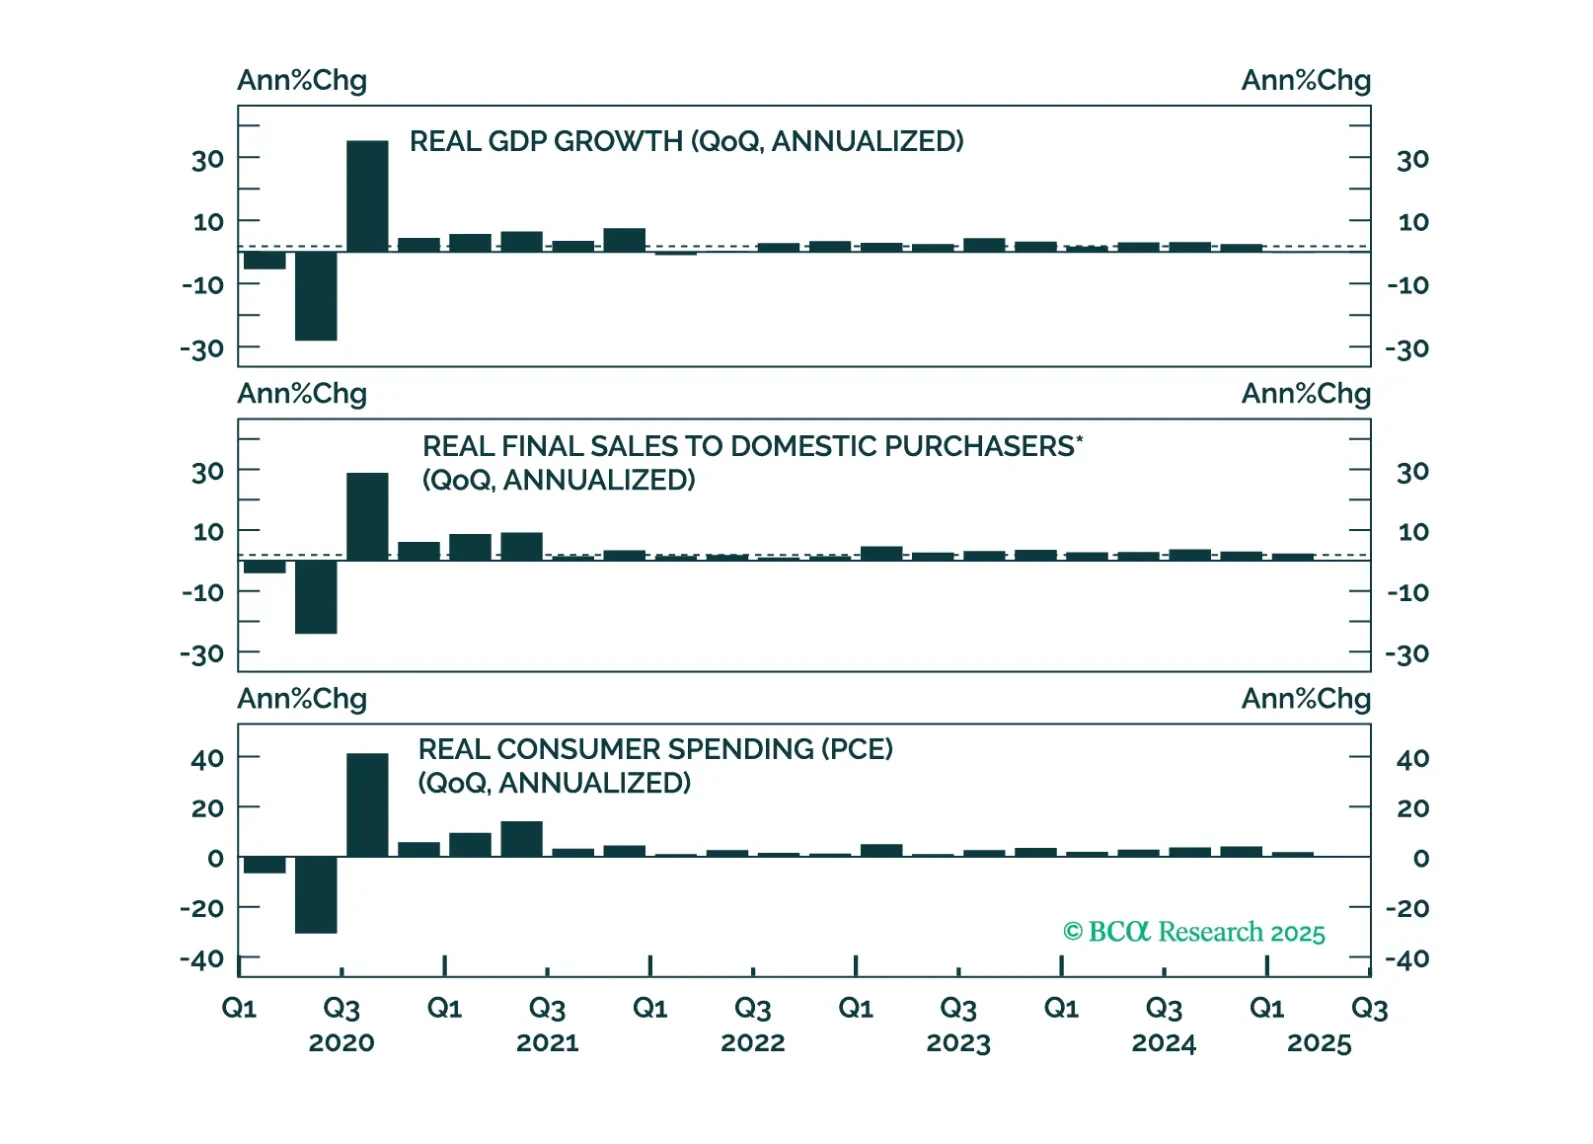
The Fed held rates steady this afternoon, and the timing of its next move will be dictated by whether the tariff shock to inflation is transitory or more long lasting.
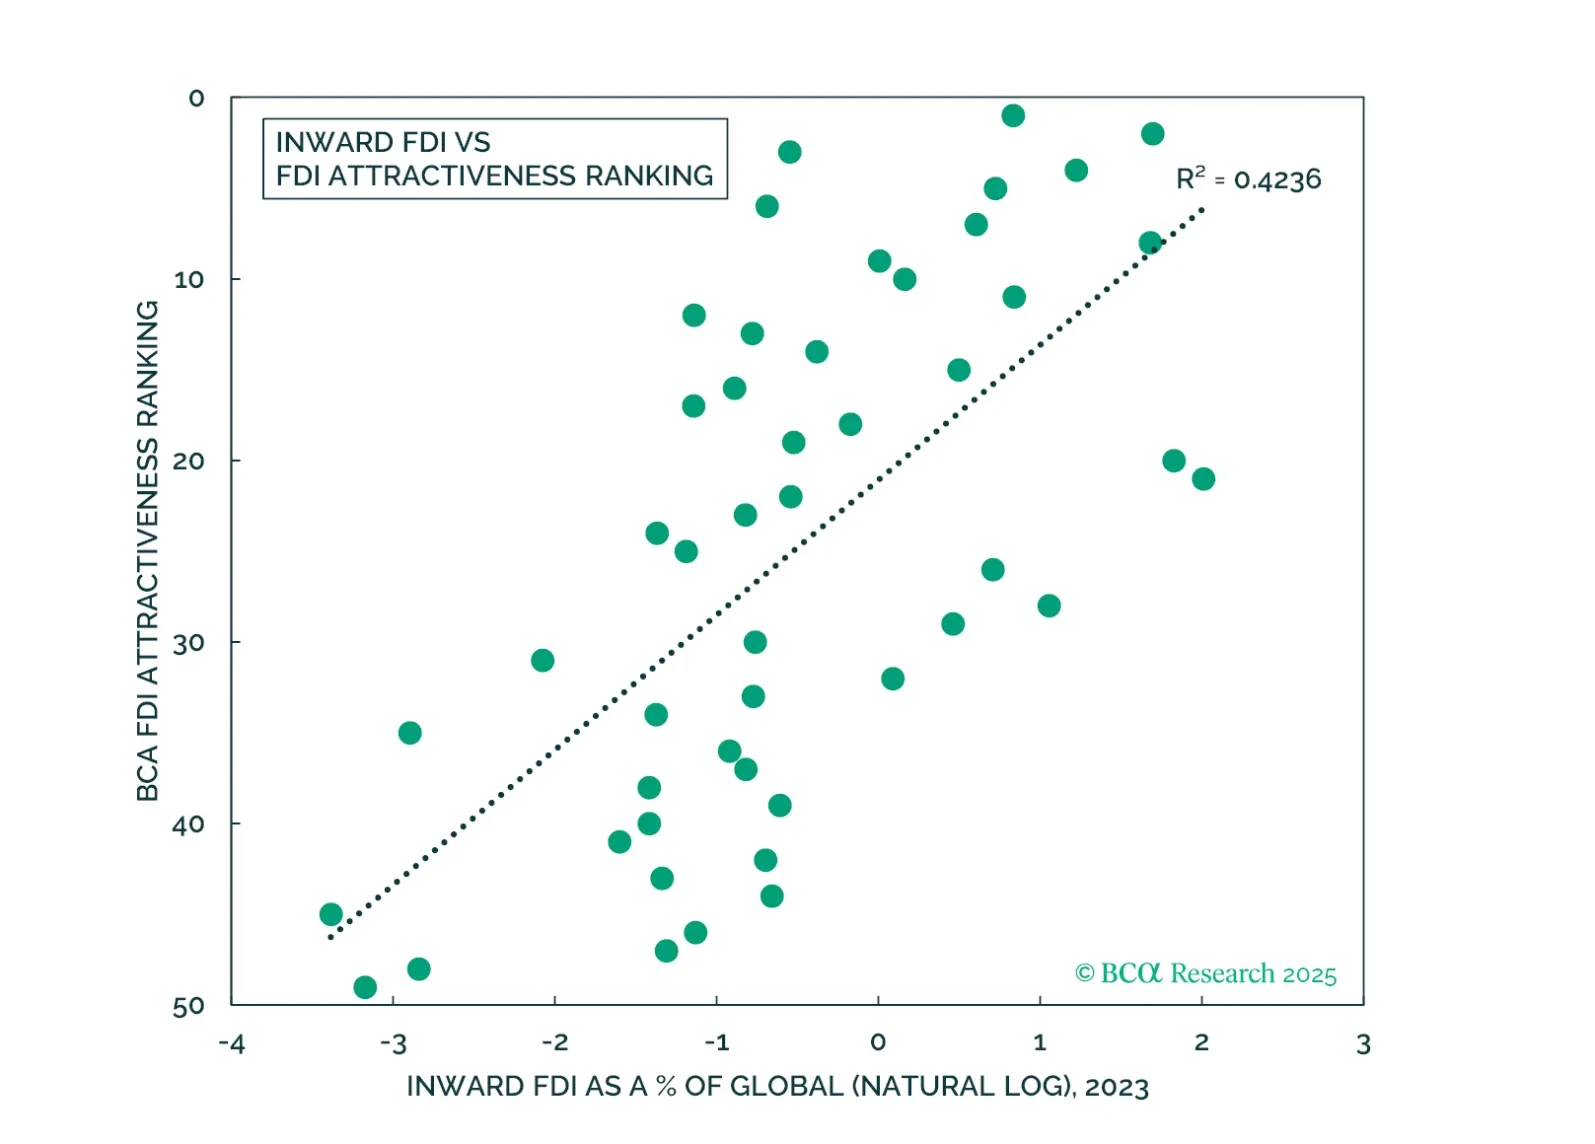
In our Beta report, we do something different. We focus on what factors create a macro context that is conducive to FDI inflows. Market size, trade openness, and infrastructure quality drive appeal, but secondary factors like governance and overall business climate play a meaningful role as well. As FDI reshuffles around geopolitics and new supply chains, competition will heat up among both destinations and investors.