Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
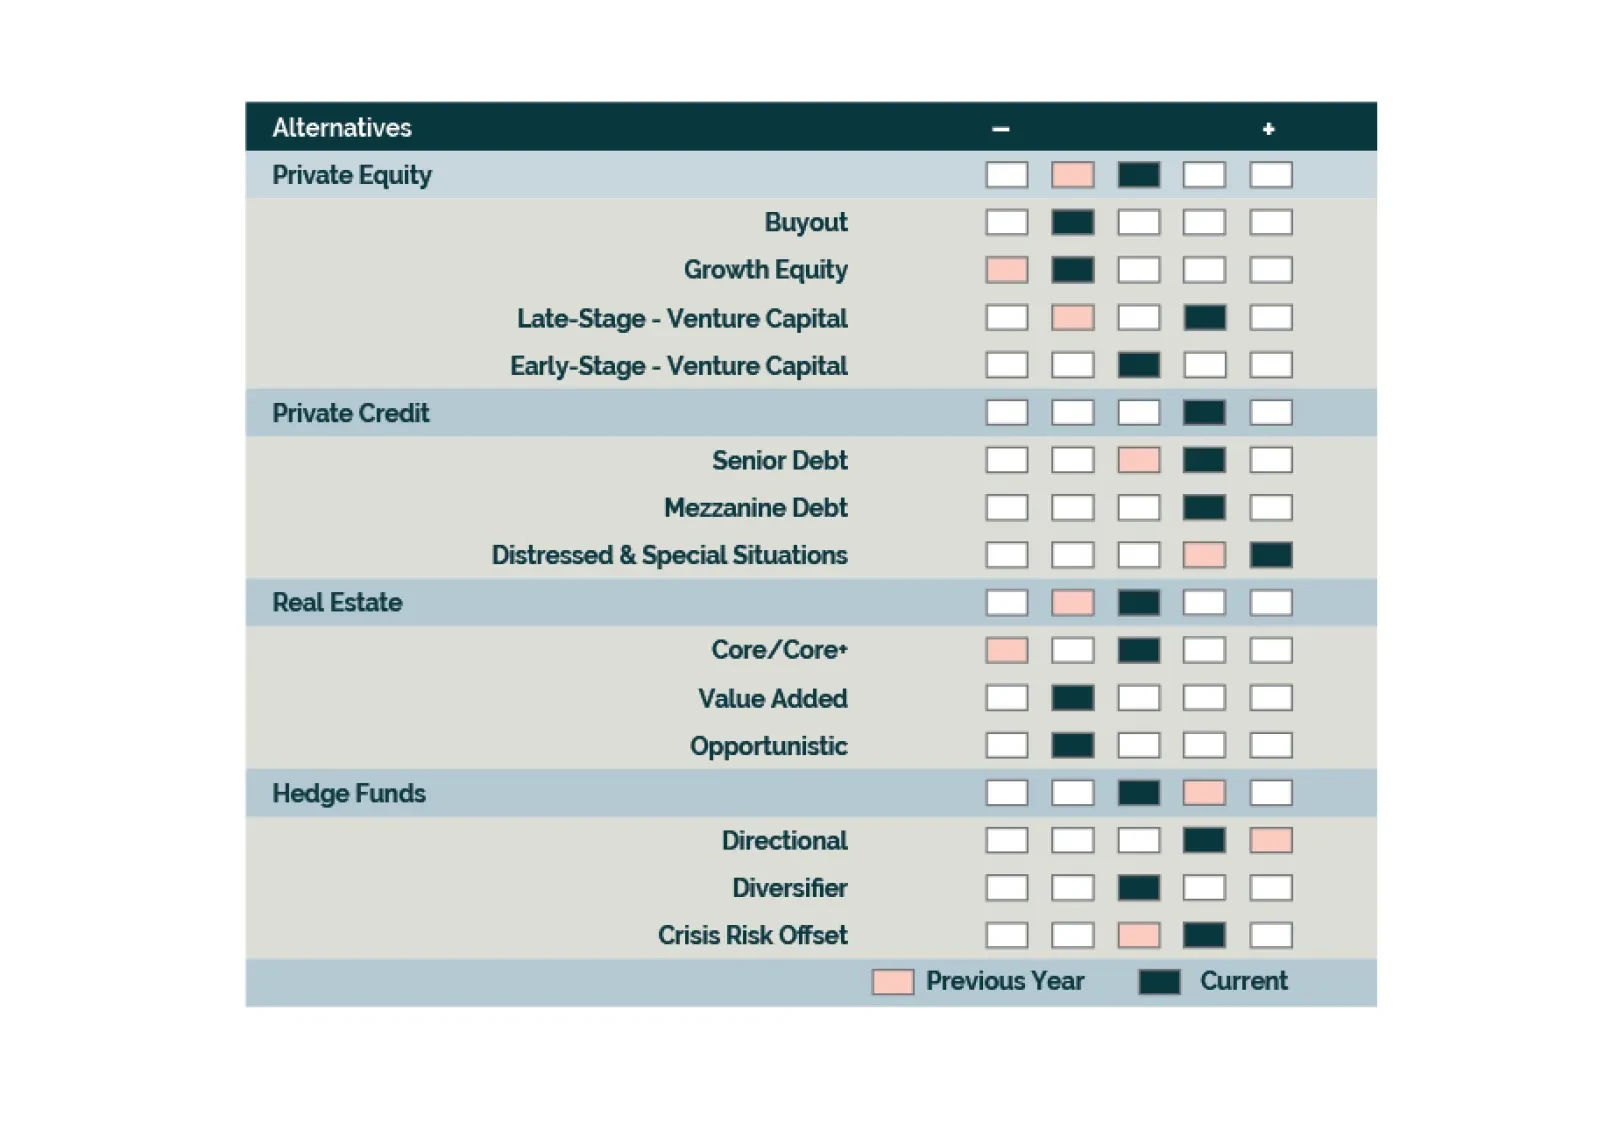
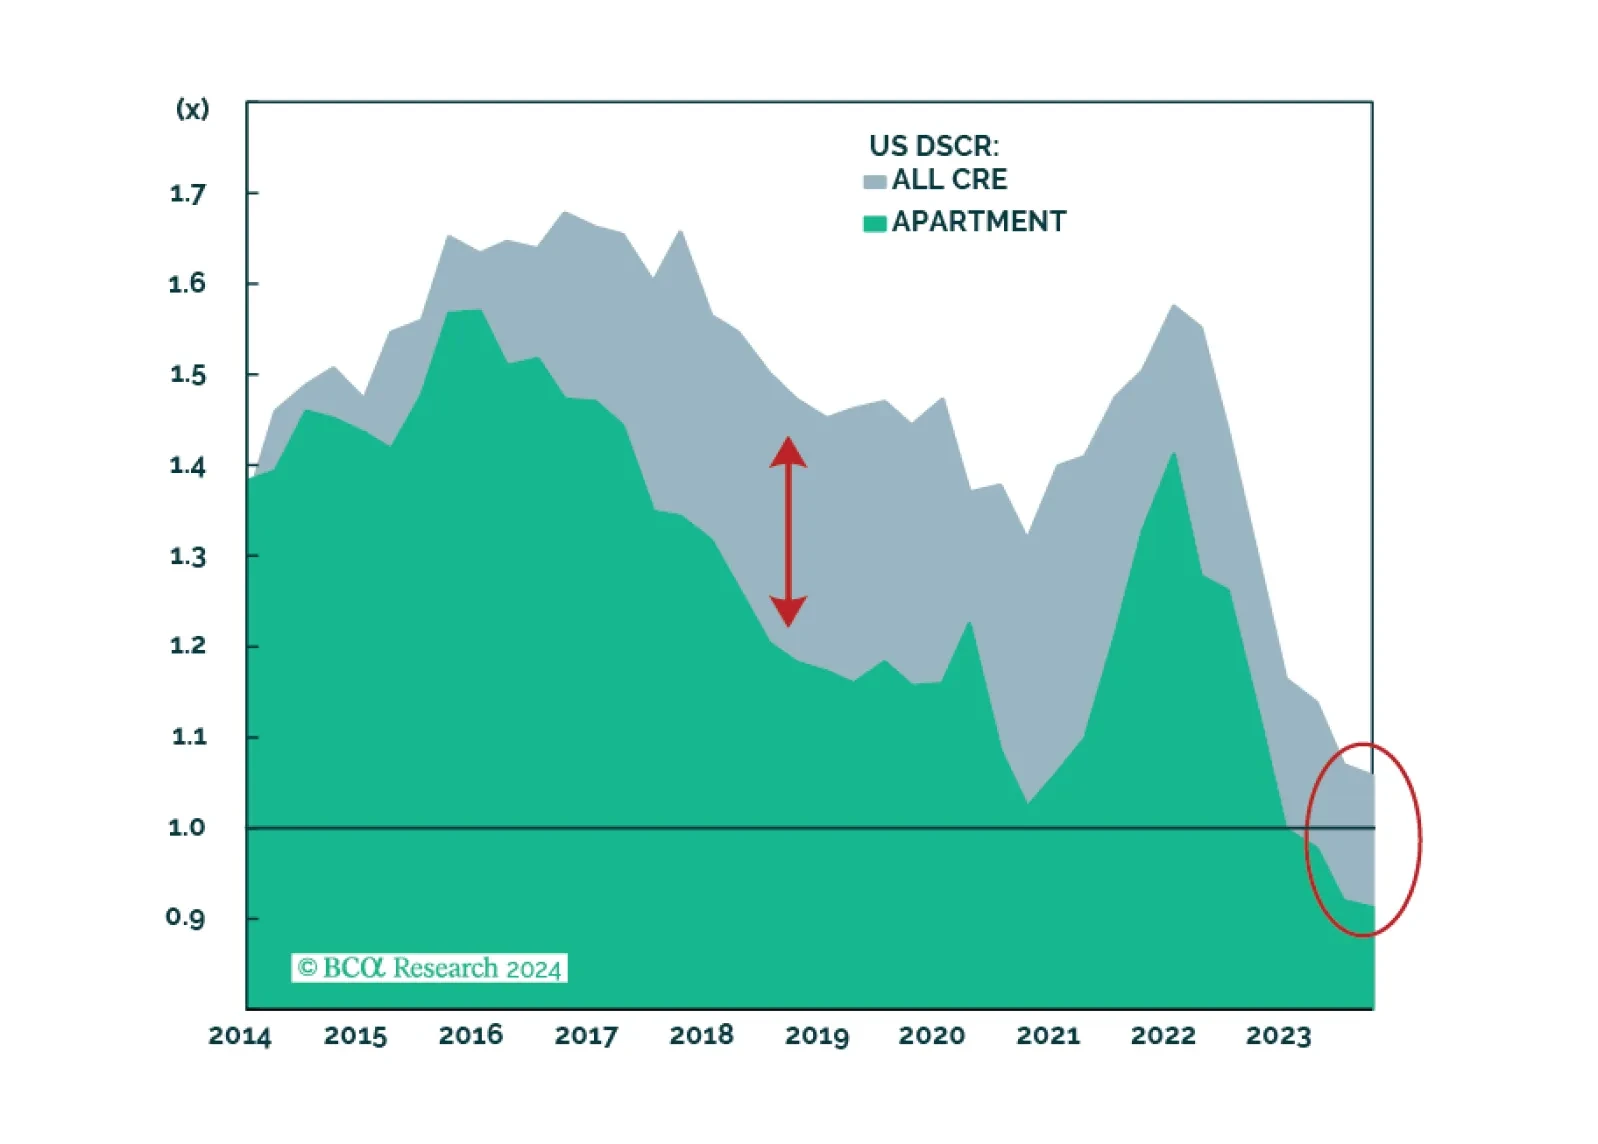
We go overweight Late-Stage Venture Capital and APAC Private Equity but remain underweight North America Buyouts. We maintain our neutral outlook towards Hedge Funds and are positive on Long-Short Equity, Event Driven, and CRO strategies. We are cooling towards Direct Lending strategies as competition and relative opportunities increase. CRE’s downturn continues to unfold; we are starting to be buyers.
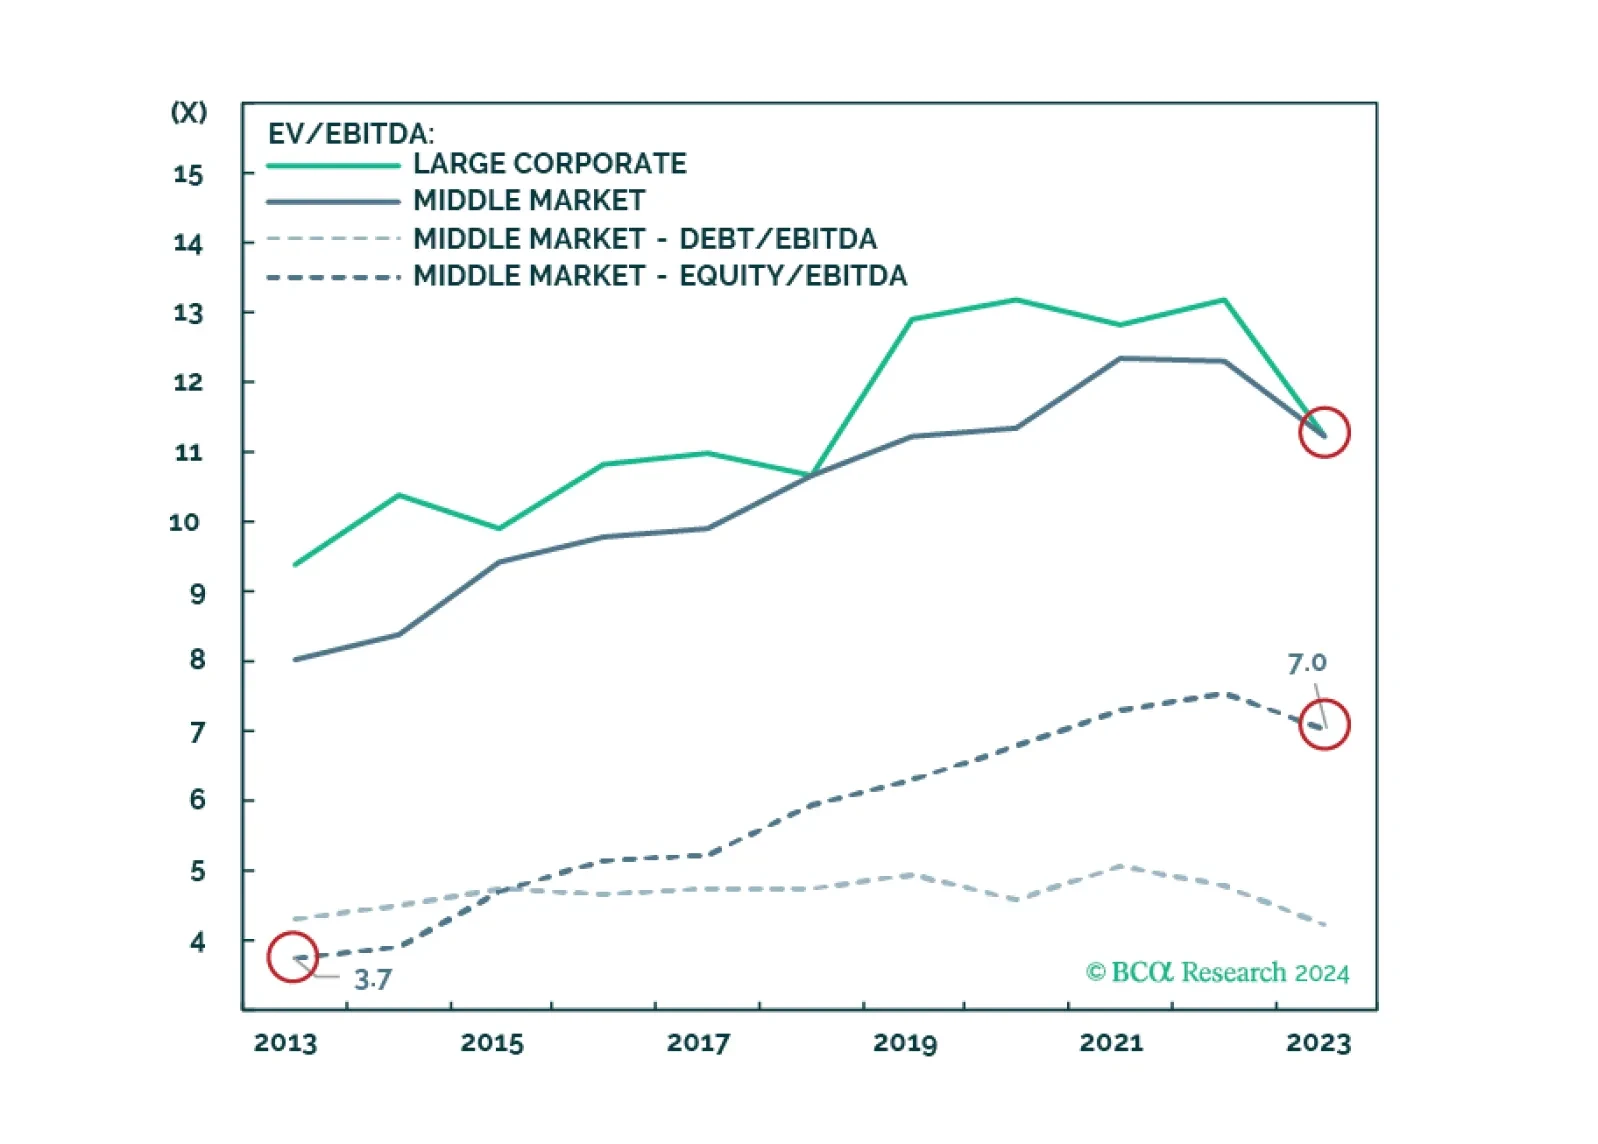
Valuation metrics in Private Equity and Venture Capital vary widely by source, stage, location, and other factors. They are prone to imprecision, which is why investors should monitor a diverse set. This report offers a series of charts comparing valuation ratios. Focusing solely on valuations reveals that North America Middle Market Buyouts appear less attractive and geographical selection will be more important going forward.
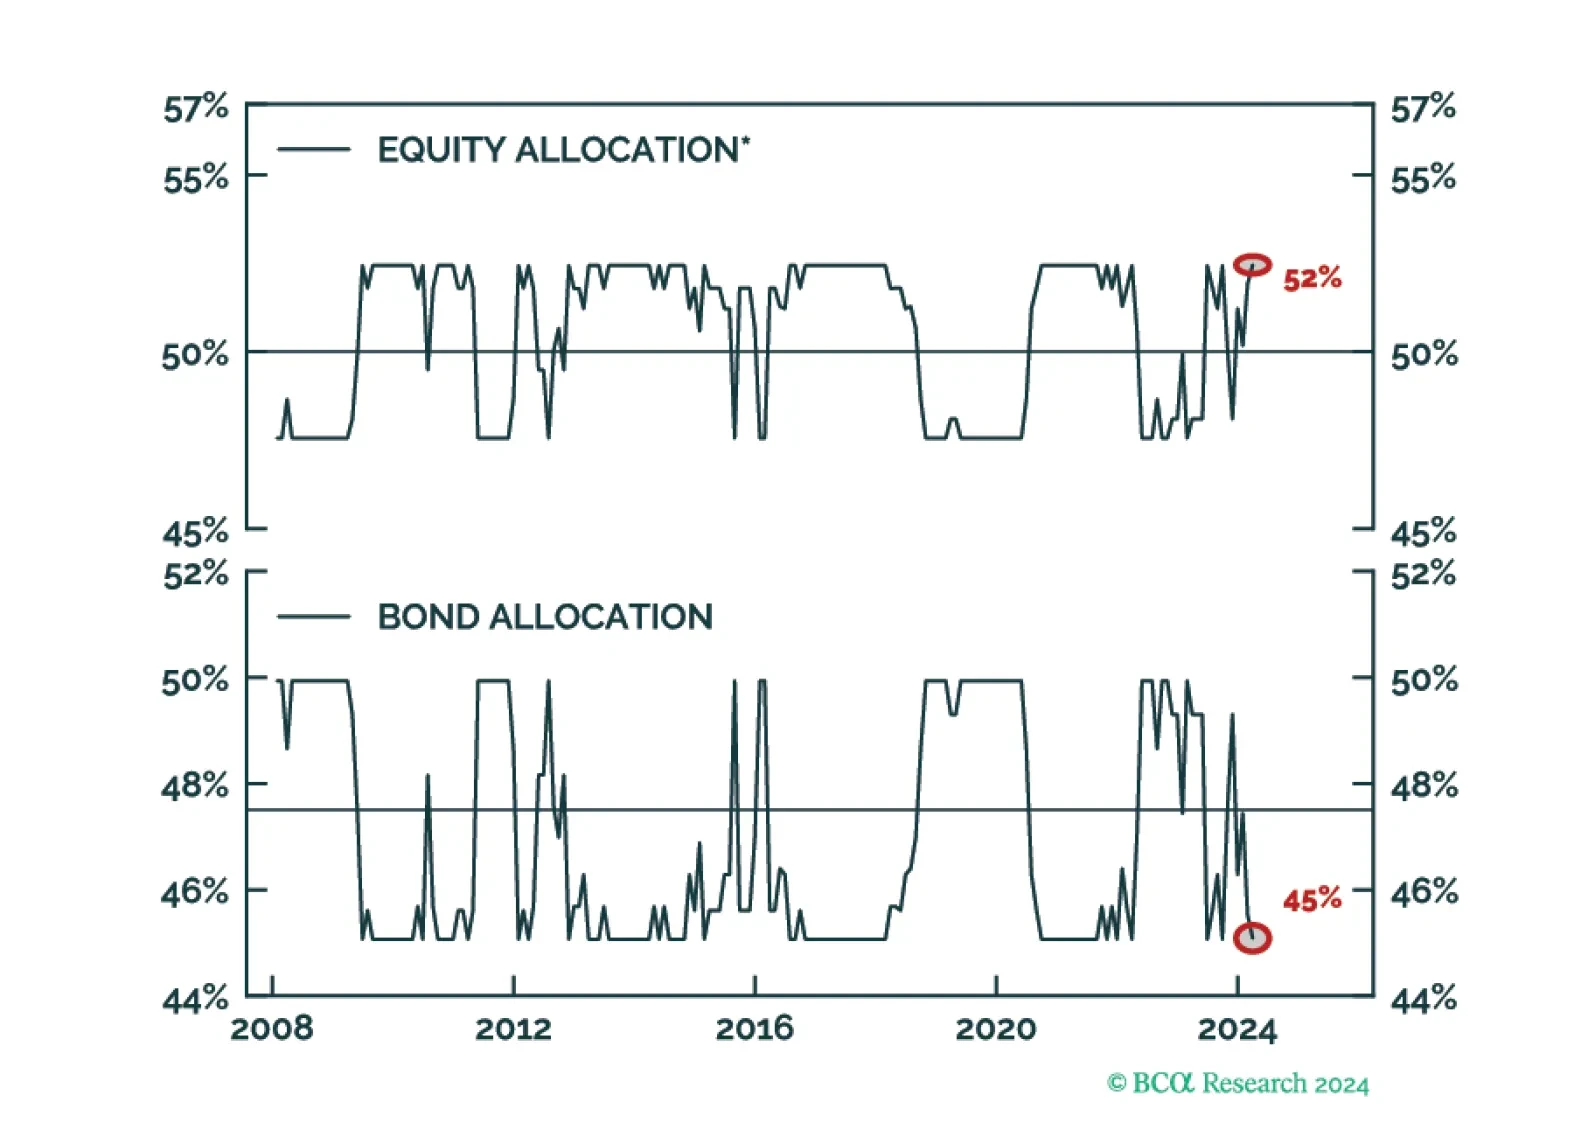
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
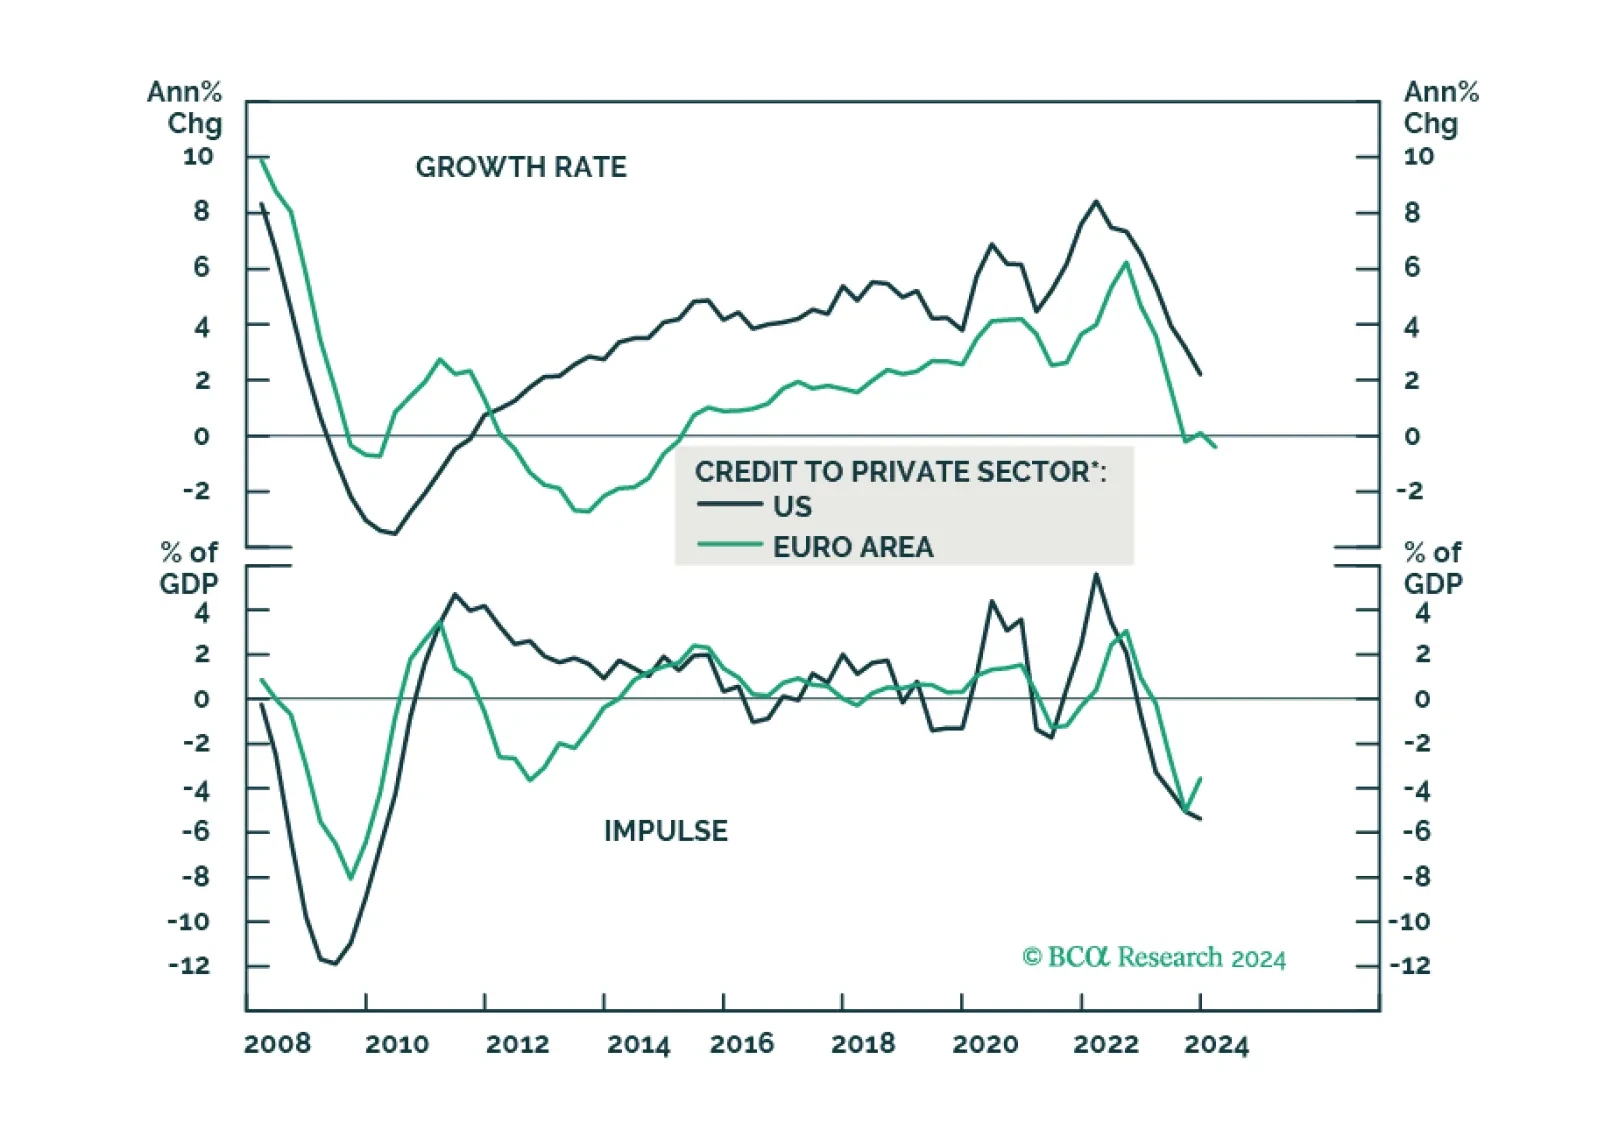
The global economy is wobbling precariously between slowing growth and reaccelerating inflation. This is unlikely to end well. Stay cautious, and hedge against both recession and inflation.
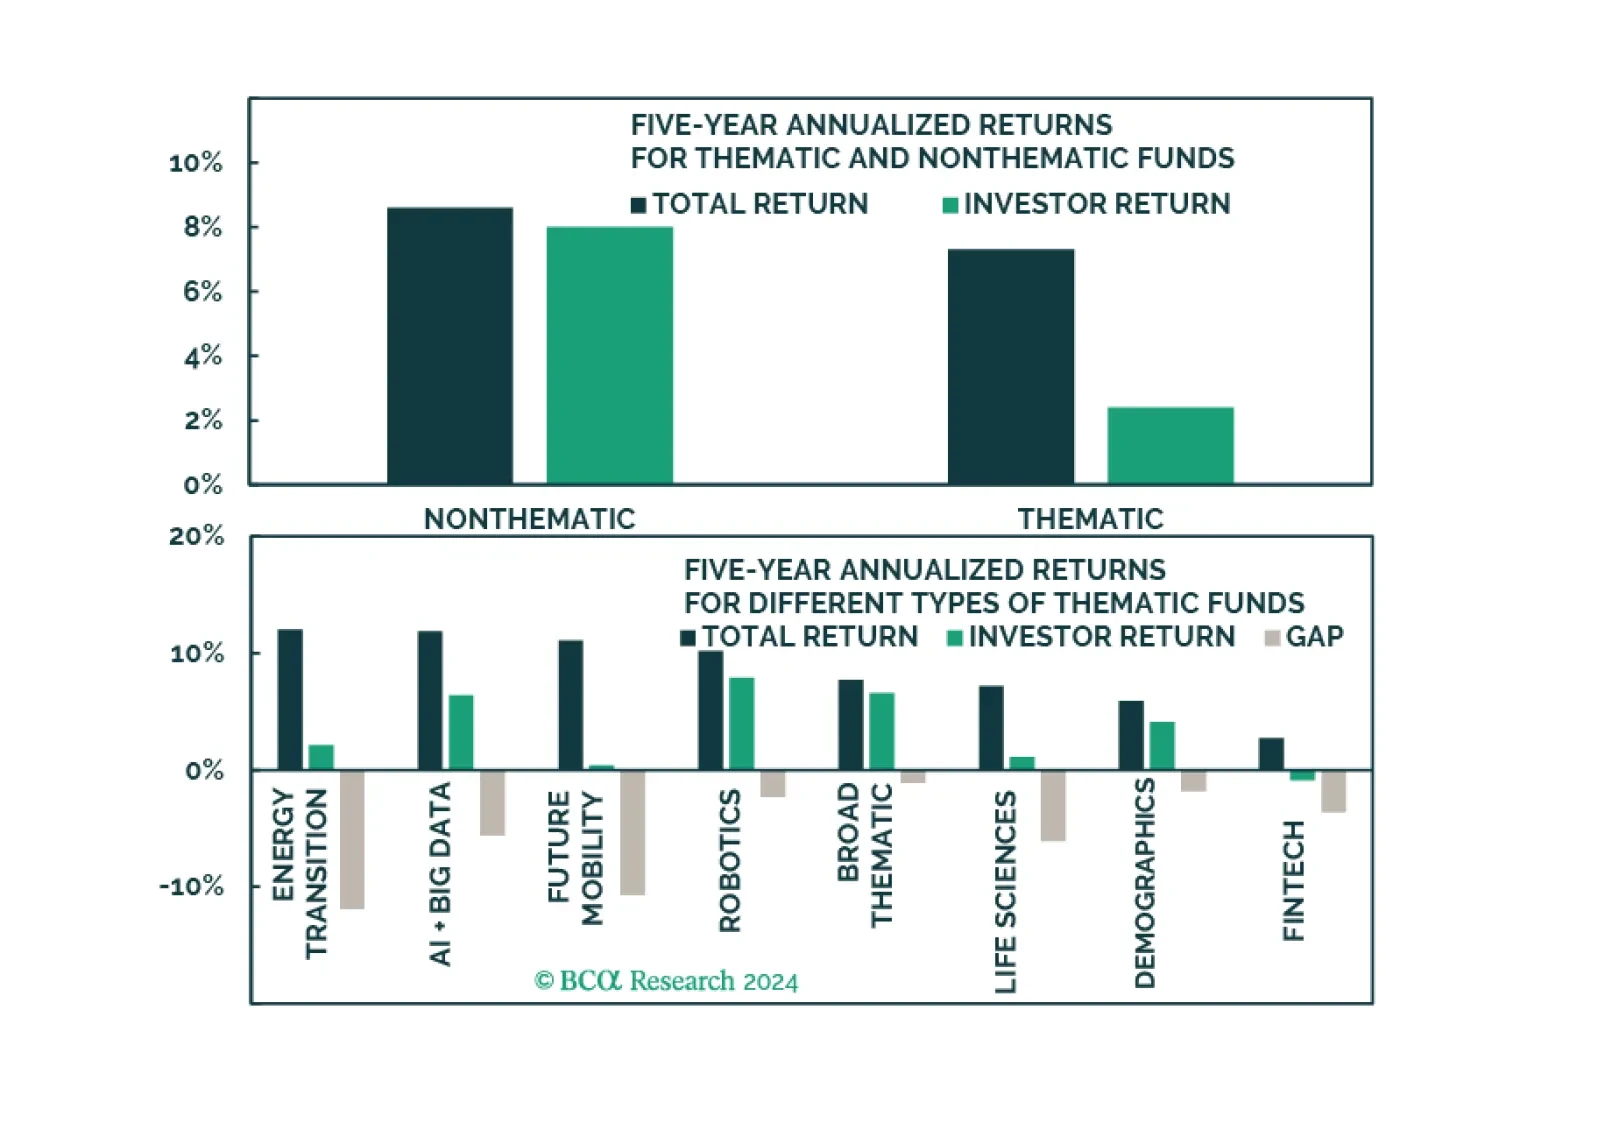
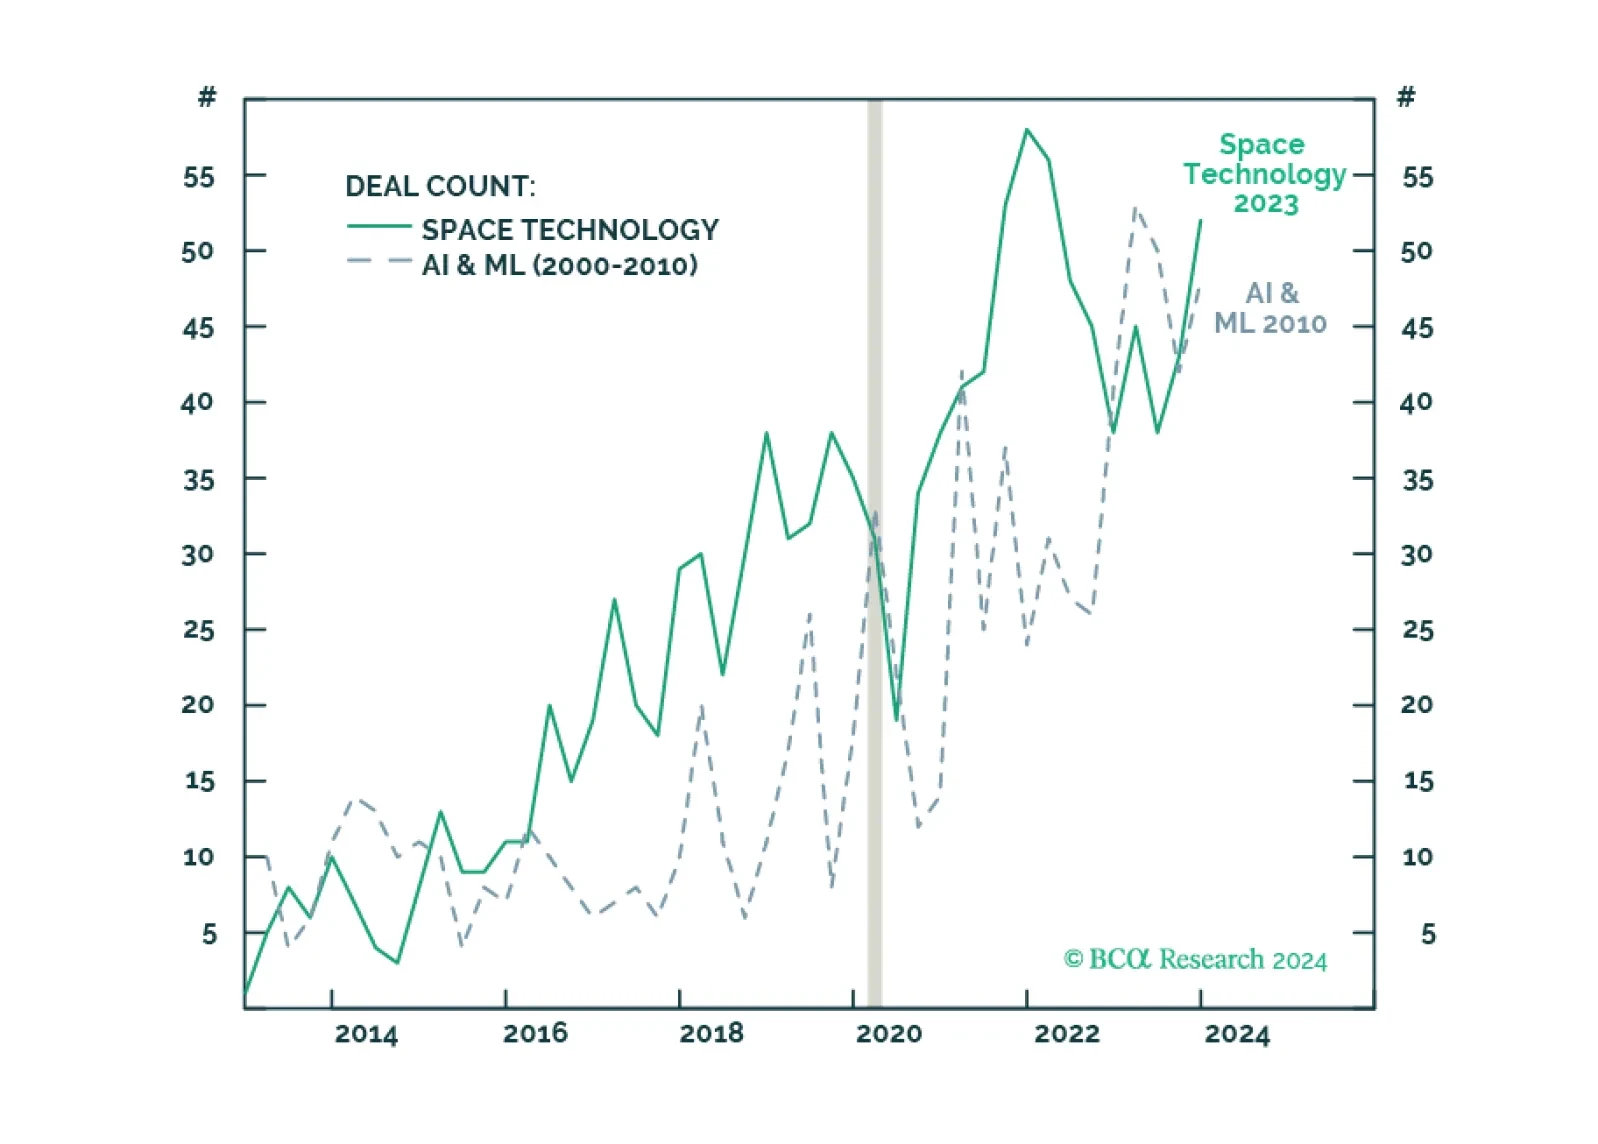
AI is not the Early-Stage bet investors should be making. It is obvious and highly competitive. Venture Capital is not about direct competition but about pioneering new directions. While everyone is distracted with AI, investors should look to Aerospace & Space Technology. Strategic buyers will provide exit opportunities.
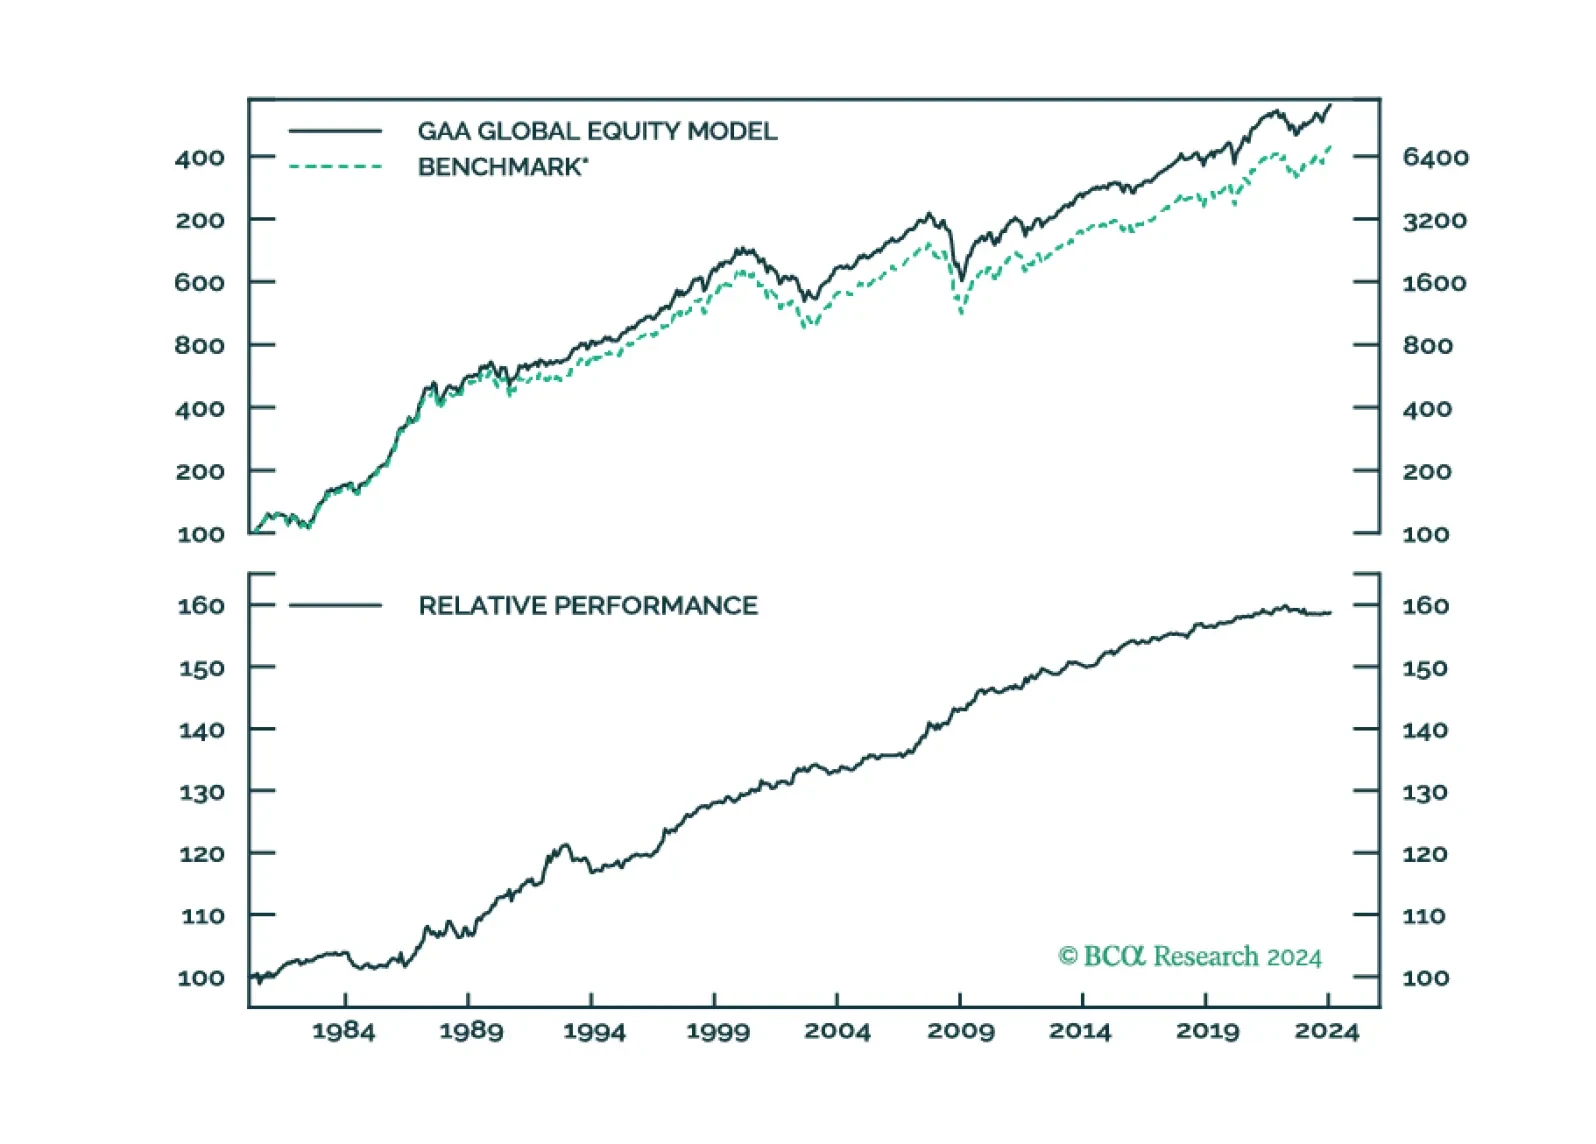
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
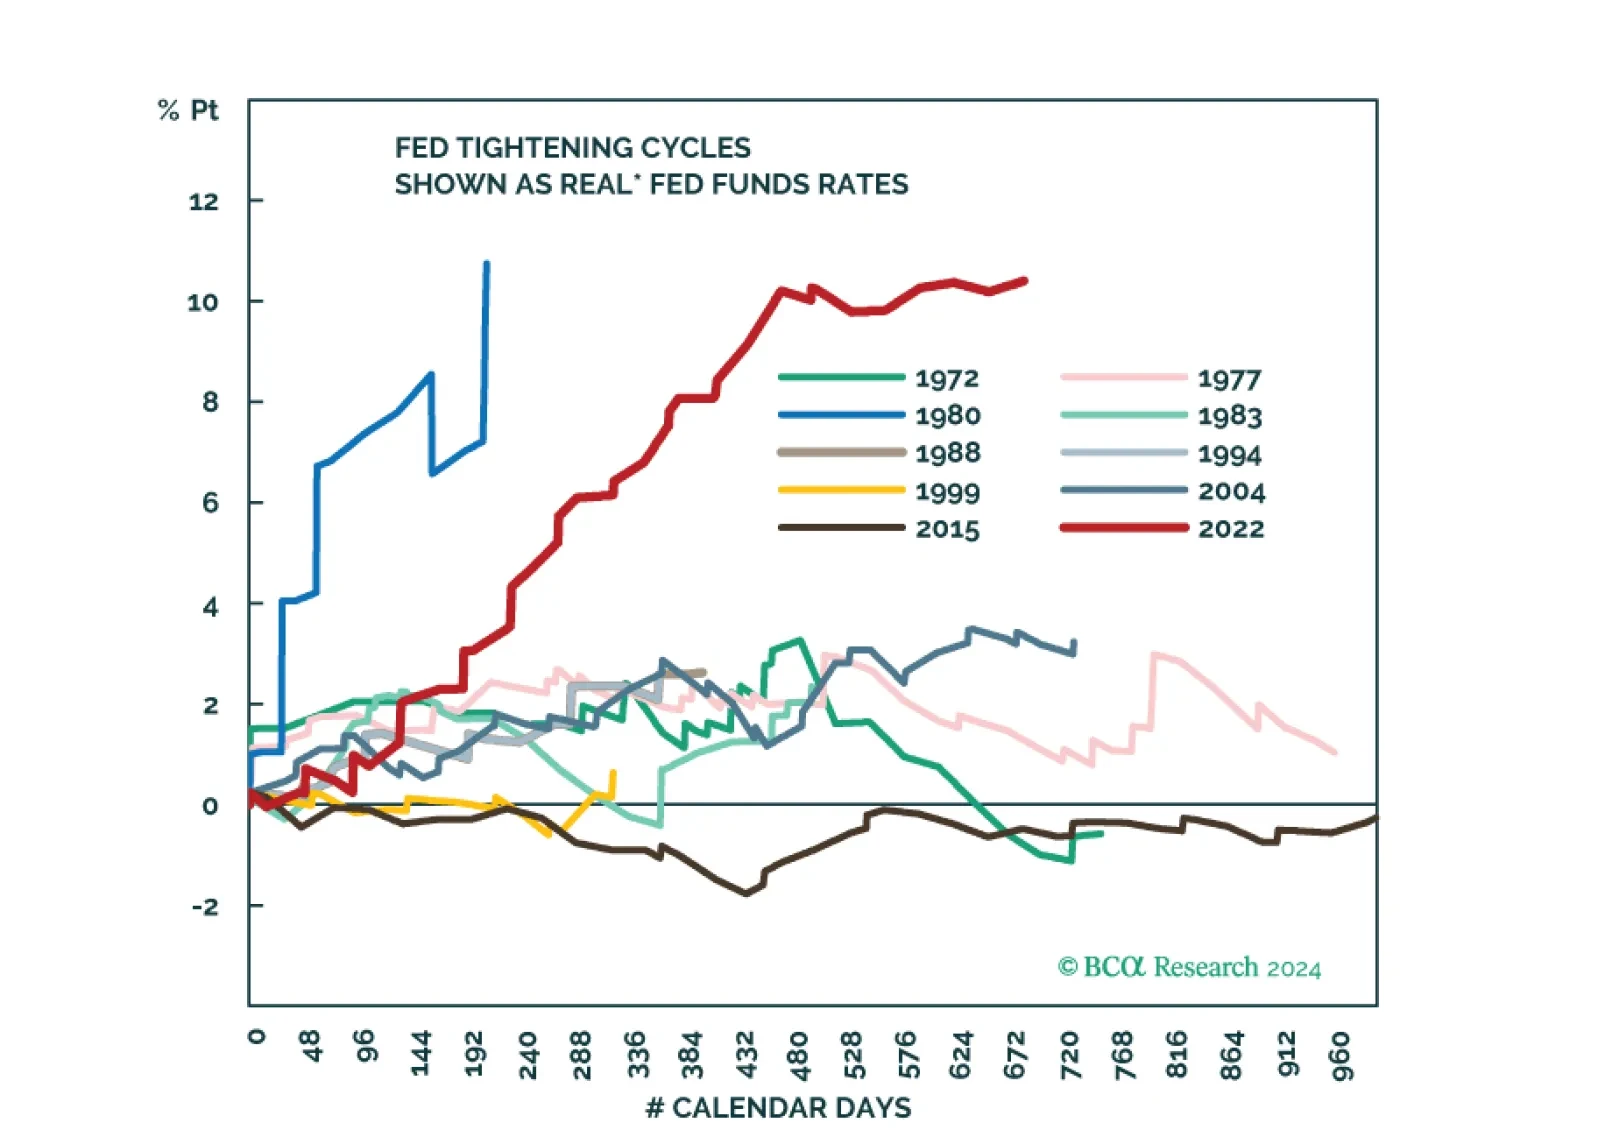
Amid patchy global growth, the US economy remains resilient. However, tight monetary policy will eventually trigger a recession in the US too. The stock market rally has been very narrow. Stay underweight risk assets.