Latest from BCA Research
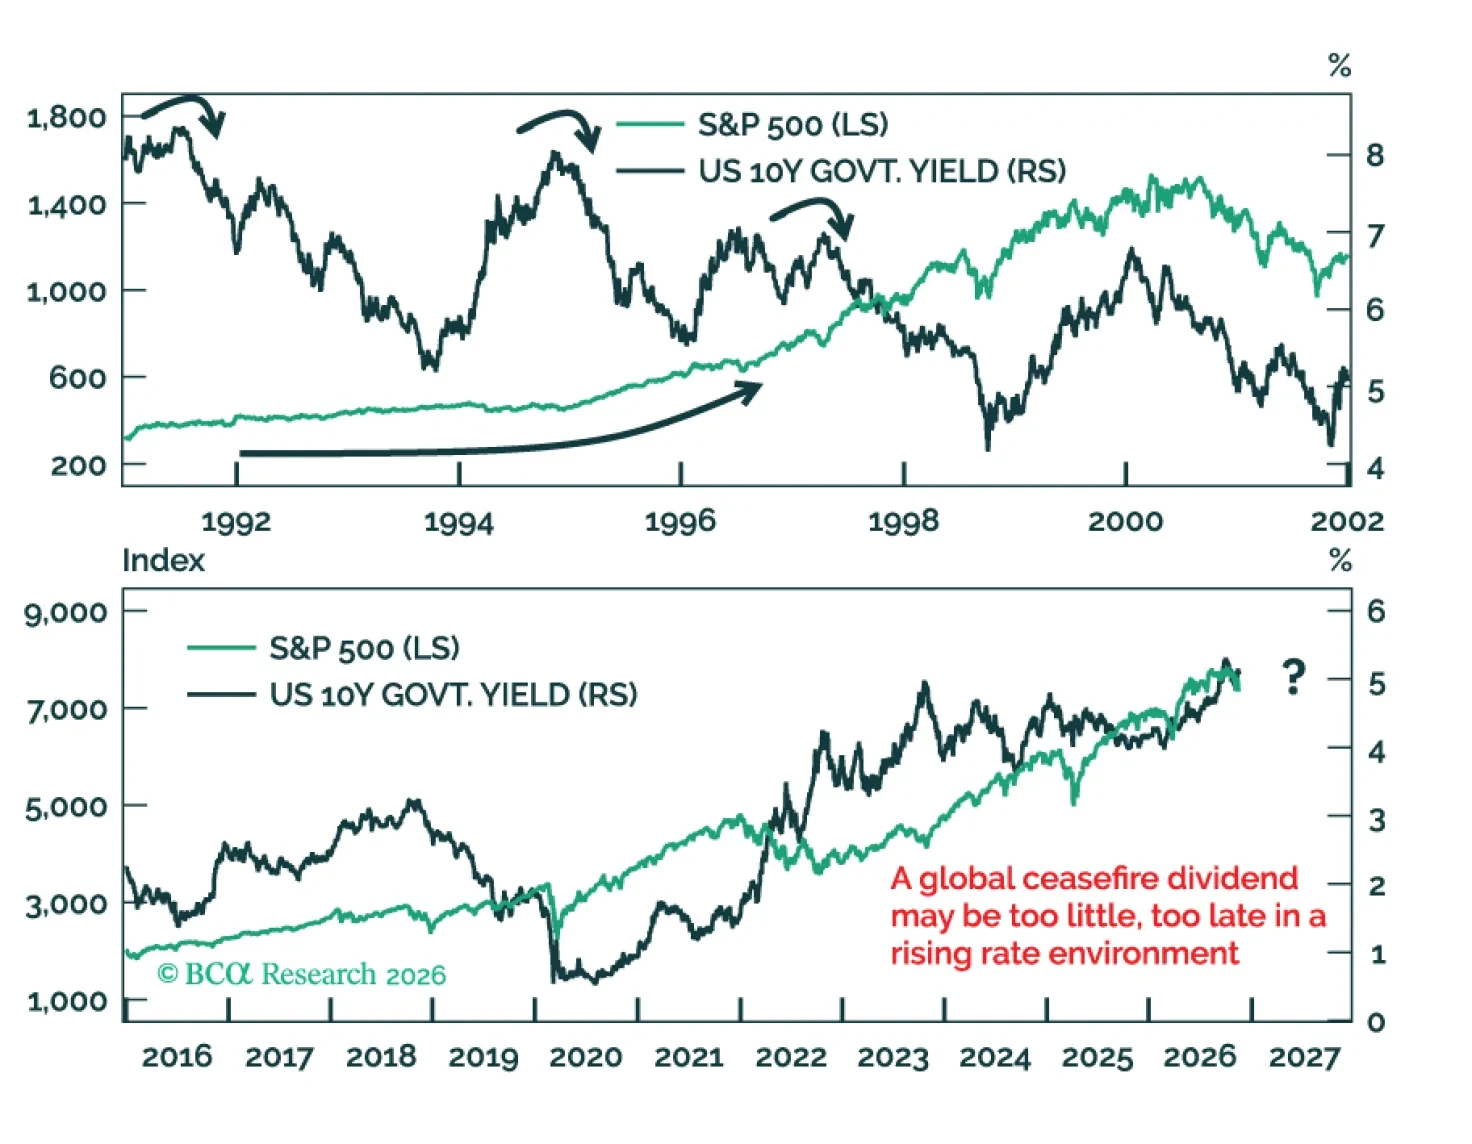
The trilateral summit between the US, Russia, and China shows how President Trump will pursue a global “ceasefire dividend” in 2027-28. But that dividend alone is not enough to sustain the bull market.
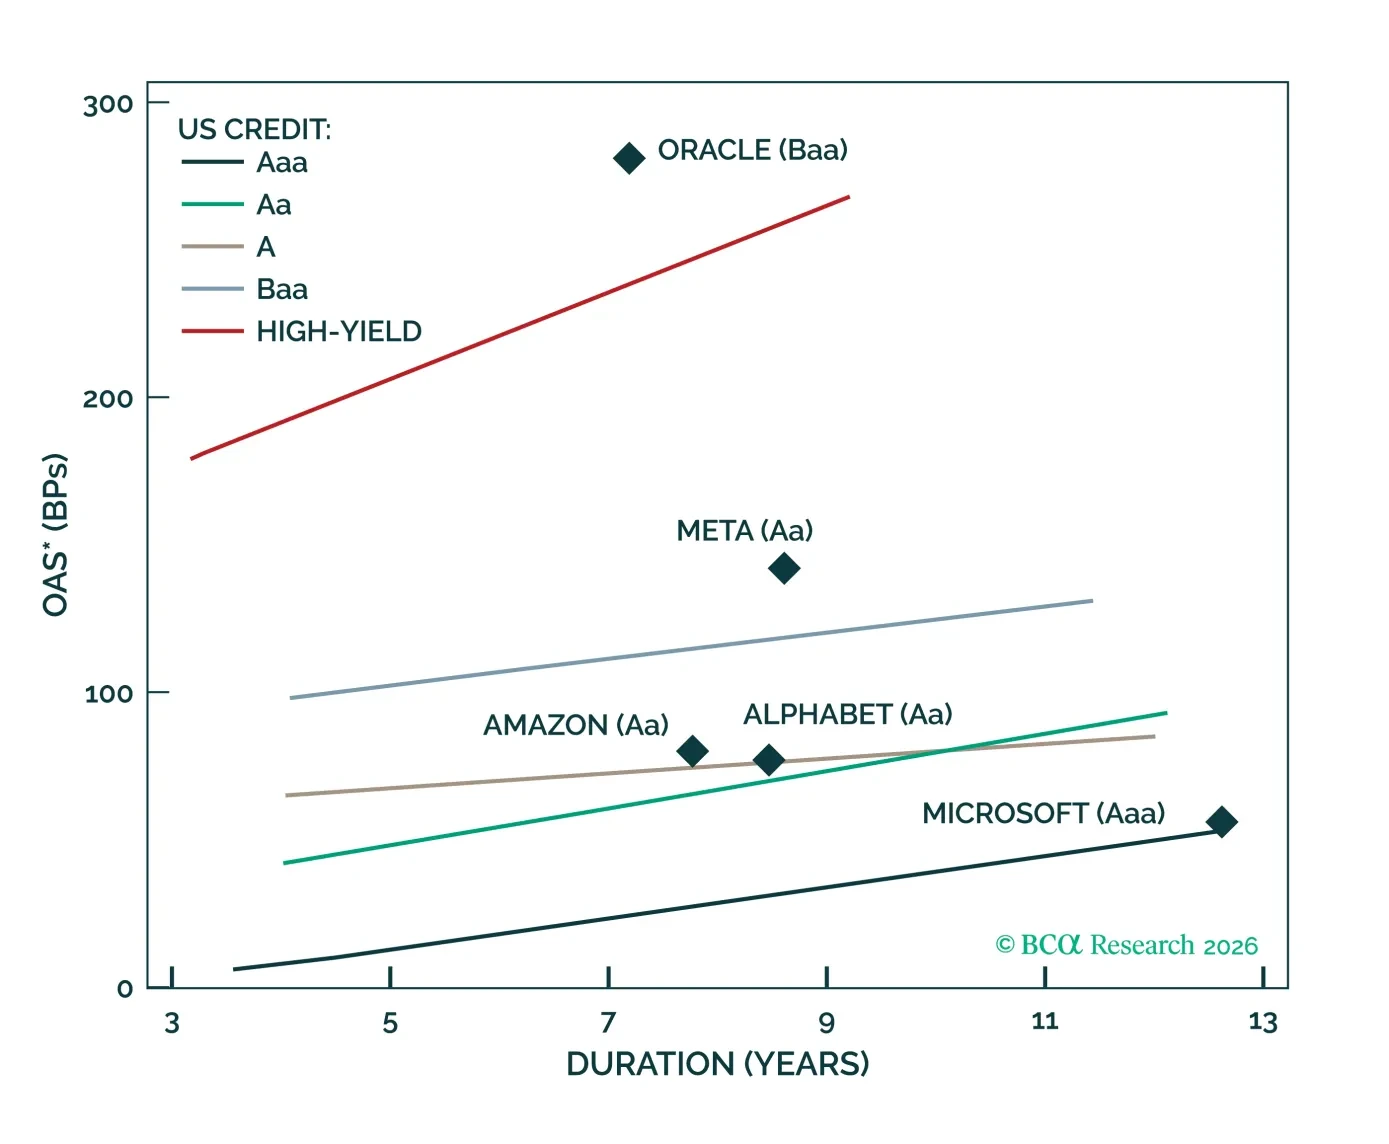
The hyperscaler repricing, European growth worries and stress in the lowest-rated junk bonds each tell a different story. We assess what drives spreads in each market and what it means for our corporate credit allocation.
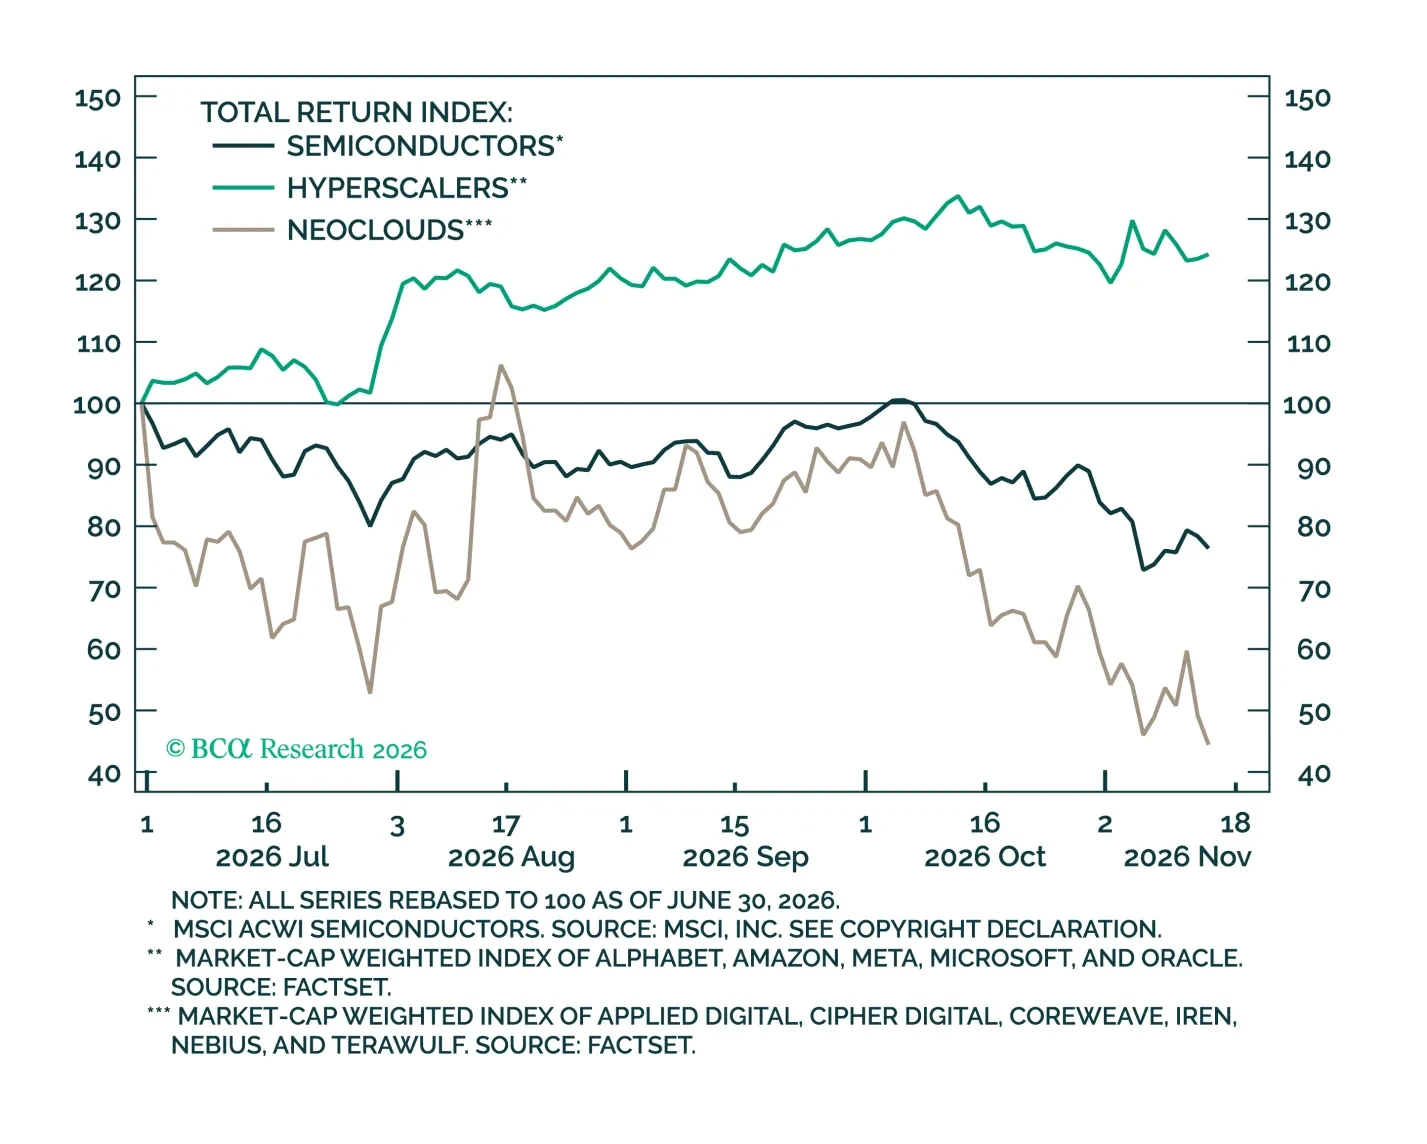
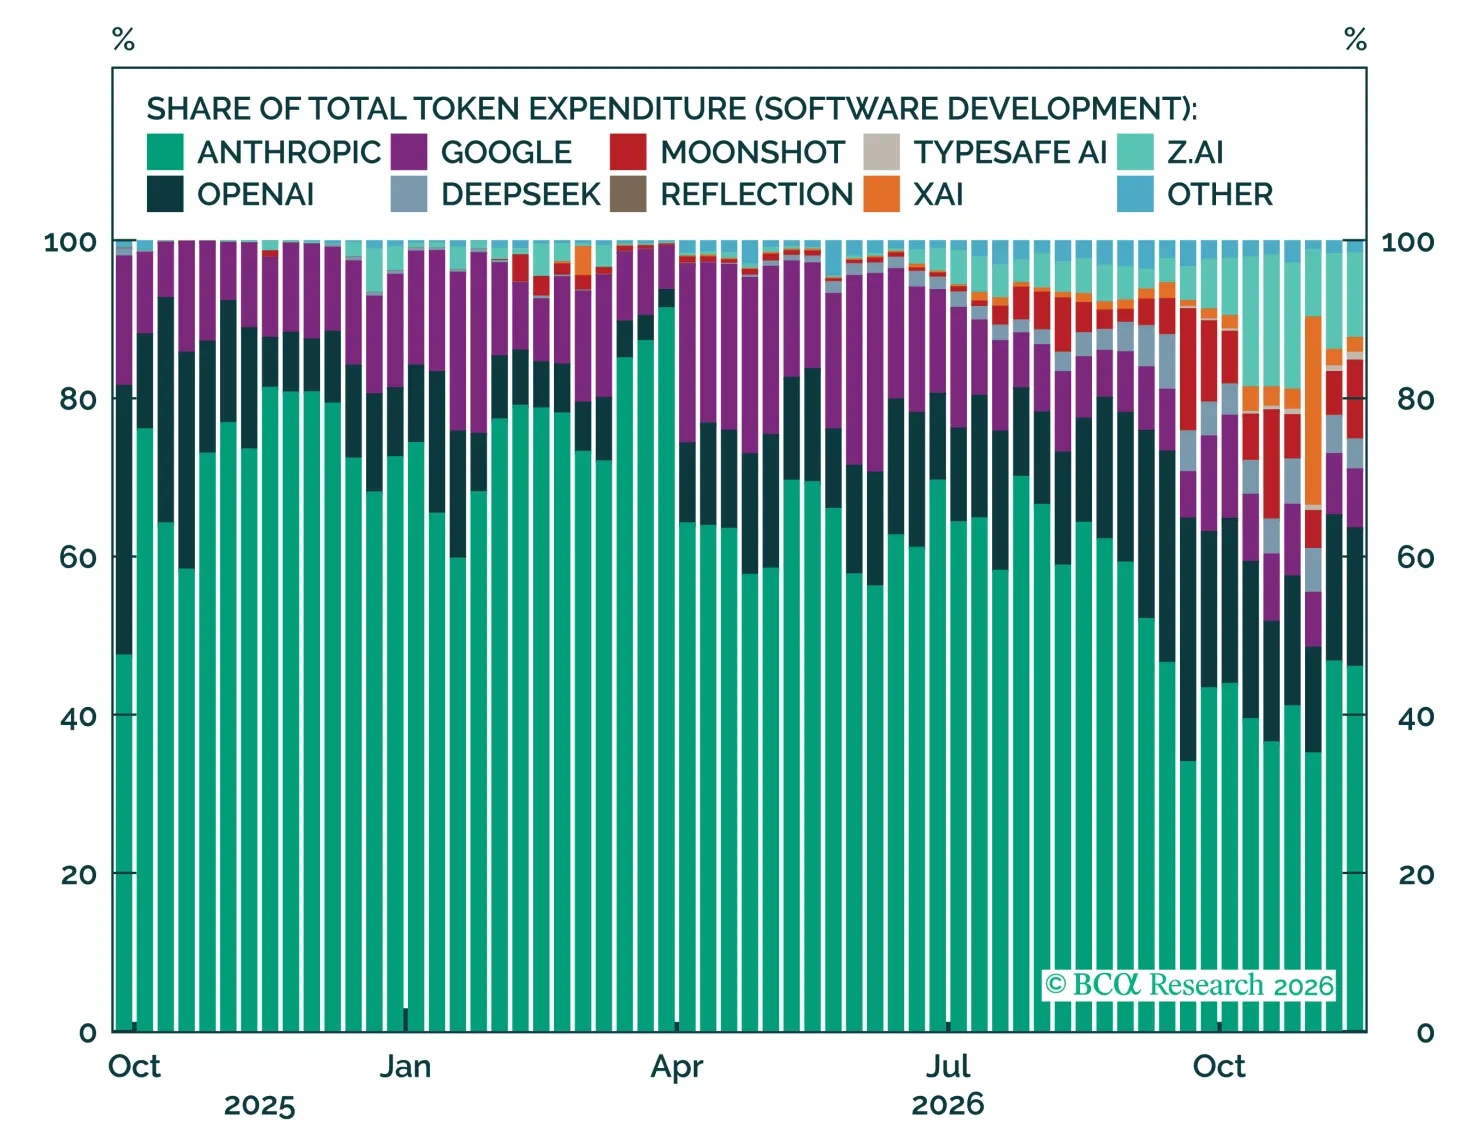
Expect Democrats to heed voters and pursue policies to reduce prices. The ousting of Huang is a blow to the neoclouds but a gift to frontier labs and hyperscalers. Downgrade Health Care and upgrade Consumer Discretionary. Upgrade Europe. Continue to favor the hyperscalers within the AI universe.
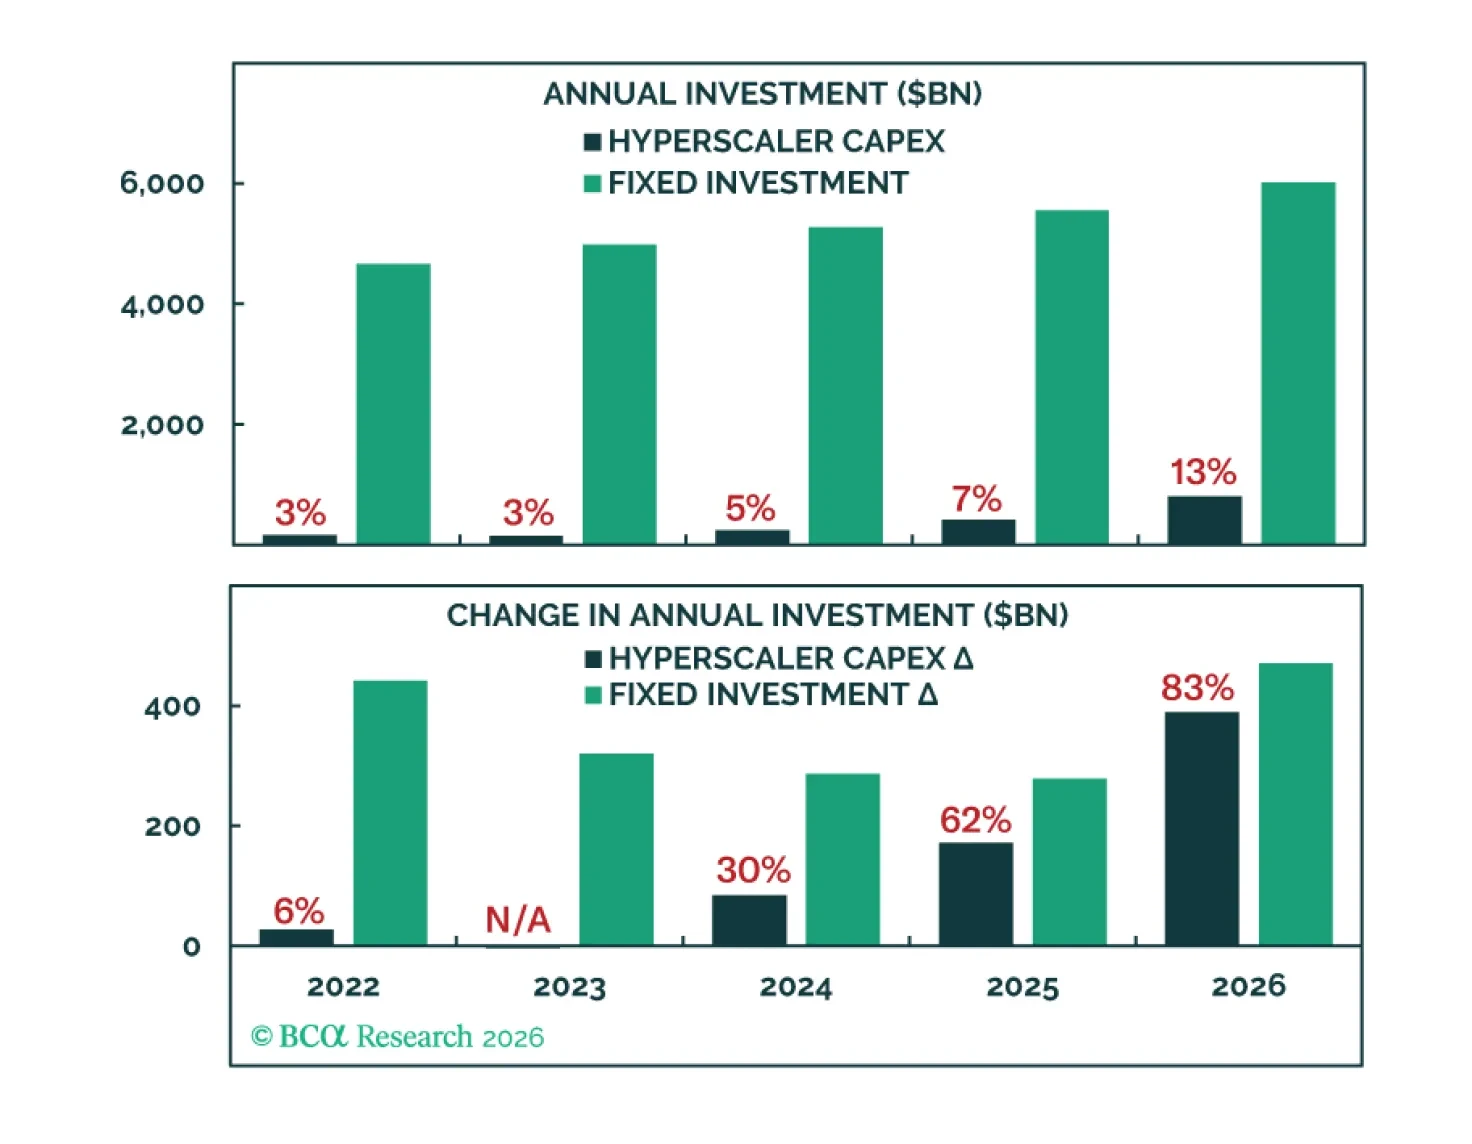
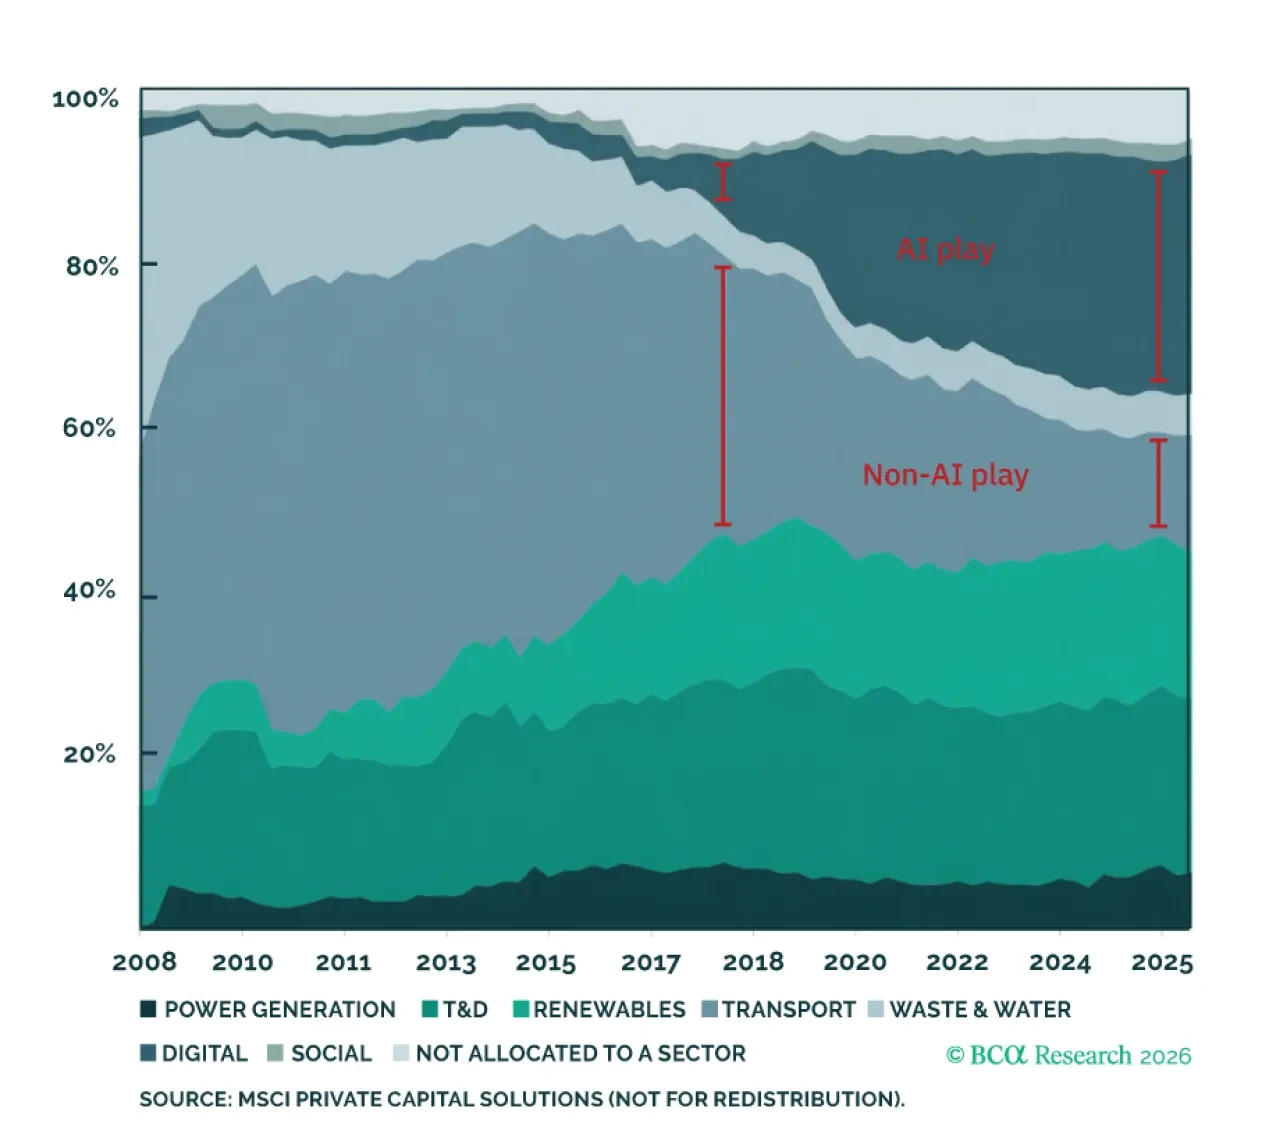
Data centers have swallowed aggregate US investment to such an extent that even a modest hyperscaler capex pullback could sink the expansion and bull market.
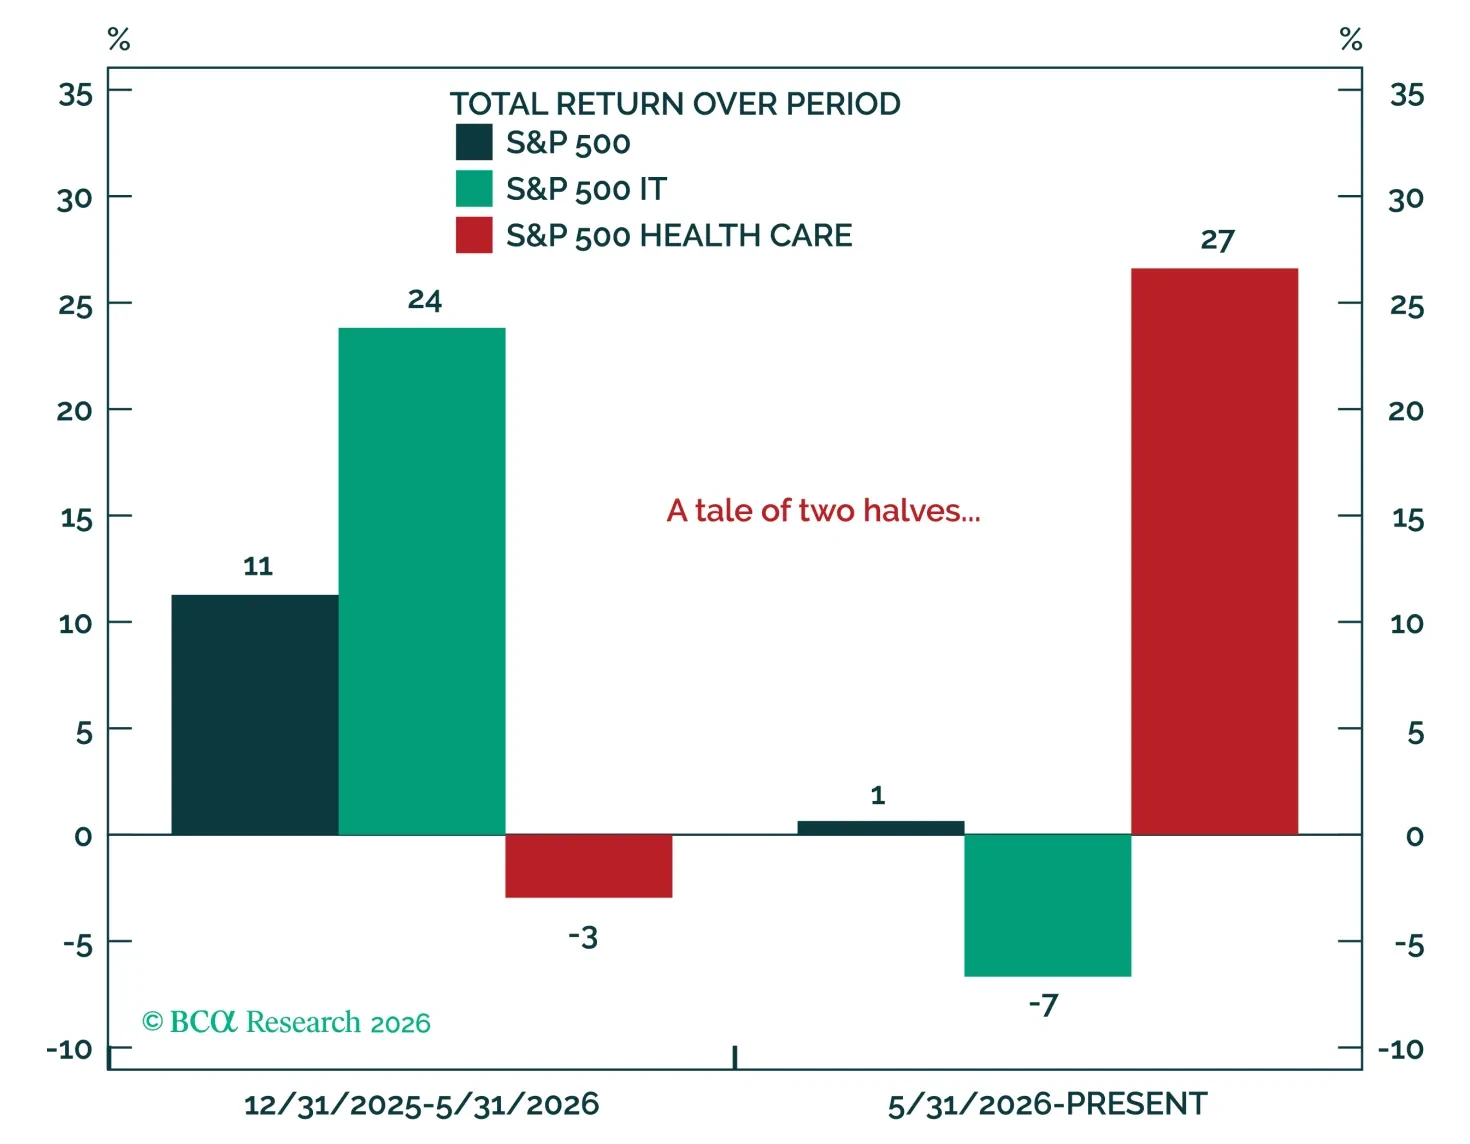
Health Care’s second-half 2026 rally has largely been a defensive rotation, not the start of a new bull market. Health Care leadership is more typical when the economy is slowing/contracting and is hard to sustain in a rising market. With the cycle still firm and our expectation that the market rallies into year end, we are neutral on the sector, though we recognize its hedging value. Within Health Care, we are underweight Providers & Services, overweight Equipment & Supplies, and market weight Pharmaceuticals, Biotech & Life Sciences (“Pharma”).
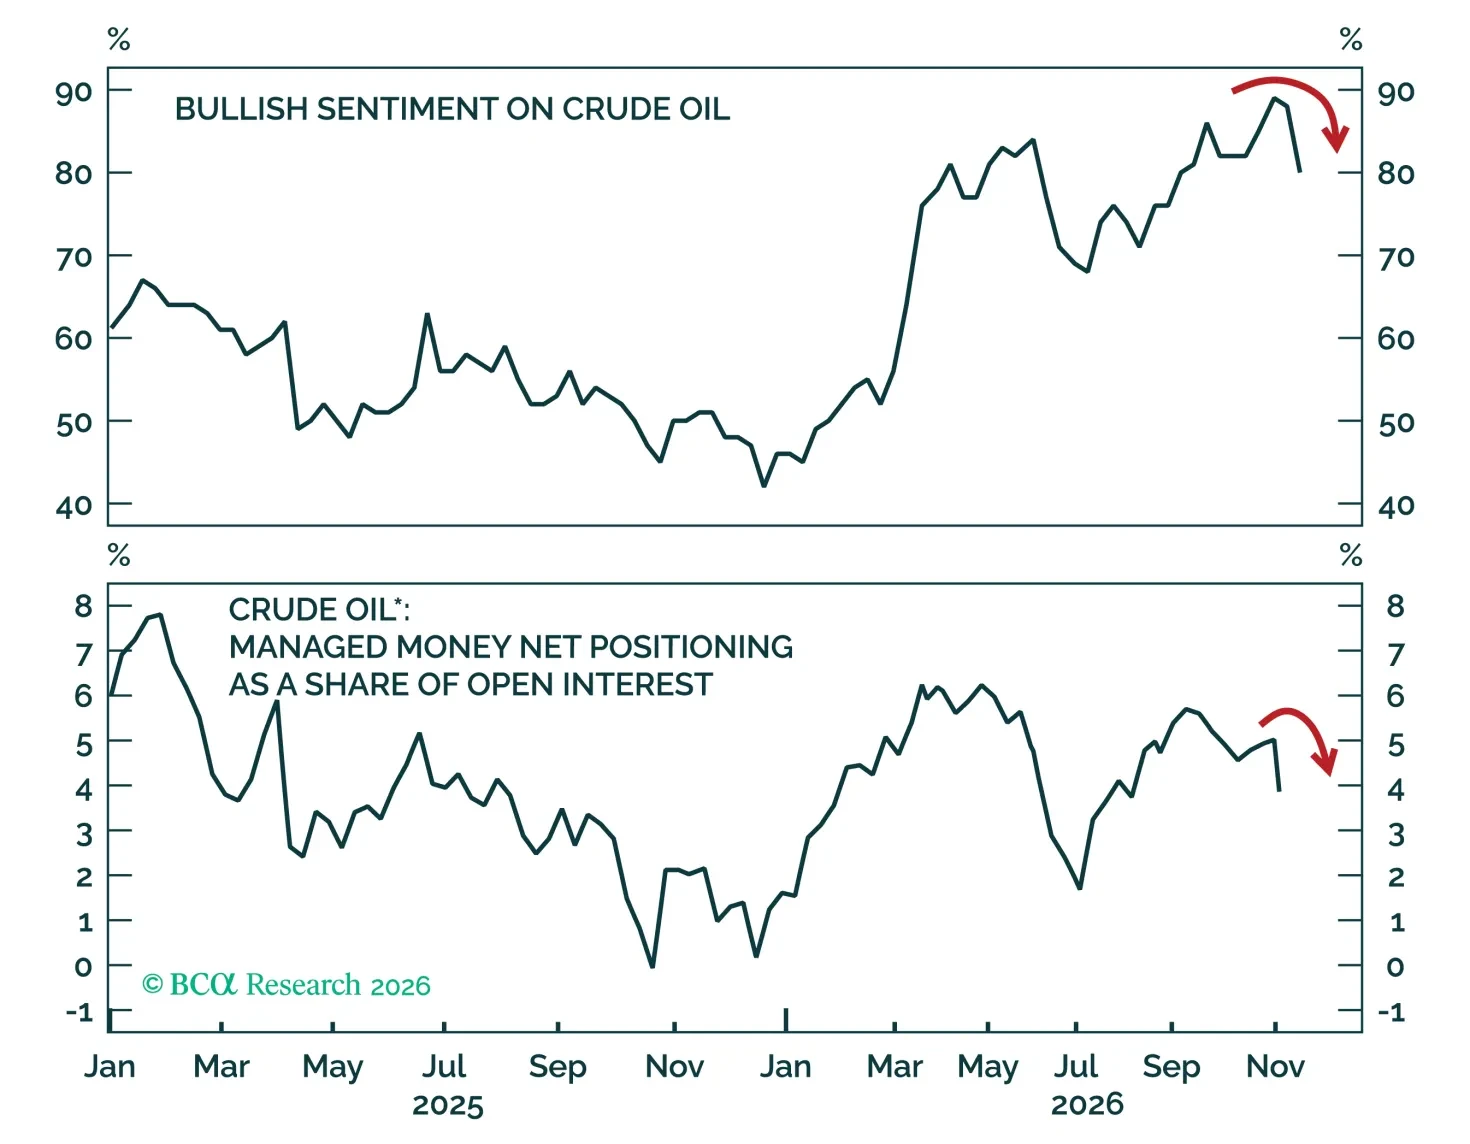
Oil’s recent price slide suggests markets are increasingly pricing in peace. But a swift US-Iran deal is far from assured, and depleted inventories leave prices exposed in the event of a renewed supply disruption. We explain why price risks now tilt higher.
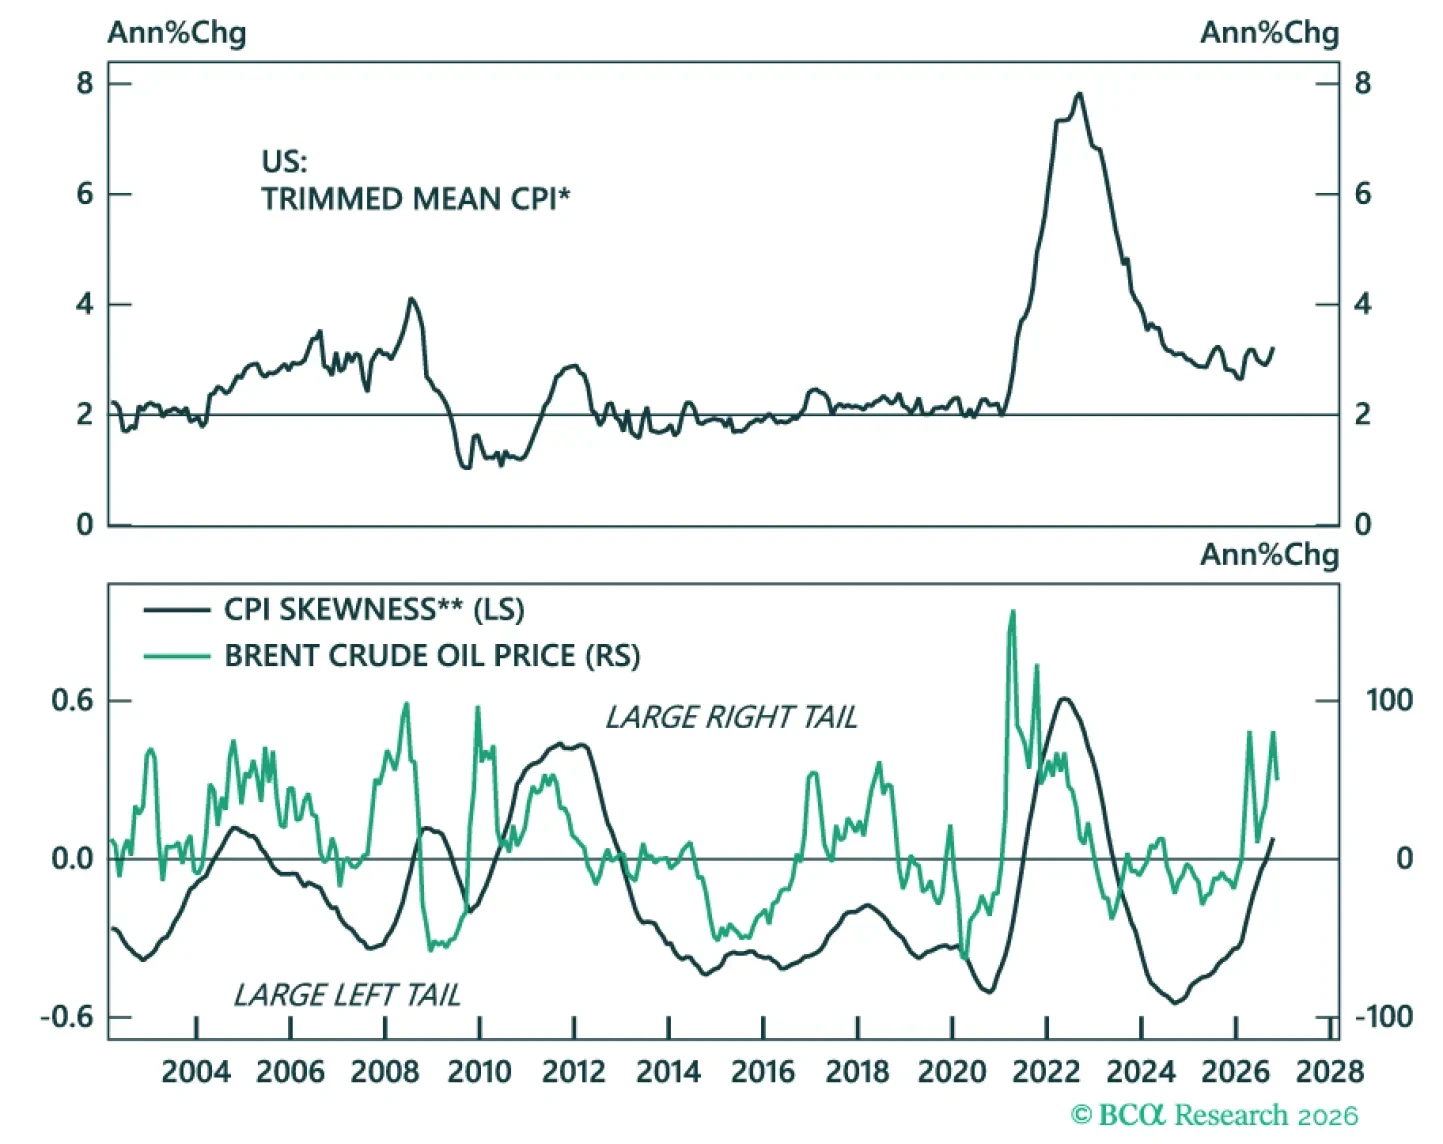
Central banks are trying to separate a narrow energy shock from broader inflation pressure. We introduce a trimmed mean, skew, and breadth diffusion measure to make that distinction across seven developed economies, and assess what it means for policy paths and bond positioning.
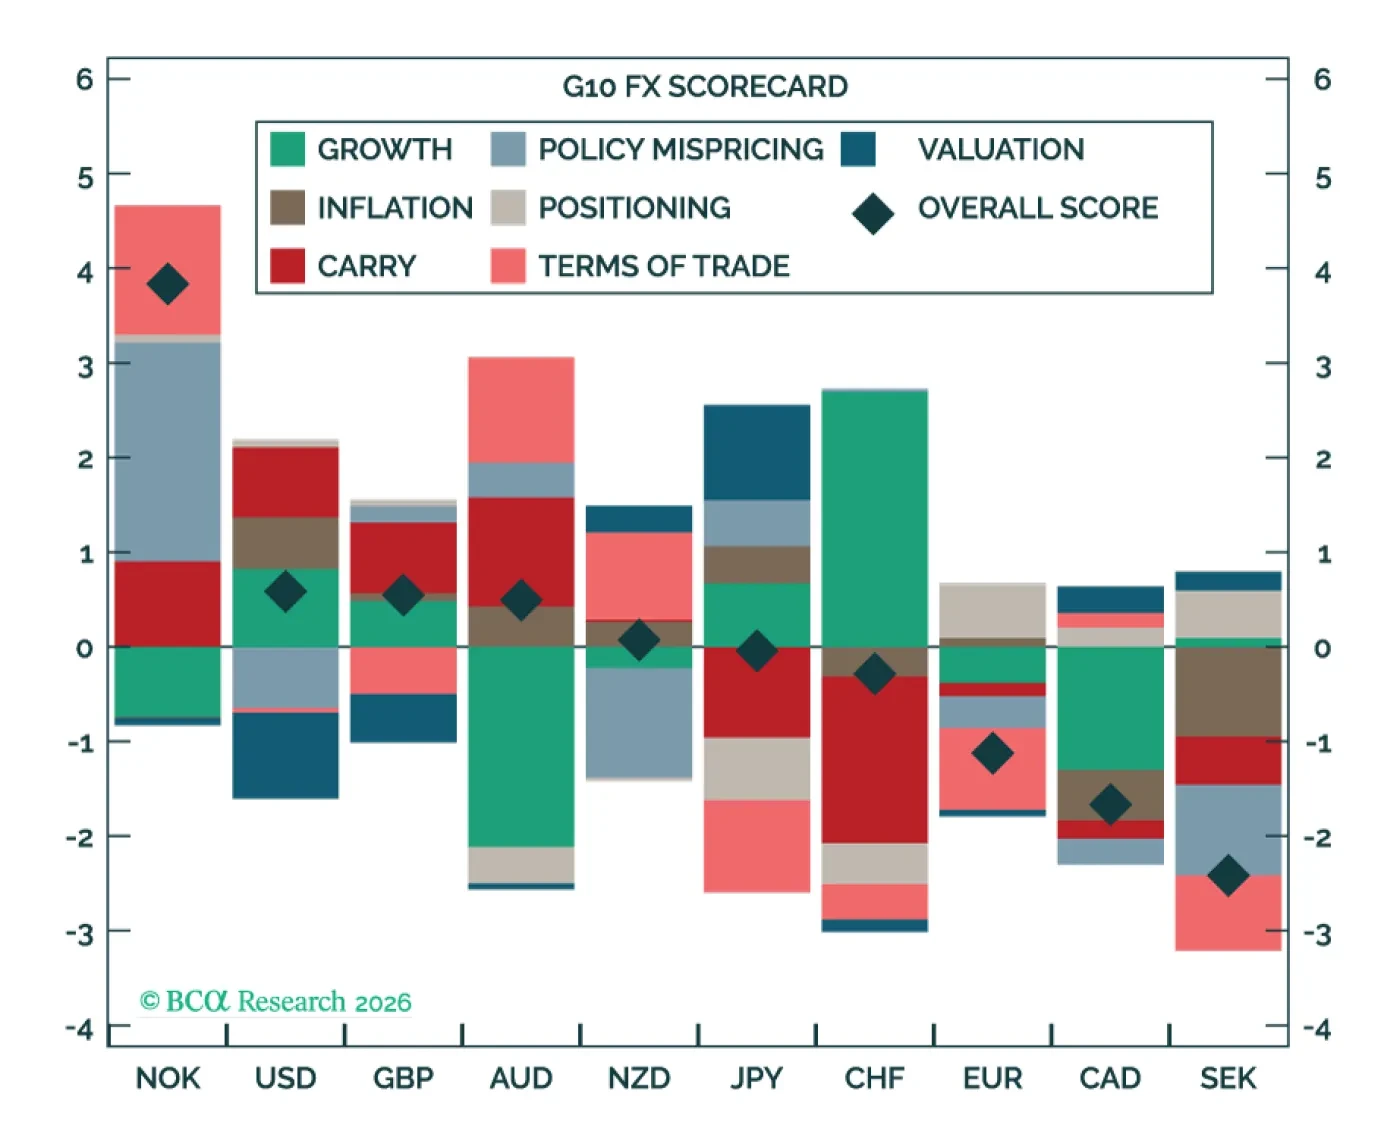
Carry still leads the G10 FX Scorecard, but diverging growth, inflation and rate signals suggest the cycle that drove returns over the past year may be nearing a turning point. We are shortening our horizon and watching for rotation opportunities in 2027.